French sovereign debt has re-emerged as the most consequential stress point inside the euro area, and the autumn of 2026 delivered the clearest warning yet that the currency bloc's fiscal fault lines remain dangerously active.
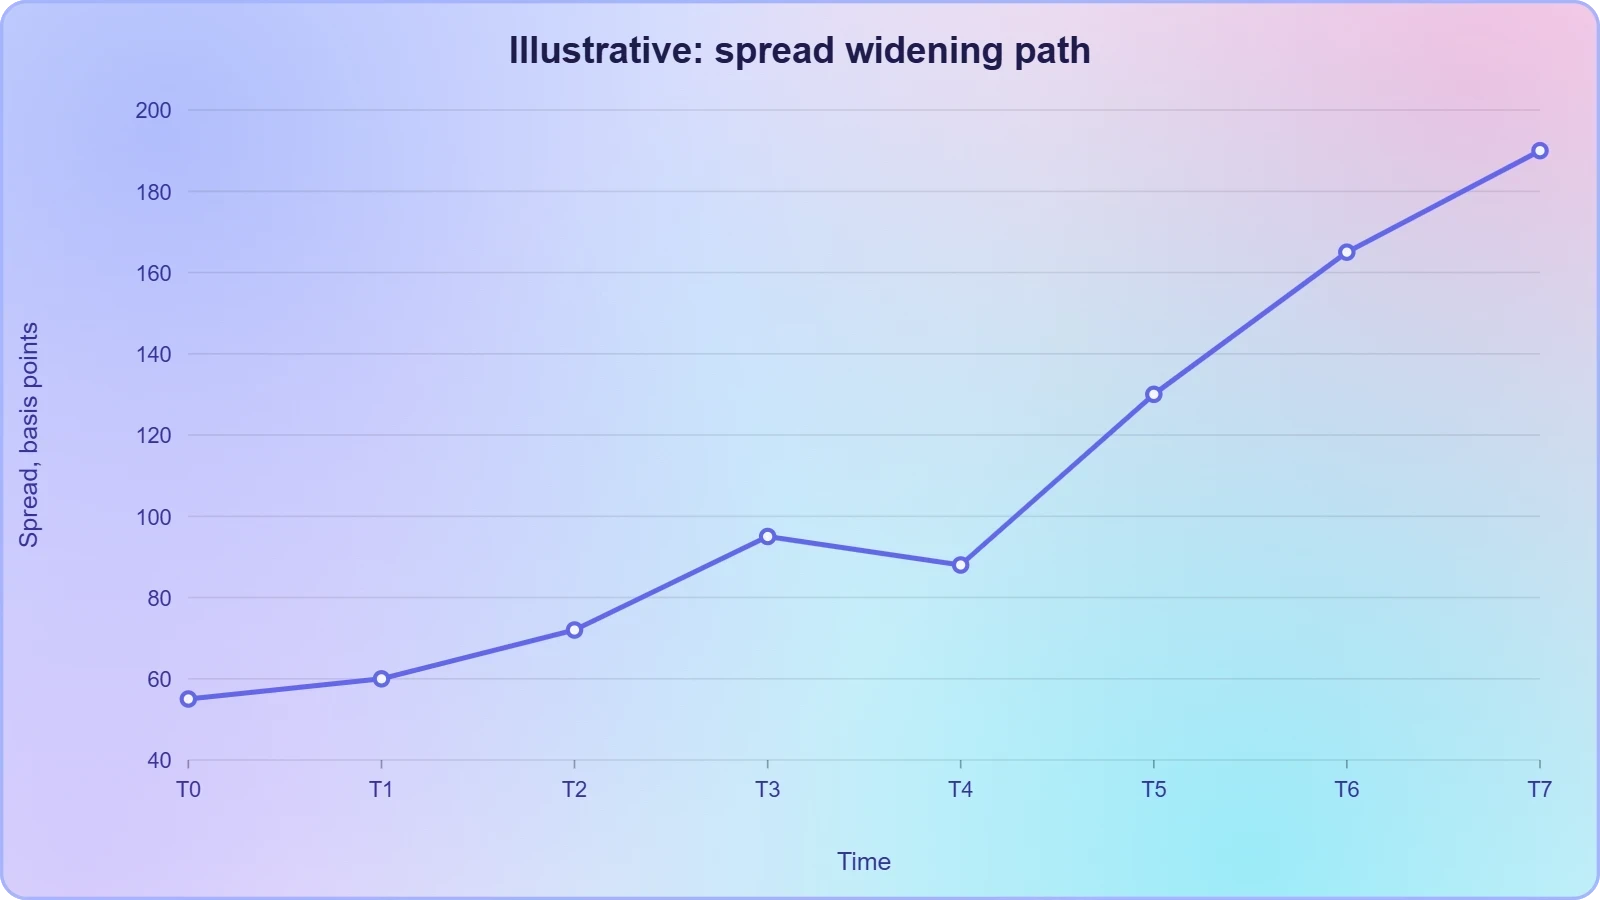
The spread between French and German ten-year yields has widened to territory not witnessed since the sovereign debt crisis of the early 2010s, while the cost of insuring French government obligations against default has climbed to its highest level in more than a decade.
These are not abstract market statistics; they are the price signals through which global capital renders judgment on a nation's fiscal credibility.
On This Page
What makes the moment so charged is the convergence of multiple weaknesses. France carries one of the heaviest public debt burdens in the advanced world, runs a deficit that has repeatedly overshot official targets, and now confronts growth so feeble that the government has trimmed its 2026 expansion forecast to a mere 0.5%.
Layer onto that a fractured political landscape incapable of delivering durable fiscal consolidation, and the ingredients for a confidence shock become self-evident. Investors are not reacting to a single data point but to a structural narrative of drift.
The broader anxiety is fragmentation—the condition in which nations sharing a single currency face radically divergent borrowing costs. When that divergence widens, debt service becomes costlier for the weakest members, market stress compounds, and the entire monetary union is tested.
This analysis dissects the mechanics of the French spread blowout, traces the historical parallels to the 2010–2012 crisis, and evaluates whether the euro area's reinforced architecture can absorb the strain this time.
TL;DR French borrowing costs have surged and the yield gap over Germany has widened to early-2010s crisis levels, with credit default insurance also hitting multi-year highs. France's combination of elevated debt, stubborn deficits, anaemic 0.5% growth, and political instability has forced investors to reprice sovereign risk. The euro has weakened nearly 5% against the dollar this year. While stronger banks and euro-area safeguards reduce the odds of a repeat of the Greece-led contagion, analysts including ING's Carsten Brzeski warn that volatility and cross-border spillovers remain live threats. The episode also echoes debt-sustainability anxieties in the United States and United Kingdom.
The Anatomy of a Sovereign Spread Blowout
A sovereign spread is far more than a number on a trading screen; it is the market's quantified verdict on relative creditworthiness. When the French-German ten-year differential widens, investors are demanding compensation for holding French risk instead of the pristine German benchmark. That compensation requirement ripples through every layer of the French economy, from corporate borrowing to household mortgages.
Why the French-German Gap Matters
The Franco-German spread functions as the euro area's most watched barometer of cohesion. Germany's bunds serve as the risk-free anchor of the currency union, so any widening of the French premium signals that investors no longer treat the two sovereigns as near-substitutes. That psychological shift is precisely what policymakers fear most.
Historically, a contained spread reflected market faith in French institutional strength and euro-area solidarity. The current widening dismantles that assumption and forces a repricing of risk across peripheral and core markets alike. Once investors begin differentiating among sovereigns, the process tends to feed on itself until a credible policy anchor restores calm.
Credit Default Swaps as a Fear Gauge
The cost of insuring French government debt against default has reached its highest level since the early 2010s, a signal that institutional investors are actively hedging sovereign exposure. Credit default swaps price the probability of a credit event, and their ascent confirms that the anxiety is not confined to yield markets. It reflects a genuine reassessment of tail risk.
When CDS premiums climb alongside cash-market spreads, the message is unambiguous: professional risk managers are paying real money to protect against a scenario they once dismissed as implausible. That hedging behaviour can itself become self-reinforcing, as rising protection costs push marginal investors toward the exit and deepen the funding squeeze.
France's Fiscal Fundamentals Under Scrutiny
Markets rarely punish nations without cause, and France's fundamentals provide ample justification for the repricing now underway. Public debt sits near the highest levels in the euro area relative to output, while budget deficits have persistently exceeded the thresholds enshrined in European fiscal rules. The trajectory, not merely the level, is what unsettles investors.
Debt, Deficits, and the Growth Trap
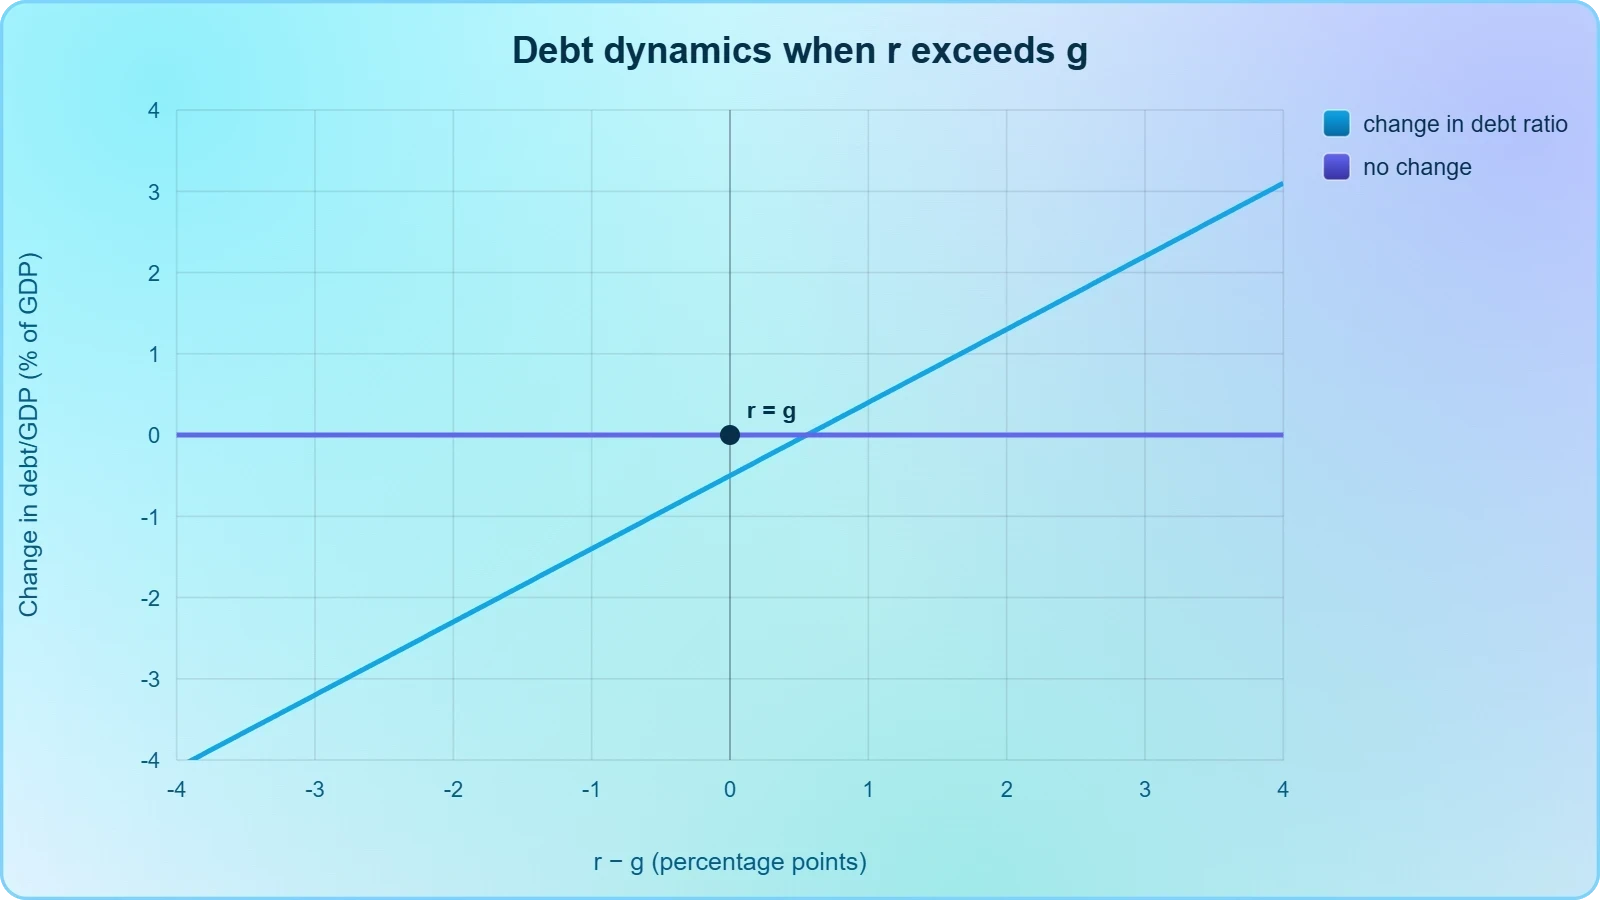
The government's decision to slash its 2026 growth forecast to 0.5% crystallises the core dilemma. Slower expansion erodes tax receipts precisely when debt service costs are climbing, creating a vicious arithmetic in which borrowing rises to cover shortfalls that weak growth keeps widening. This is the classic debt spiral in slow motion.
Mathematically, the dynamics are unforgiving. When the effective interest rate on debt exceeds nominal growth, the debt ratio expands even without fresh borrowing:
Here ##d## represents the debt-to-GDP ratio, ##r## the effective interest rate, ##g## nominal growth, and ##pb## the primary balance. With growth collapsing toward zero and yields rising, France's ##(r - g)## term turns decisively positive, demanding large primary surpluses that its politics cannot currently deliver.
Political Instability as a Risk Multiplier
Fiscal credibility ultimately rests on political capacity to legislate consolidation, and France's fragmented parliament has repeatedly demonstrated its inability to do so. Successive governments have struggled to pass budgets, and each episode of gridlock reinforces investor scepticism about the durability of any adjustment plan. Markets price not intentions but enforceable commitments.
Political instability compounds the fiscal problem because it shortens time horizons. Governments facing imminent collapse cannot impose painful reforms, and opposition forces have little incentive to co-operate on austerity. The result is a structural bias toward deficit drift, which investors recognise and discount through wider spreads and higher hedging costs.
We Also Published
Lessons From the 2010–2012 Euro Crisis
The ghost haunting today's markets is the sovereign debt crisis that nearly tore the euro apart between 2010 and 2012. Then, stress originating in Greece cascaded through Portugal, Ireland, Italy, and Spain in a contagion that exposed the currency union's fundamental design flaw: monetary integration without fiscal union. The parallels to today's French episode are uncomfortable.
The Contagion Mechanism Explained
During the earlier crisis, governments were implicitly expected to rescue domestic banks holding vast quantities of their own sovereign debt. This created a doom loop in which bank weakness and sovereign weakness reinforced each other, driving yields higher and making refinancing progressively harder. The cycle only broke when credible backstops emerged.
Rescue programmes tied to austerity measures eventually stabilised the periphery, but the decisive intervention came in 2012 when the European Central Bank pledged to do "whatever it takes" to preserve the euro. That commitment, backed by the promise of unlimited bond purchases, fundamentally altered market psychology and compressed spreads across the bloc.
What Has Changed Since Then
Analysts broadly agree that stronger bank balance sheets and reinforced euro-area safeguards make a full replay of the crisis less probable. Banking union, stricter capital requirements, and the European Stability Mechanism provide buffers that simply did not exist in 2010. The architecture is more resilient, though not invulnerable.
Yet resilience is not immunity. Economists caution that further volatility and cross-border spillovers remain entirely possible, particularly if political dysfunction prevents credible fiscal adjustment. The safeguards buy time; they do not manufacture the political will that France currently lacks. Markets understand this distinction acutely.
- 01
- 02
- 03
- 04
The Currency Channel and Global Spillovers
Sovereign stress never stays confined to bond markets, and the euro's near-5% decline against the dollar this year illustrates how quickly fiscal anxiety transmits into currency pricing. A weaker euro raises imported inflation, complicates the ECB's policy calculus, and signals diminished global confidence in euro-area assets. The exchange rate has become an amplifier of the fiscal narrative.
Why the Euro Is Under Pressure
Currency markets price relative confidence, and capital flows toward economies perceived as fiscally credible. As French risk premia widen, marginal investors rotate out of euro-denominated assets, pressuring the single currency. The depreciation is orderly so far, but it adds a second front of instability for policymakers already wrestling with sovereign spreads.
A weaker euro also complicates the inflation picture, potentially forcing the ECB into a policy stance that suits neither the strong core nor the stressed periphery. This tension between monetary needs and fiscal realities is precisely the kind of fragmentation the currency union was never designed to manage gracefully.
The Debt-Fear Feedback Loop
Nobel laureate Paul Krugman observed in an October 8 blog post that a slowdown in bond purchases raises the risk a government could be forced into default for lack of cash to pay interest and principal. Fear of default, he noted, can then trigger further capital flight and even higher interest rates. The logic is circular and corrosive.
This feedback loop explains why sovereign stress can escalate faster than fundamentals alone would suggest. Once investors begin pricing default probability, the resulting capital flight raises borrowing costs, which worsens the fiscal position, which validates the original fear. Breaking that loop requires a credible anchor, whether political or institutional.
Parallel Debt Anxieties in the US and UK
France is not an isolated case, and economists increasingly note a similar cycle unfolding in the largest advanced economies. In both the United States and the United Kingdom, concern about rising government debt is pushing up yields and interest costs, which in turn adds to the debt burden. The dynamic is structurally identical, even if the political contexts differ.
The Universal Arithmetic of Rising Yields
Across these economies, the mechanism is the same: as investors demand higher compensation for holding sovereign debt, governments face larger interest bills, which widen deficits, which require more issuance, which further pressures yields. This reflexive loop transforms debt sustainability from a static accounting question into a dynamic market judgment.
The implication is sobering for fiscal planners everywhere. Even modest increases in average borrowing costs, compounded over years, can add percentage points of GDP to debt service. In an era of elevated issuance and diminished central bank bond purchases, the margin for error has narrowed considerably across the developed world.
Why France Still Stands Apart
Despite these parallels, France's position carries distinctive risks because it lacks the monetary sovereignty of the US and UK. Washington and London borrow in currencies they control and issue; Paris shares the euro with nineteen other members and depends on collective institutions. That asymmetry magnifies the consequences of any loss of confidence.
France also enters this episode with less fiscal headroom than its peers, having accumulated debt through repeated deficits without the growth dividend that might justify it. The combination of shared currency, high debt, weak growth, and political paralysis makes the French case uniquely fragile within the advanced-economy cohort.
What Lies Ahead for the Euro Area
The path forward hinges on whether France can credibly demonstrate fiscal control before market pressure becomes self-fulfilling. ING's Carsten Brzeski captured the mood with his blunt assessment that "we are deep into French crisis territory." That phrase carries weight because it comes from a seasoned macro strategist, not a headline-seeking commentator. The diagnosis is professional and grim.
Scenarios for the Coming Months
The benign scenario requires political consensus on consolidation, a stabilisation of spreads, and restored investor confidence. The adverse scenario involves continued gridlock, widening spreads, and mounting pressure on the ECB to intervene. Between these poles lie numerous intermediate paths, each carrying distinct implications for euro-area cohesion and global risk appetite.
Much depends on whether European institutions can credibly signal that they will not allow a core member to drift toward crisis. The 2012 playbook demonstrated that decisive communication can move markets powerfully. Whether that tool remains as potent in a more fragmented political environment is the central question.
Implications for Investors and Policymakers
For investors, the episode reinforces the value of monitoring sovereign spreads and CDS premiums as early-warning indicators. For policymakers, it delivers an unmistakable message: fiscal credibility is not a technical matter but a political one, and markets will price its absence without sentiment. The euro area's resilience will be tested by whether its members can summon the will to act.
The deeper lesson is that monetary union without fiscal convergence remains structurally fragile. France's stress is a symptom of that unfinished architecture, and until the bloc addresses it, episodes of fragmentation will recur. Each recurrence erodes confidence a little further, making the next one harder to contain.
From our network :
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
RESOURCES
- FINANCIAL MARKET FRAGMENTATION IN THE EURO AREAinstitutdelors.euNov 17, 2016 ... ... yields and bank exposures in the euro crisis ... Euro Area Government Bonds—Integration and Fragmentation During the Sovereign Debt…
- 10 years after “whatever it takes”: fragmentation risk in the current ...europarl.europa.euJun 20, 2022 ... The combination of these concerns during the euro crisis led to a crippling scenario of high bond yields and large…
- Measuring sovereign bond fragmentation in the Eurozonesciencedirect.comThe financial fragmentation of the European sovereign bond market resulting from the crisis has brought instability to the Eurozone, undermining the monetary ...
- How Japanese bond yields, Chinese competition are stoking euro ...scmp.comOct 8, 2026 ... When the governor of the Bank of France feels it is necessary to point out that “France is not Greece…
- Euro area government bonds – Fragmentation and contagion during ...sciencedirect.comThe paper analyzes the integration of euro area sovereign bond markets during the European sovereign debt crisis. It tests for contagion (i.e., ...
- France debt crisis: Could turmoil spread across the euro zone?cnbc.com2 days ago ... French bond yields and the spread over German debt have surged to levels not seen since the euro zone debt…
- Parsing financial fragmentation in the euro area: a multi-country ...ecb.europa.euFrance, so that sovereign bond yields and funding cost increase to crisis levels for three years; shock is persistent, i.e. follows an AR(1) process…
- Why France is a warning sign for the markets - Axiosaxios.comOct 7, 2026 ... The epic shifts in global bond markets mostly reflect economic fundamentals, but the distruptions could grow into a broader crisis.
- Measuring Financial Fragmentation in the Euro Area Corporate ...mdpi.com... euro area sovereign crisis in 2011 and 2012. Corporate bonds issued in Italy and Spain bear higher yields than similar bonds issued in…
- Euro Area Financial Fragmentation and Bond Market Stability inelibrary.imf.orgSep 26, 2025 ... The indicator reflects the extent to which yields across different country groupings—often characterized by differing structural and financial ...
- The French leadership paradox - GIS Reportsgisreportsonline.comJan 8, 2026 ... The French-German spread on sovereign bond yields – an indicator of whether France ... Crisis of Leadership Europe European Union…
- Tight by comparison | DWSdws.comJan 23, 2026 ... By 2007, Italy, Spain and France were able to borrow at rates not far off Germany's. Then came the Eurozone…
- WORKING PAPER SERIES Parsing Financial Frictions Underlying ...centralbank.cyFragmentation during the Euro Area Crisis ... Notes: increase of the euro area loss given default so that sovereign bond yields increase approximately by…
- How Macronism has destabilised France and Europe - LSE Blogsblogs.lse.ac.ukFeb 6, 2026 ... At the same time, French government bond yields have risen sharply, at points surpassing those of Italy and Greece. This…
- Eurozone crisis - Wikipediaen.wikipedia.orgThe eurozone crisis, also known as the euro area crisis, European debt crisis, or European sovereign debt crisis, was a debt crisis and financial…
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments