The proposition that SpaceX and Tesla might be consolidated into a single corporate entity has resurfaced through Elon Musk's own public commentary, in which he characterised the combination as "a good idea" and confirmed that committees at both firms are examining a potential transaction.
The implied valuation of approximately $3.5 trillion would, if realised, constitute the largest merger ever recorded, exceeding the scale of any industrial combination hitherto completed. Such a figure is not merely a financial curiosity; it signals the emergence of a corporate structure whose reach would span orbital launch services, defence contracting, electric vehicle manufacturing, energy storage and autonomous transport software.
Analysts have been notably consistent in identifying the principal obstacle to completion, and it is not the conventional antitrust apparatus that ordinarily governs mega-mergers. Rather, the decisive friction is political.
On This Page
- The Strategic Logic and Structural Scale of a SpaceX-Tesla Combination
- National Security, Dual-Jurisdiction Exposure and the Political Impediment
- Regulatory Pathways, Antitrust Doctrine and Cross-Border Review
- Strategic Implications for Defence Procurement and Industrial Policy
- Conclusion: Political Risk as the Binding Constraint
A combined entity would simultaneously function as a major aerospace and defence contractor to the United States government and as a manufacturer whose production base is deeply embedded in China.
This dual exposure creates a structural tension that regulators in Washington and Beijing would each interpret through the lens of national security rather than competition policy alone.
The analytical consensus, as articulated by specialists such as Derek Scissors of the American Enterprise Institute, is that political objections are unlikely to prevent a deal outright but would instead impose a durable burden of scrutiny.
A merger agreement would probably contain pledges limiting the operational integration between the rocket and vehicle businesses, yet the enforcement of such covenants depends entirely on the disposition of the incumbent administration.
A future government could reopen the question with considerably greater severity, meaning that the transaction would carry political risk for years rather than months.
TL;DR Elon Musk has revived the prospect of merging SpaceX with Tesla, a combination that could approach $3.5 trillion in value and rank as the largest merger in corporate history. Analysts contend that political and national security considerations, rather than antitrust doctrine, represent the principal impediment. A combined firm would unite a US defence contractor with a manufacturer heavily dependent on Chinese production, inviting scrutiny from Washington and Beijing alike. Structural safeguards may be negotiated, but enforcement would remain contingent on the political complexion of future administrations.
The Strategic Logic and Structural Scale of a SpaceX-Tesla Combination
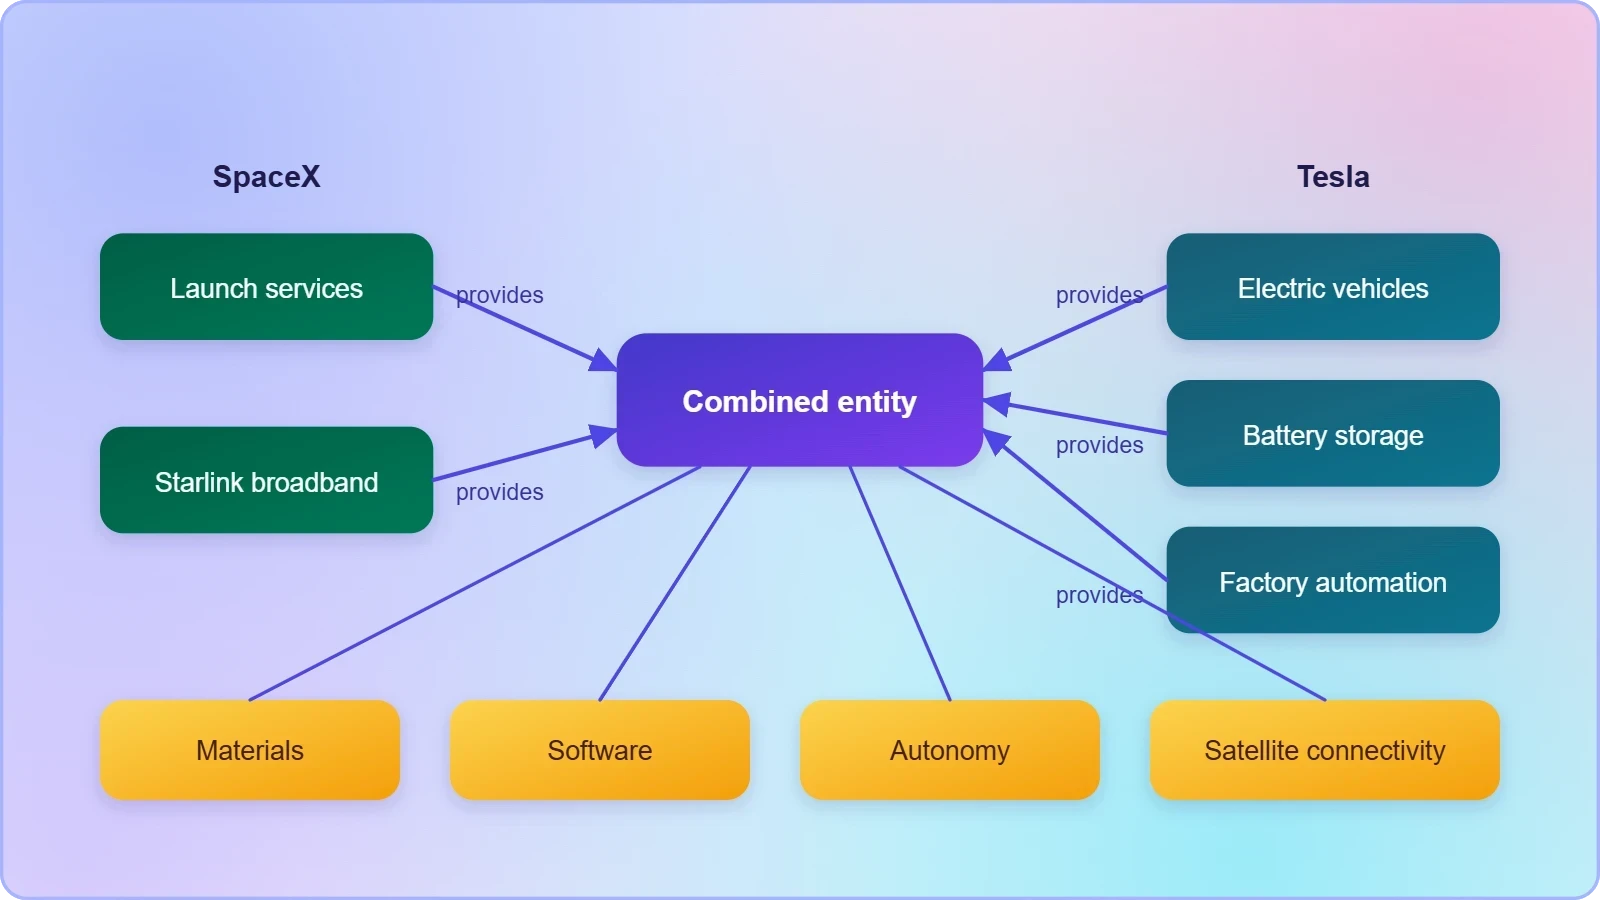
The rationale for consolidation rests on an argument about vertical and horizontal complementarity that is unusual in industrial history. SpaceX possesses launch capability, satellite infrastructure and a growing defence relationship; Tesla possesses manufacturing scale, battery technology, software engineering depth and a consumer distribution network.
A merged entity would control inputs and outputs across several strategic value chains simultaneously, which is precisely why the transaction attracts attention disproportionate to its financial size alone.
Valuation Architecture and the $3.5 Trillion Threshold
Estimating the combined worth requires caution, since neither company's private valuation is audited in the manner of a listed peer. SpaceX has periodically raised capital at valuations reported in the hundreds of billions, while Tesla's market capitalisation fluctuates with equity sentiment.
The $3.5 trillion figure should therefore be treated as an indicative order of magnitude rather than a precise forecast, contingent on prevailing market conditions at the time of any announcement.
What distinguishes this transaction from conventional mega-mergers is the proportion of value attributable to intangible and strategic assets. Launch cadence, spectrum rights, defence clearances and proprietary software contribute far more to the implied valuation than physical plant does.
Consequently, conventional accounting metrics such as enterprise value to EBITDA ratios offer limited analytical traction, and valuation specialists would need to construct bespoke frameworks incorporating sovereign contract backlog and regulatory optionality.
The historical comparison most frequently invoked is the largest completed mergers of the past half-century, yet none of those involved a principal whose personal holdings spanned both sides of the transaction.
Because Musk holds substantial stakes in both enterprises, the negotiation is less an arm's-length bargain between independent boards than a related-party process requiring heightened governance scrutiny. Independent directors and minority shareholders would demand robust procedural protections.
Financing structure remains opaque. A share-for-share exchange would avoid the need for enormous debt issuance, but it would also concentrate ownership in a manner that amplifies governance concerns. Cash components, if any, would require syndicated lending at a scale that few institutions could underwrite alone. Analysts therefore expect any structure to be predominantly equity-based, with attendant dilution implications for existing holders.
Technological Complementarity Across Value Chains
The engineering overlap between the two firms is frequently underestimated in public commentary. Both organisations have cultivated in-house competence in power electronics, thermal management, advanced materials and embedded software, competencies that transfer imperfectly but meaningfully between aerospace and automotive applications. Consolidation would permit the internalisation of supplier relationships and the pooling of scarce engineering talent across programmes.
Starlink, SpaceX's satellite broadband constellation, illustrates the convergence most vividly. Terrestrial electric vehicles and orbital communications infrastructure increasingly intersect through connected-vehicle architectures, and a unified entity could integrate satellite connectivity into consumer products without negotiating commercial terms with an external counterparty.
Such integration raises competitive questions, however, since rival automakers would be reluctant to depend on a supplier owned by a competitor.
Manufacturing philosophy constitutes another point of convergence. Tesla's approach to high-volume production and SpaceX's iterative, rapid-prototyping methodology both derive from a shared organisational culture rather than from sectoral convention.
A merger would formalise what is already an informal exchange of personnel and practice, though formalisation also invites the governance scrutiny that informality currently avoids.
Nevertheless, complementarity does not automatically generate shareholder value. Empirical research on large mergers consistently finds that anticipated synergies are realised less often than projected, and conglomerate structures frequently trade at a discount to focused peers.
The strategic case must therefore be weighed against the documented tendency of diversified industrial combinations to underperform their sum-of-parts valuation over extended horizons.
Governance Concentration and Related-Party Dynamics
Because a single individual holds decisive influence over both enterprises, the transaction would test the adequacy of existing governance frameworks. Independent directors would be obliged to demonstrate that minority holders received fair treatment, and any perception of self-dealing could invite litigation from institutional investors. Delaware corporate law, under which Tesla is incorporated, provides robust mechanisms for such challenges.
The concentration of control also has implications beyond shareholder relations. When one person directs infrastructure upon which governments and militaries depend, commercial decisions acquire a quasi-public character. Senator Cory Booker's observation that business decisions become national security decisions under such conditions captures a genuine structural concern rather than mere political rhetoric, and it applies irrespective of the incumbent's personal inclinations.
Succession risk compounds the governance question. A combined entity of this scale would be extraordinarily dependent on a single founder, and institutional investors have increasingly pressed for documented succession planning at founder-controlled firms.
Any merger agreement would likely need to address contingency arrangements, though public disclosure of such provisions would itself be commercially sensitive.
Compensation and incentive structures would require harmonisation across two very different workforces. SpaceX's engineering culture and Tesla's production-oriented culture reward different behaviours, and merging equity plans, vesting schedules and performance metrics is a technically demanding exercise that frequently generates retention problems during integration. Talent attrition in the immediate post-merger period is a documented risk.
Market Reaction and Investor Interpretation
Public equity markets would interpret any formal announcement through multiple lenses simultaneously. Tesla shareholders might welcome diversification away from automotive cyclicality, while also fearing dilution and the assumption of defence-sector political risk.
Bond investors would focus on leverage and covenant structure, and rating agencies would assess the combined entity's cash flow stability across divergent business cycles.
Private market participants, including venture investors in adjacent space and mobility sectors, would reassess competitive dynamics. A combined entity with internal capital markets could outbid standalone rivals for talent and contracts, potentially accelerating consolidation among smaller competitors.
Antitrust authorities in multiple jurisdictions would examine such effects, though the political objections identified by analysts would likely dominate the regulatory timeline.
Retail investor sentiment, particularly pronounced in Tesla's shareholder base, introduces volatility that institutional analysis cannot fully model. The company's valuation has historically reflected narrative as much as earnings, and a merger announcement would generate competing narratives of strategic genius and overreach. Price discovery in the immediate aftermath would probably be disorderly.
Analyst coverage would fragment along sectoral lines, since few research houses maintain simultaneous expertise in aerospace, defence, automotive and energy. This analytical gap could itself contribute to mispricing, as investors struggle to construct coherent valuation models for an entity without direct precedent. The absence of comparable peers is a genuine impediment to efficient market assessment.
We Also Published
National Security, Dual-Jurisdiction Exposure and the Political Impediment
The central analytical claim in the source material is that political considerations, rather than regulatory procedure, constitute the binding constraint. This distinction matters because antitrust review follows codified processes with defined timelines, whereas political objection operates through informal channels including congressional pressure, committee scrutiny and executive discretion over defence contracting. The latter is considerably harder to predict and to litigate.
The Defence Contractor Dimension in Washington
SpaceX's growing role as a provider of launch services to the United States government, including national security missions, places it within a category of contractors subject to stringent foreign ownership and control reviews.
A merger with a company possessing extensive foreign manufacturing operations would trigger examination under provisions governing defence industrial security, irrespective of the parties' intentions.
Congressional committees possess considerable leverage over such transactions through their oversight of appropriations and procurement. Senator Booker's public statement, made in his capacity as a member of both the Judiciary and Foreign Relations committees, signals that scrutiny would be bipartisan and procedurally multifaceted. Committee hearings alone can impose substantial delay and reputational cost.
The Department of Defense would confront a practical dilemma. SpaceX is currently a critical supplier with limited near-term alternatives for certain launch capabilities, which gives the company leverage in any negotiation over conditions.
Yet the department cannot readily accept arrangements that create perceived foreign influence over sensitive programmes, particularly where supply chains intersect with adversarial jurisdictions.
Mitigation measures would probably include proxy agreements, special security arrangements and firewalls between sensitive programmes and the broader corporate group. Such structures exist in defence contracting and are not unprecedented, but they impose ongoing compliance costs and administrative friction. Their adequacy would be contested by critics and revisited by successive administrations.
Chinese Manufacturing Dependence as Strategic Leverage
Tesla's substantial production capacity within China constitutes the most consequential vulnerability in the transaction's political calculus. Analysts have observed that this dependence could furnish Beijing with leverage in any future dispute with Washington, since the physical assets and employment relationships are situated within Chinese jurisdiction and subject to local law.
The reciprocal dimension is equally significant. Chinese authorities would scrutinise a merger that placed their domestic manufacturing base within a group holding sensitive American defence contracts. Data governance provisions, export control regimes and technology transfer rules would all intersect, creating compliance obligations that could prove mutually incompatible in practice.
This interdependence creates what might be termed a mutual hostage structure. Neither government can act decisively against the combined entity without imposing costs on its own strategic interests, yet neither can credibly commit to restraint.
The resulting equilibrium is unstable and would generate persistent political risk premia in the entity's cost of capital.
Historical precedent offers limited guidance. Previous instances of defence contractors with foreign manufacturing exposure have generally involved smaller operations or jurisdictions with treaty arrangements. The scale of Tesla's Chinese footprint, and the strategic prominence of both parent companies, place this case outside established categories and invite bespoke policy responses.
Congressional Scrutiny and Bipartisan Skepticism
Legislative attention to the transaction has already materialised, with Senator Booker's remarks representing an early articulation of concerns that are likely to broaden. Antitrust enforcers worldwide would examine the deal, he noted, and the concentration of infrastructure relied upon by governments and militaries transforms commercial decisions into security decisions.
Bipartisan skepticism appears probable, though for divergent reasons. Some legislators would emphasise competition and consumer welfare, others foreign influence and defence readiness, and still others the personal concentration of power.
This coalition of concerns, while lacking a single coherent doctrine, is politically durable because each faction can pursue its objection through separate institutional channels.
Committee hearings would generate a public record that subsequent administrations could draw upon. Even if the incumbent executive declined to impose conditions, the documentary trail would constrain future discretion and provide a basis for later review.
This institutional memory effect is precisely what analysts mean when they suggest the deal would face years of political pressure.
State-level actors also possess relevant authority, particularly regarding manufacturing incentives and data protection. A transaction of this magnitude would mobilise governors, attorneys general and local regulators, each with distinct statutory tools. The multiplicity of veto points increases the probability that some condition, somewhere, proves unacceptable to the parties.
Enforcement Asymmetry Across Administrations
The AEI analysis identifies a critical temporal dimension: commitments extracted at the point of approval may not be enforced by subsequent administrations. A merger agreement would likely include pledges limiting connections between SpaceX and Tesla, yet the durability of such pledges depends on political will rather than legal architecture alone.
This asymmetry creates a form of regulatory moral hazard. Parties can offer concessions knowing that enforcement is discretionary, while critics can oppose the deal knowing that future governments may reopen the question. Neither side can make credible long-term commitments, and the resulting uncertainty is itself a cost borne by the merged entity.
Contractual firewalls, security agreements and proxy arrangements are all mechanisms that have been used in comparable situations, but their effectiveness varies with the vigilance of overseers. Where oversight is politically contested, the practical strength of a firewall may be considerably weaker than its documentary appearance suggests.
Investors would therefore need to price political risk explicitly, assigning probabilities to scenarios in which a future administration imposes divestiture, operational restrictions or contract exclusions. Such scenario analysis is inherently subjective, and the absence of historical analogues makes calibration difficult. This uncertainty would likely depress the combined entity's valuation relative to a politically neutral peer.
Regulatory Pathways, Antitrust Doctrine and Cross-Border Review
Although political considerations dominate the analytical narrative, the formal regulatory pathway remains substantive and would proceed in parallel. Multiple jurisdictions would assert authority, and the transaction would require notification in the United States, the European Union, China and numerous other markets where either company operates. Coordination among these regimes is limited, and divergent outcomes are conceivable.
Antitrust Theory Applied to Cross-Sector Consolidation
Conventional antitrust analysis focuses on market definition and competitive effects within defined markets. A SpaceX-Tesla combination presents unusual difficulties because the parties are not direct competitors in most relevant markets, which ordinarily reduces concern.
The theory of harm would instead rest on conglomerate effects, foreclosure and the leveraging of dominance across adjacent markets.
Foreclosure concerns arise where a merged entity could deny rivals access to essential inputs. If Tesla vehicles integrate Starlink connectivity as a proprietary feature, competing automakers might face degraded options, and satellite competitors might find distribution channels narrowed. Such theories are analytically demanding but have gained traction in recent enforcement practice.
The conglomerate effects doctrine, long dormant in several jurisdictions, could be revived. Regulators might argue that combining complementary assets creates entrenchment that neither firm could achieve independently, raising barriers to entry across multiple sectors simultaneously. This argument is theoretically coherent but empirically contested, and its acceptance would represent a significant doctrinal shift.
Remedies would be correspondingly complex. Structural remedies such as divestiture are difficult to apply to businesses whose value derives from integration, while behavioural remedies require ongoing monitoring that agencies are often reluctant to undertake. The mismatch between the transaction's architecture and available remedial tools complicates resolution considerably.
Foreign Investment Screening Regimes
Beyond competition law, foreign investment screening mechanisms would engage. Although both parties are nominally American, Tesla's Chinese operations and supply relationships would invite examination under provisions designed to detect foreign control or influence over critical infrastructure. The analysis focuses on substance rather than formal nationality.
Several jurisdictions have expanded their screening regimes in recent years, lowering thresholds and broadening the sectors covered. Critical infrastructure, dual-use technology and data-intensive businesses are routinely captured. A combined entity would satisfy multiple criteria simultaneously, virtually guaranteeing comprehensive review across the jurisdictions where it operates.
Mitigation agreements are the standard instrument for resolving screening concerns, typically involving governance undertakings, information barriers and commitments regarding sensitive assets. Their negotiation is confidential and their terms rarely disclosed, which complicates external assessment of whether substantive protections have been secured or merely symbolic ones.
The interaction between screening regimes and antitrust review creates procedural complexity. Conditions imposed by one authority may conflict with those imposed by another, and the parties must construct a package acceptable to all. Where geopolitical tension exists between reviewing states, the scope for mutually compatible conditions narrows considerably.
- 01
- 02
- 03
- 04
Securities Disclosure and Shareholder Approval Mechanics
If Tesla remains publicly listed, the transaction would require extensive disclosure under securities regulations, including proxy statements detailing the fairness analysis, conflicts of interest and projected synergies. Shareholder approval would be required, and the related-party nature of the transaction would intensify scrutiny of the disclosure's adequacy.
Litigation risk is substantial. Merger challenges are a well-established feature of American corporate practice, and plaintiffs would likely allege inadequate disclosure or unfair process. Even meritless suits impose costs and delay, and the presence of a controlling shareholder with interests on both sides of the transaction amplifies the probability of challenge.
Appraisal rights would permit dissenting shareholders to seek judicial determination of fair value, creating contingent liabilities that complicate financing. The magnitude of such exposure depends on the proportion of holders who dissent, which in turn depends on the premium offered relative to prevailing market prices at announcement.
Accounting treatment would also require resolution. Depending on structure, the transaction might be accounted for as a reverse acquisition, a common-control combination or a standard business combination, each with distinct implications for reported earnings and balance sheet presentation. The choice would materially affect the entity's apparent financial profile.
Strategic Implications for Defence Procurement and Industrial Policy
The transaction cannot be assessed in isolation from the broader reconfiguration of Western defence industrial policy. Governments have increasingly sought to reduce dependence on single suppliers while simultaneously consolidating procurement around a small number of capable primes. A SpaceX-Tesla combination would intensify this tension rather than resolve it.
Supplier Concentration and Mission Assurance
SpaceX's position in launch services has already generated concern about over-reliance on a single provider. Mission assurance requires redundancy, yet the economics of launch favour scale, producing a structural tension between resilience and efficiency. Consolidation with Tesla would extend this concentration into adjacent domains, including communications and ground infrastructure.
Defence planners must weigh the operational benefits of integration against the strategic risk of dependence. A supplier that is difficult to replace possesses bargaining power that may not align with public interest, particularly where the supplier's principal is politically active. Contractual mechanisms can partially address this, but they cannot fully substitute for genuine alternatives.
The industrial base implications extend to smaller suppliers. A combined entity with internal capital markets could vertically integrate components currently sourced externally, displacing established vendors and reducing the diversity of the supplier ecosystem. Such effects are gradual but cumulative, and they are difficult to reverse once capacity is lost.
Allied governments would observe these developments with attention. Several have sought to develop indigenous launch and satellite capabilities precisely to avoid dependence on American providers, and consolidation might accelerate such efforts. The strategic consequence could therefore be fragmentation rather than the integration the parties intend.
Allied Perspectives and Export Control Considerations
Export control regimes, including the International Traffic in Arms Regulations, would govern the transfer of technical data within the combined entity. Tesla's foreign operations would create numerous points of potential exposure, and compliance would require rigorous internal controls that impose costs on routine business activities.
Allied governments would seek assurances that their own defence relationships with SpaceX would not be compromised by the merger. Such assurances are politically necessary but legally fragile, since they depend on the continued willingness of the American executive to honour them. Historical experience suggests that such commitments are honoured inconsistently.
The technology transfer dimension is particularly sensitive. Satellite communications technology, autonomous systems and advanced manufacturing processes all have dual-use potential, and their presence within a group with extensive Chinese operations would attract scrutiny from export control authorities in multiple capitals. Compliance architectures would need to be exceptionally robust.
International coordination among export control authorities is imperfect, and divergent interpretations of multilateral arrangements are common. A combined entity would therefore face a patchwork of national requirements rather than a coherent regime, increasing compliance complexity and the risk of inadvertent violation.
Capital Allocation and Long-Horizon Investment
A merged entity would possess internal capital markets capable of funding programmes that external investors might decline to finance. This capacity is genuinely valuable for long-horizon projects such as interplanetary transport or orbital infrastructure, where payback periods exceed typical investment horizons and uncertainty is substantial.
Yet internal capital markets also create agency problems. Management may cross-subsidise failing projects, and the absence of external discipline can entrench inefficiency. Empirical literature on conglomerates documents persistent value discounts attributable in part to such dynamics, and the risk would be acute in an entity dominated by a single decision-maker.
Capital intensity would remain formidable. Both businesses require continuous heavy investment, and the combined entity's financing needs would be substantial. Access to capital markets would depend on the perceived political risk, creating a feedback loop in which political uncertainty raises the cost of capital and thereby constrains the very investments that justify the merger.
Dividend policy and capital return would require reconciliation between shareholders with different expectations. Tesla's investor base has historically tolerated minimal distributions in pursuit of growth, while SpaceX's private investors may have different liquidity preferences. Harmonising these expectations is a governance challenge that would persist well beyond completion.
Innovation Incentives Under Concentrated Ownership
Scholarly debate on whether concentration aids or impedes innovation remains unresolved. Proponents argue that integrated entities can pursue ambitious programmes requiring coordinated investment across disciplines, while critics contend that market power reduces the pressure to improve and narrows the diversity of experimental approaches.
The empirical record is mixed and highly context-dependent. Some of the most consequential innovations of the past century emerged from large integrated organisations, while others originated in small firms operating at the periphery. Generalisation is therefore hazardous, and the specific characteristics of the aerospace and automotive sectors must inform any assessment.
One relevant consideration is the availability of alternative pathways for talented engineers and entrepreneurs. If consolidation narrows the number of independent organisations capable of pursuing frontier projects, the diversity of approaches diminishes, and the probability of discovering unexpected solutions declines. This is a systemic concern rather than a narrow competitive one.
Conversely, integration may accelerate the diffusion of techniques between sectors. Manufacturing methods developed for rocketry can inform automotive production, and battery expertise can inform satellite power systems. Such cross-pollination is a genuine benefit, though it might also be achieved through licensing and partnership without full consolidation.
Conclusion: Political Risk as the Binding Constraint
The analytical weight of the evidence supports the conclusion that political considerations, rather than regulatory doctrine, will determine the transaction's fate. Antitrust review is procedurally demanding but ultimately resolvable through negotiation and remedy; political opposition is diffuse, durable and resistant to settlement. The distinction is fundamental to understanding why this merger differs from conventional mega-deals.
Synthesis of Analytical Findings
Three findings emerge with reasonable confidence. First, the strategic logic of combination is coherent but not overwhelming, and the anticipated synergies would require sustained managerial attention to realise. Second, the dual-jurisdiction exposure creates structural vulnerabilities that no contractual arrangement can fully eliminate.
Third, the concentration of control in a single individual amplifies both the transaction's appeal and its political fragility.
These findings do not imply that the transaction will fail. Analysts quoted in the source material expect it to proceed, subject to conditions and sustained scrutiny. The more probable outcome is completion accompanied by governance undertakings, security arrangements and operational firewalls, followed by years of intermittent political contestation over their adequacy.
The valuation implications are correspondingly nuanced. A completed merger would create an entity of extraordinary strategic significance, but its cost of capital would embed a political risk premium that a comparable but politically neutral firm would not bear.
Whether the strategic benefits exceed this premium is a question that cannot be resolved ex ante with confidence.
Implications for Investors and Policymakers
For investors, the transaction underscores the importance of incorporating political analysis into conventional financial modelling. Regulatory calendars and antitrust theories are necessary inputs, but they are insufficient without an assessment of legislative sentiment, electoral cycles and the durability of executive commitments across administrations.
For policymakers, the case illustrates the difficulty of governing corporate entities whose scale and strategic reach exceed the capacity of any single regulatory regime. Existing instruments, designed for a world of nationally bounded firms, are poorly suited to entities whose operations span jurisdictions and whose decisions carry security implications.
The broader lesson concerns the interaction between private ambition and public authority. Where a single individual controls infrastructure upon which states depend, the boundary between commercial and governmental decision-making becomes indistinct. Managing that boundary requires institutional creativity, and the SpaceX-Tesla proposal may prove instructive regardless of its eventual outcome.
Finally, the episode demonstrates that merger analysis in strategically significant sectors can no longer be confined to competition economics. National security, foreign policy, industrial strategy and data governance all bear upon the assessment, and analytical frameworks must expand accordingly.
The discipline of merger review is, in this respect, being reshaped by the very transactions it seeks to evaluate.
From our network :
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
RESOURCES
- Musk's political baggage clouds prospects for SpaceX-Tesla dealreuters.com5 days ago ... “If Elon Musk moves forward with the merger of Tesla and SpaceX, the deal would carry real risks that antitrust…
- Elon Musk & Gwynne Shotwell on AI Risks and Peer Review, Starshipyoutube.comSep 14, 2026 ... Elon Musk & Gwynne Shotwell on AI Risks and Peer Review, Starship, Terafab, SpaceX/Tesla Merger. @allin 15K likes 1.4M views…
- Why is Elon Musk plotting a mega-merger of SpaceX and Tesla?bbc.com6 days ago ... Musk says there's "a lot to be gained" by combining the firms in what would be the biggest merger in…
- UB expert available to discuss implications of possible SpaceX ...buffalo.edu5 days ago ... “Despite the excitement surrounding a potential SpaceX–Tesla merger, the deal's benefits appear limited, while significant risks and obstacles ...
- All-In Summit: Elon Musk & Gwynne Shotwell -- AI Risks and Peer ...x.comSep 15, 2026 ... ... SpaceX/Tesla Merger Potential -- Management at SpaceX ++ much more! (0:00) SpaceX's @Gwynne_Shotwell joins The Besties! (1:45) Gwynne's SpaceX ...
- How does SpaceX make decisions? : r/SpaceXLounge - Redditreddit.comJan 26, 2022 ... In the Dan Rasky interview years back, he mentioned how at NASA when they had a risk ... SpaceX-Tesla merger…
- Rockets, robots and risk: Elon Musk's $3.6tn gamble to merge Tesla ...ft.com6 days ago ... The world's richest man is preparing for the “AI singularity” by trying to fold SpaceX and Tesla together into a…
- Tesla beats earnings projections after Musk floats SpaceX merger plantheguardian.com6 days ago ... ... politics · World · Climate crisis · Middle East · Ukraine · Football ... analysis, direct from the Guardian…
- SpaceX-Tesla merger could face antitrust scrutiny - Semaforsemafor.com4 days ago ... One former Justice Department official told Semafor that the risks for the merger are real ... analyze website traffic. For…
- Musk races to seal $3.7 trillion SpaceX-Tesla merger before Trump ...investinglive.com6 days ago ... Summary. There is a push to announce a SpaceX-Tesla merger by mid-2027 so it closes under Trump, Bloomberg reports. The…
- Musk Says SpaceX and Tesla Have Begun Exploring a Mergerbloomberg.com6 days ago ... Markets Daily UK for what's driving UK markets before the trading day starts; Balance of Power for the latest political…
- The Merger That Changes Everything: Why My SpaceX Thesis Just ...macronotes.substack.comFeb 20, 2026 ... ... analysis, including the complete stock selection, allocation strategy, and risk framework. ... If the Tesla-SpaceX merger thesis materializes, ...
- Musk Tries to Lock In His Tesla-SpaceX Dream Before Trump's Exitbloomberg.com6 days ago ... Time is running out to pull off the $3.7 trillion merger before political and financial environments take a turn.
- SpaceX-Tesla Merger Antitrust Risk at $3.5T [2026] - Tech Insidertech-insider.org4 days ago ... Booker's Warning and the Political Backdrop. Politics shadows the legal analysis. Sen. Cory Booker told Reuters, as quoted by Semafor:…
- After Earnings, Is Tesla Stock a Buy, a Sell, or Fairly Valued?morningstar.comFeb 5, 2026 ... ... SpaceX merger, here's what we think of Tesla stock ... Tesla also faces political risk related to the political…
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments