When American voters handed control of both chambers of Congress to the Democratic Party in the 2026 midterm elections, the reaction on trading floors from New York to Frankfurt was almost instantaneous. Equity benchmarks climbed, crude oil contracts collapsed by more than eight percent, and currency desks repriced the dollar against the euro, the pound and the yen within hours. What markets were really celebrating was not a partisan outcome but the disappearance of a question that had haunted portfolios for months: whether the result would be contested, litigated, or met with institutional resistance. The orderly concession, or at least the absence of disruption, mattered more to capital than the identity of the winners.
The session deserves close reading because it compresses several distinct forces into a single trading day. There is the pure relief trade, in which uncertainty premiums unwind and risk assets rally. There is the sector rotation story, visible in the divergence between defence contractor Lockheed Martin, which fell nearly seven percent, and solar manufacturer First Solar, which gained almost five. There is the commodity shock, driven by expectations that a Democratic Congress could choke off funding for an unpopular war and thereby reduce geopolitical risk to energy supply. And there is the macro backdrop of eurozone inflation touching a three-year high, which complicates any simple narrative of a uniformly risk-on world.
This analysis unpacks each of those threads, separating the durable signal from the noise of a single volatile session. It examines why the Dow's fifteen-hundred-point advance coexisted with a sharp decline in Nvidia and both of Elon Musk's listed companies, why Tokyo's Nikkei moved in the opposite direction to Wall Street, and what the oil collapse reveals about how markets price political risk. Investors who understand the mechanics behind these moves will be better equipped to interpret the next election-driven shock, whenever it arrives.
On This Page
- The Relief Rally: Why Removing Uncertainty Outweighed Policy Fears
- Oil's Sharp Retreat and the Politics of War Funding
- Sector Dispersion: Winners and Losers Beneath the Headline
- Global Spillovers: Europe, Asia and the Currency Channel
- Governorships, Data Centres and the Local Politics of Infrastructure
- What the Session Reveals About Election-Driven Market Behaviour
TL;DR Democratic victories in both houses of Congress triggered a relief rally in US equities, with the Dow Jones Industrial Average surging three percent to 53,356.12 while the S&P 500 and Nasdaq posted smaller gains. Oil prices fell more than eight percent as traders bet that a Democratic-controlled Congress would restrict war funding and push President Trump toward ending the conflict with Iran. Sector dispersion was pronounced: defence stocks and Musk-linked companies fell, while solar and mega-cap technology names rose. European markets gained roughly two percent, Tokyo's Nikkei slipped on technology weakness, and eurozone inflation hit a three-year high of four percent, lifting the euro against the dollar.
The Relief Rally: Why Removing Uncertainty Outweighed Policy Fears
Financial markets are frequently described as pricing information, but what they price most acutely is the absence of resolution. Before the vote, a meaningful cohort of investors had convinced themselves that a decisive Democratic sweep could damage equities, particularly through risks to the enormous capital expenditure programmes underpinning artificial intelligence data centres. Yet when the result arrived and President Trump declined to contest it, the dominant emotion on trading desks was relief rather than fear. The Dow's three percent advance, equivalent to more than fifteen hundred points, was less a verdict on Democratic policies than a release of accumulated tension.
The Anatomy of an Uncertainty Premium Unwinding
Every contested political event carries an embedded insurance cost. Options markets widen, volatility indices firm, and portfolio managers hold larger cash buffers than they otherwise would. When the event resolves cleanly, that insurance is no longer needed and the cost of carrying it is returned to the market in the form of fresh buying. The 2026 midterms followed this template almost perfectly, with the Dow closing at 53,356.12, the S&P 500 adding 1.6 percent and the Nasdaq Composite rising 1.4 percent. The pattern is familiar from previous election cycles, though the magnitude here was amplified by the war-related anxiety layered on top.
What distinguishes a relief rally from a genuine re-rating is durability. Relief rallies tend to fade within weeks as attention returns to earnings, interest rates and valuation. A re-rating, by contrast, persists because the underlying earnings power of companies has changed. The early evidence from this session suggests the former: the gains were broad but not uniform, and several prominent names moved sharply lower despite the index-level euphoria. Investors would be wise to treat the initial surge as a liquidity event rather than a fundamental reassessment until subsequent sessions confirm whether the buying has legs.
Reading the Index Divergence
The three major US benchmarks told subtly different stories. The Dow, weighted by price and dominated by industrial and financial stalwarts, posted the largest percentage gain at three percent. The S&P 500, the broadest gauge of large-cap America, rose a more modest 1.6 percent, while the technology-heavy Nasdaq Composite lagged at 1.4 percent. That ordering is revealing: the rally was strongest in the old-economy, domestically oriented names least exposed to the regulatory and budgetary questions a Democratic Congress might raise, and weakest in the growth sectors where policy risk is most concentrated.
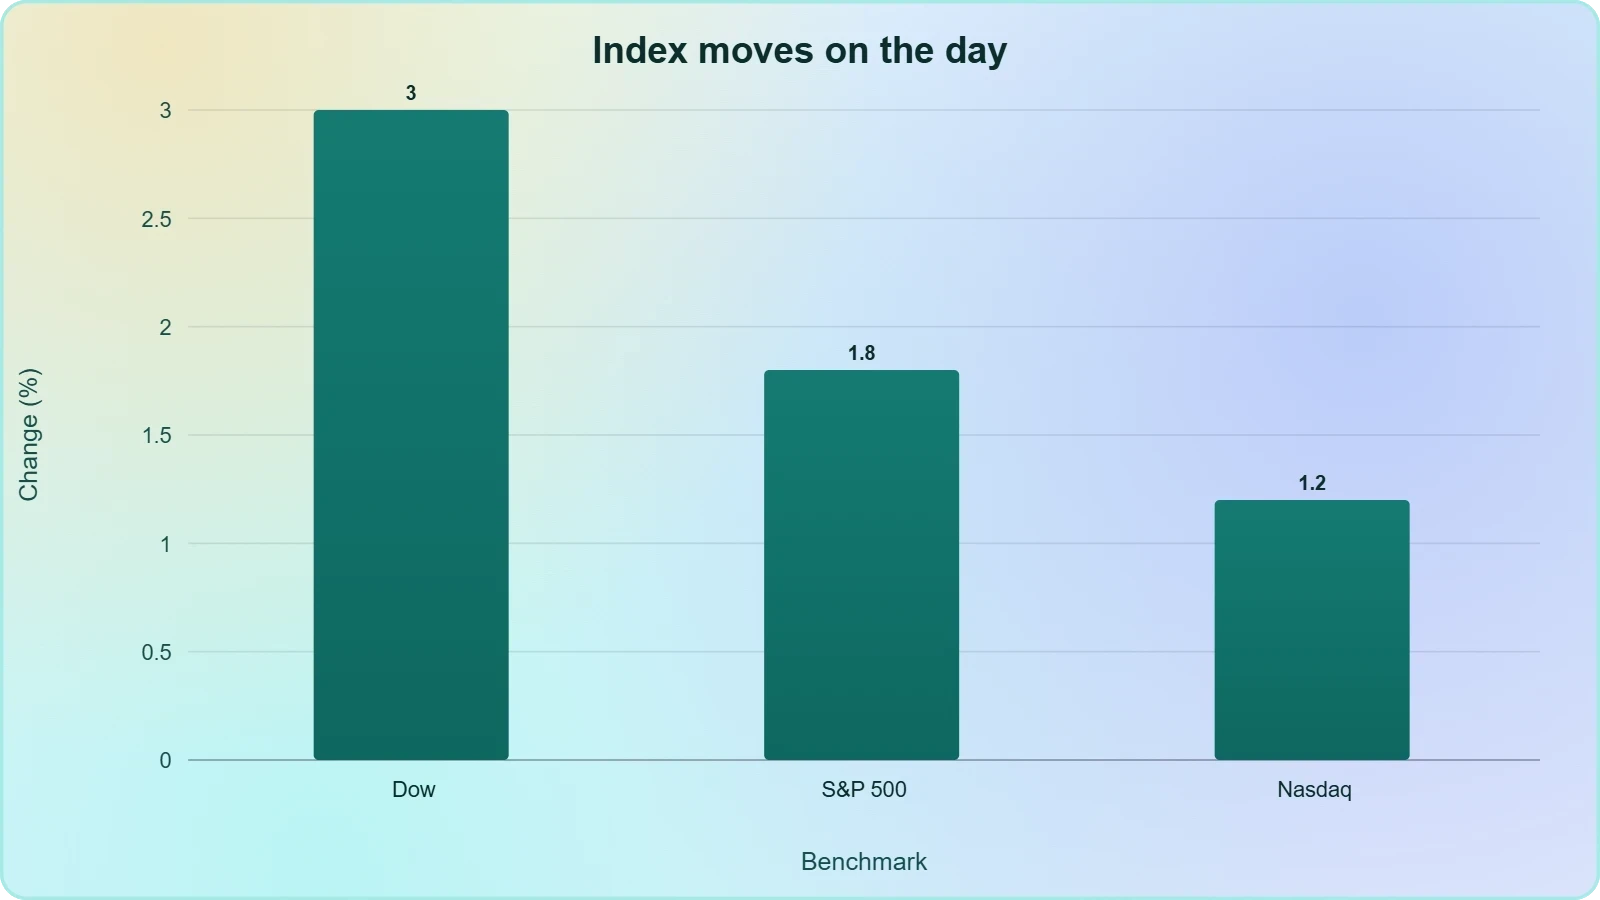
This divergence matters for portfolio construction. A rally led by cyclicals and value names suggests investors are positioning for a period of legislative gridlock punctuated by targeted investigations, rather than for sweeping new spending or regulation. Gridlock, paradoxically, is often kind to equities because it forecloses disruptive change. The muted Nasdaq performance also reflects the specific anxiety about data centre buildouts, a concern that did not evaporate simply because the votes were counted. Technology investors face a more complicated calculus than the headline index numbers imply.
Oil's Sharp Retreat and the Politics of War Funding
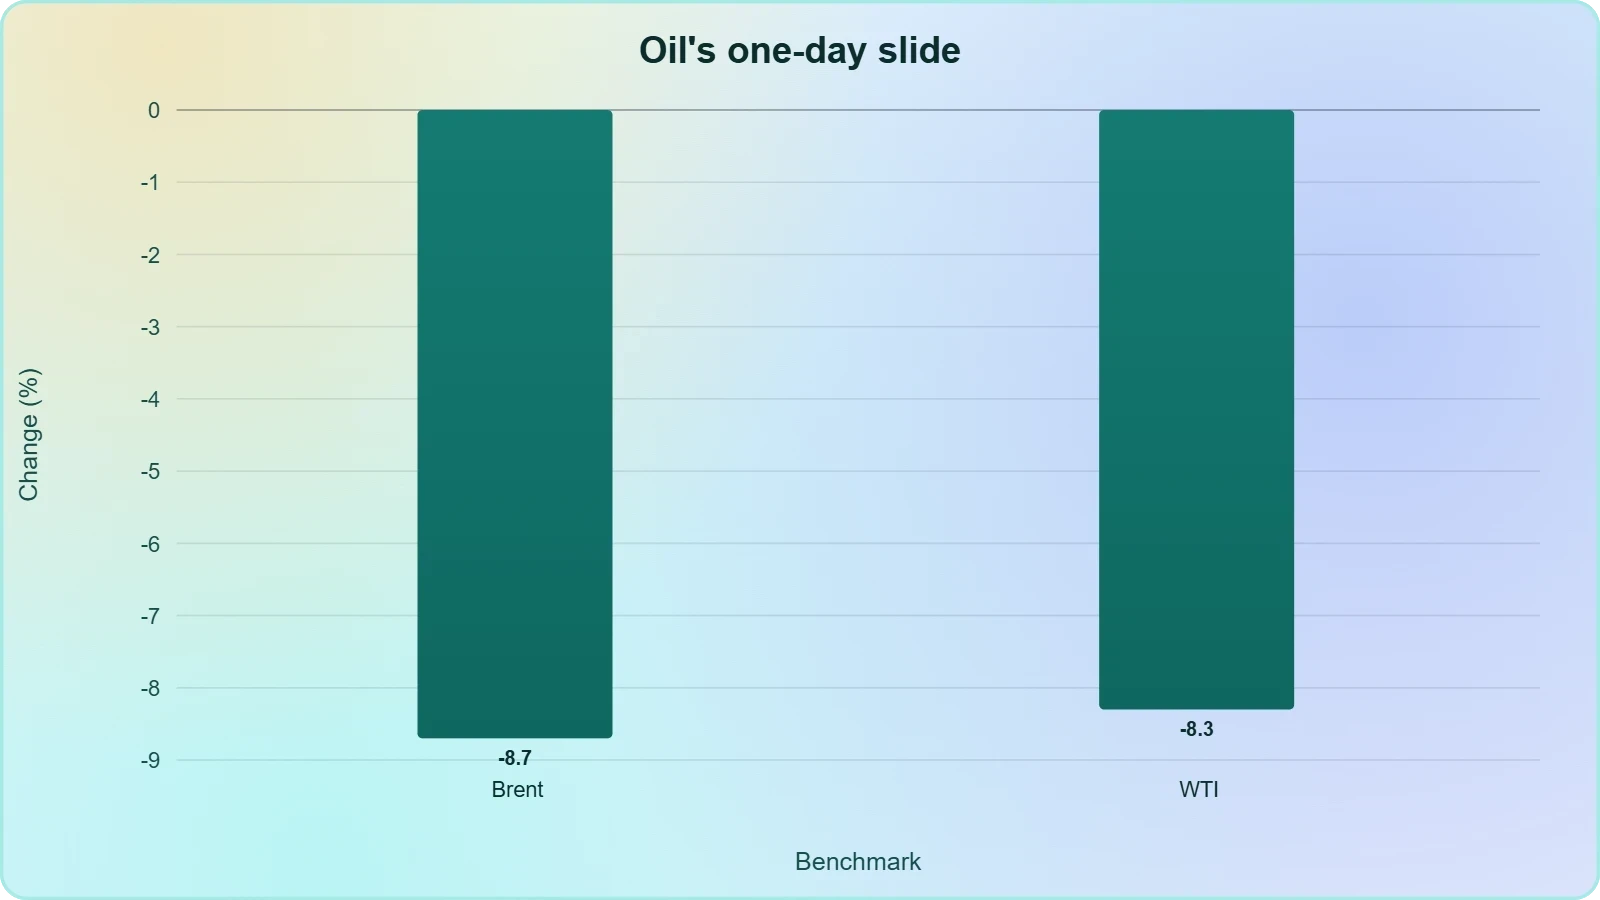
Crude oil's collapse was the most dramatic single move of the session and the one most directly traceable to political causation. Brent North Sea crude fell 8.7 percent to $94.62 a barrel, while West Texas Intermediate dropped 8.3 percent to $88.12, both settling below the psychologically significant hundred-dollar threshold. The trigger was not a supply surprise, a demand shock or an inventory report. It was the market's judgement that a Democratic-controlled Congress would use its power of the purse to restrict funding for the US war with Iran, thereby increasing pressure on President Trump to wind the conflict down.
How Legislative Leverage Becomes a Commodity Price
Oil markets embed a geopolitical risk premium whenever supply routes or producing regions are threatened by conflict. That premium is notoriously difficult to quantify, but it can be inferred from the speed with which prices fall when the threat recedes. An eight percent single-day decline implies that traders had been carrying a substantial war-risk cushion, and that the election result convinced them it could be safely removed. The mechanism is straightforward: congressional control over Pentagon appropriations gives the legislature genuine leverage over the conduct and duration of military operations, and markets recognised that leverage immediately.
Vice-President JD Vance's public acknowledgement that the Republican defeat stemmed from popular opposition to the war, which had driven up fuel and other prices, reinforced the market's interpretation. When a senior administration figure concedes that the conflict is politically costly, traders reasonably conclude that its days are numbered. The oil price thus became a barometer not of geology or OPEC quotas but of democratic accountability. This is an underappreciated channel through which elections transmit into commodity markets, and it deserves more attention than the usual focus on fiscal and regulatory policy.
Implications for Energy Equities and Inflation
Falling crude prices cut both ways for investors. They relieve pressure on household budgets and transport costs, offering a disinflationary impulse that central banks would welcome, particularly with eurozone inflation already running at a three-year high of four percent. But they also compress revenues for energy producers and their service suppliers, which can drag on equity indices weighted toward the sector. The net effect on a diversified portfolio depends on the relative weight of consumers versus producers, and on whether the decline proves durable or merely a one-day overreaction to a political headline.
For the broader inflation picture, the timing is delicate. A sustained retreat in energy costs would provide welcome relief to consumers and could soften the trajectory of headline inflation on both sides of the Atlantic. Yet the eurozone's four percent reading, reported the same week, reminds us that underlying price pressures remain stubborn. Policymakers will be watching whether the oil move persists before adjusting their forecasts, and investors should resist extrapolating a single session's commodity plunge into a durable disinflation narrative.
We Also Published
Sector Dispersion: Winners and Losers Beneath the Headline
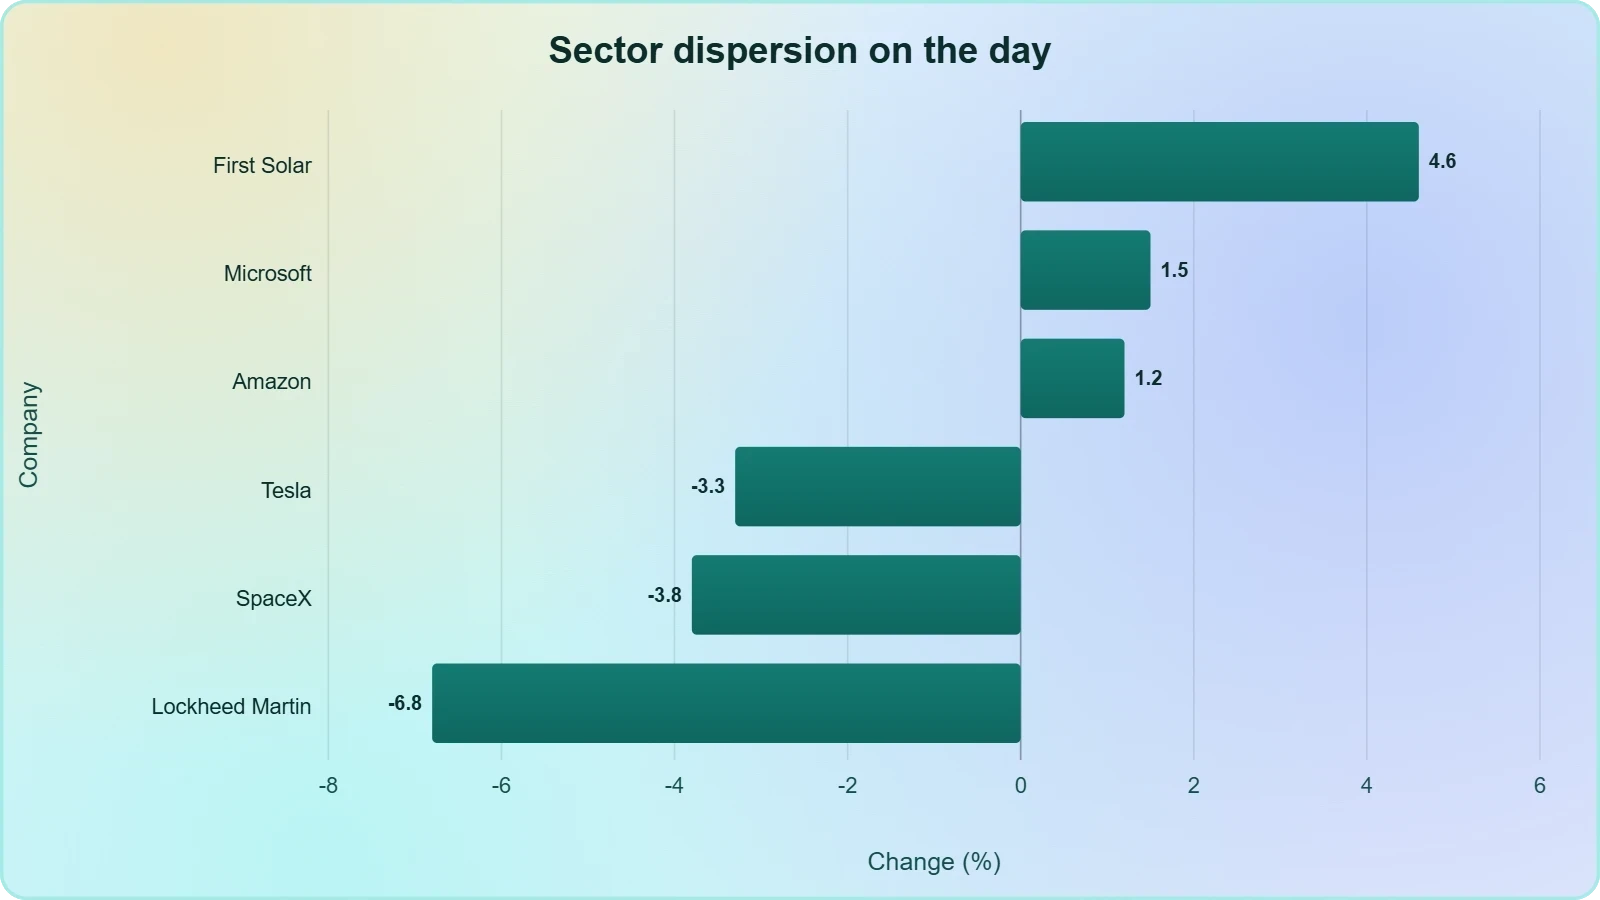
Index-level gains conceal as much as they reveal, and the post-election session offered a masterclass in dispersion. Microsoft and Amazon advanced, reflecting confidence that mega-cap software and cloud franchises would weather any legislative scrutiny. Nvidia, the emblem of the artificial intelligence buildout, declined, a signal that investors remain wary of the data centre policy risk that had worried them before the vote. Defence giant Lockheed Martin fell 6.9 percent on expectations of constrained Pentagon budgets, while solar company First Solar rose 4.6 percent, benefiting from the prospect of a Congress more sympathetic to renewable energy incentives.
The Musk Complex and Policy-Sensitive Names
Both of Elon Musk's publicly traded companies moved lower, with SpaceX falling 3.8 percent and Tesla dropping 3.3 percent. The pattern is consistent with a market that associates these enterprises with the outgoing administration's priorities and anticipates a less accommodating legislative environment. Companies whose valuations rest partly on political alignment, regulatory forbearance or government contracts are inherently exposed to electoral shifts, and the Musk complex sits squarely in that category. Investors holding such names should recognise that they are carrying a political beta alongside their operational beta, and that the two can move independently.
The defence sector's weakness tells a parallel story. Lockheed Martin's near-seven-percent decline reflects the market's expectation that a Democratic Congress will scrutinise and potentially trim military appropriations, particularly those tied to the Iran conflict. Yet defence spending is notoriously sticky, sustained by bipartisan consensus on national security and by the distributed geography of defence manufacturing, which gives contractors political allies in every state. A single session's selloff may therefore overstate the durability of the threat, and long-term investors should distinguish between headline-driven volatility and genuine changes to the procurement pipeline.
Solar, Renewables and the Green Policy Trade
First Solar's 4.6 percent gain illustrates the mirror image of the defence trade. A Congress controlled by Democrats is widely expected to protect and extend incentives for renewable energy, making solar manufacturers natural beneficiaries of the result. The move also reflects a rotation within the energy complex, as capital exits fossil fuel producers facing lower crude prices and redeplores toward alternatives with policy tailwinds. Whether this rotation persists depends on the legislative agenda actually delivered, which is far from certain given the competing priorities and narrow margins that typically characterise congressional majorities.
For investors, the lesson is that election outcomes create relative-value opportunities even when the absolute direction of the market is unclear. The spread between First Solar and Lockheed Martin on a single day was more than eleven percentage points, a dispersion that dwarfs the index-level moves. Capturing such spreads requires a view not merely on who won, but on which specific policies will actually be enacted and how quickly. That is a far more demanding analytical task than simply buying the index on relief, and it rewards investors with genuine sector expertise.
- 01
- 02
- 03
- 04
Global Spillovers: Europe, Asia and the Currency Channel
The American session did not unfold in isolation. European markets closed roughly two percent higher, echoing the relief that swept Wall Street, while most Asian bourses also advanced. Tokyo's Nikkei 225 was the conspicuous exception, falling 1.4 percent as technology shares struggled, a reminder that the global transmission of a US political event is neither uniform nor instantaneous. Currency markets added another layer, with the euro rising to $1.1229 from $1.1193, the pound climbing to $1.3473 from $1.3415, and the dollar slipping to ¥158.49 from ¥158.69.
Why Tokyo Diverged From the Global Rally
Japan's equity market is unusually sensitive to the semiconductor and technology supply chain, and the same data centre anxieties that weighed on Nvidia in New York resonated more forcefully in Tokyo. Japanese technology names are deeply embedded in the global AI hardware ecosystem, supplying components, materials and manufacturing equipment to the very buildout that Democratic oversight might slow. When the policy risk to that buildout rises, Tokyo feels it more acutely than Frankfurt or London, whose indices are weighted toward financials, industrials and consumer staples.
The divergence also reflects domestic factors. The yen's modest strengthening against the dollar, from ¥158.69 to ¥158.49, creates a translation headwind for Japan's exporters, whose earnings are flattered by a weaker currency. A stronger yen compresses the overseas profits of Toyota, Sony and their peers when repatriated, and equity markets anticipate that arithmetic. The Nikkei's decline is therefore a compound of global technology anxiety and local currency dynamics, a useful illustration of how a single political event propagates through multiple channels simultaneously.
Currency Markets as a Political Barometer
The dollar's softness against the euro and sterling, though modest in percentage terms, signals that currency traders read the Democratic victory as a check on fiscal expansion and geopolitical adventurism. A Congress capable of blocking legislation and investigating the executive branch is, in market terms, a Congress capable of restraining deficits and de-escalating conflicts, both of which are traditionally dollar-negative in the short run because they reduce the safe-haven premium embedded in US assets. The euro's rise to $1.1229 was small but directionally consistent with this interpretation.
Currency moves of this magnitude are easily reversed and should not be over-interpreted. Yet they matter for multinational corporations, whose reported earnings are sensitive to translation effects, and for emerging market economies that borrow in dollars. A softer dollar eases the debt-service burden of dollar-denominated borrowers and can support commodity prices, though the oil collapse in this session overwhelmed any such support. Investors with global exposure should monitor whether the dollar's dip extends into a trend or fades as attention returns to relative growth and interest rate differentials.
Governorships, Data Centres and the Local Politics of Infrastructure
Beyond Washington, Democrats captured governorships in states including Texas, Georgia and Ohio, and in each of those contests opposition to data centres featured as a campaign issue. This is a development of considerable significance for the technology sector, because data centre siting is fundamentally a local and state matter. Federal policy sets the broad regulatory framework, but zoning, water rights, electricity supply and tax abatements are negotiated at the state and municipal level. A shift in gubernatorial control can therefore alter the economics of the AI buildout far more directly than any congressional hearing.
The Grid, Water and Zoning Constraints on AI Expansion
Artificial intelligence infrastructure is extraordinarily resource-intensive. Large data centres consume electricity on the scale of small cities and require substantial water for cooling, placing them in direct competition with residential and agricultural users. Communities that once welcomed the tax revenue and construction jobs have grown more sceptical as power bills rise and aquifers are drawn down. Candidates who promised to scrutinise or restrict data centre approvals won votes on that basis, and their victories signal that the social licence for unfettered expansion is narrowing in key states.
For investors in the AI supply chain, this represents a genuine and underappreciated risk. The demand for chips, servers and networking equipment is derived from the assumption that data centres will be built at a certain pace. If local opposition slows permitting, stretches grid connections or imposes costly environmental conditions, that assumption weakens. Nvidia's decline on the session, even as the broader market rallied, suggests some investors are already pricing this risk. The constraint is not computational but physical and political, and it will shape the sector's trajectory for years.
Legislative Gridlock and the Limits of Divided Government
A Democratic Congress can block legislation, open investigations into the Trump administration and influence government budgets, including the Pentagon's. What it cannot do, absent supermajorities, is enact sweeping new programmes of its own. The realistic expectation is therefore gridlock punctuated by oversight, a configuration that markets often find congenial because it forecloses disruptive change. The president retains substantial executive authority over foreign policy, trade and regulation, so the practical effect of divided government may be less dramatic than either party's rhetoric suggests.
Investors should calibrate their expectations accordingly. The sectors most exposed are those whose fortunes depend on specific budget lines, such as defence procurement and renewable energy incentives, and those subject to intense congressional scrutiny, such as technology platforms and financial institutions. For the broad market, the dominant implication is stability rather than transformation. The relief rally captured that judgement efficiently, and the subsequent weeks will reveal whether the underlying fundamentals justify the optimism or whether the session was merely a release of pent-up tension.
What the Session Reveals About Election-Driven Market Behaviour
Stepping back from the individual data points, the post-election session offers a compact case study in how markets process political information. The dominant reaction was relief, expressed through a broad equity rally and a sharp decline in oil. The secondary reaction was dispersion, expressed through sector and single-stock moves that reflected specific policy expectations. The tertiary reaction was international, expressed through European gains, Japanese weakness and modest currency shifts. Understanding this hierarchy helps investors anticipate how future political events will propagate through portfolios, and which exposures are most likely to amplify or dampen the initial shock.
Separating Signal From Noise in Political Trades
Political trades are notoriously prone to overreaction. Markets form expectations before votes, position accordingly, and then adjust violently when the outcome differs from the consensus. The adjustment is often larger than the underlying change in fundamentals warrants, because it reflects the unwinding of positioning rather than a reassessment of value. The Dow's fifteen-hundred-point gain is a case in point: it is implausible that the intrinsic value of American enterprise rose by three percent overnight, but entirely plausible that investors who had hedged the event no longer needed their hedges.
Disciplined investors therefore treat election sessions as opportunities to rebalance rather than to chase. If a stock falls sharply because of a political headline but its long-term cash flows are unaffected, the decline may be a buying opportunity. If a stock rises because of relief but faces genuine policy headwinds, the rally may be a chance to reduce exposure. The key is to distinguish between changes in the political weather, which are transient, and changes in the political climate, which are structural. Most election results alter the weather; only occasionally do they alter the climate.
Positioning for the Legislative Year Ahead
The months following the midterms will bring committee hearings, budget negotiations and the slow grind of legislative business. Investors should watch the appropriations process closely, particularly for defence and energy programmes, and monitor which investigations Congress chooses to pursue. The data centre question will play out primarily at the state level, where newly elected governors will shape permitting regimes. Currency markets will respond to the evolving balance between fiscal restraint and geopolitical de-escalation. None of these developments will arrive overnight, and patient investors will have ample time to adjust their portfolios as the picture clarifies.
The overarching lesson is that political outcomes matter to markets chiefly through the uncertainty they resolve and the specific policies they enable or foreclose. The 2026 midterms resolved a great deal of uncertainty and foreclosed a small number of policies, which is precisely the combination that produces a relief rally. Whether that rally matures into a durable advance depends on earnings, interest rates and the physical constraints on the AI buildout, none of which were settled by the vote. Investors who keep that distinction in view will navigate the coming year with greater clarity than those who mistake a single session's euphoria for a lasting trend.
From our network :
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
RESOURCES
- Wall Street ends higher after Democrats win Congress; data center ...reuters.com8 hours ago ... Wall Street closed sharply higher on Wednesday as Democrats' sweeping midterm election victory eased political uncertainty and boosted risk ...
- Stock market news for Nov. 4, 2026 - CNBCcnbc.com10 hours ago ... Stocks ripped higher on Wednesday after a decisive victory by Democrats in the U.S. midterm elections removed political risk that…
- World shares advance as Democrats' victory eases ... - Reutersreuters.com1 day ago ... Global stocks rallied on Wednesday after Democrats seized control of both chambers of Congress in the US midterm elections, ...
- U.S. Stocks Jump After Democrats Sweep Congress - WSJwsj.com12 hours ago ... ... elections giving way to a relief rally ... Treasury yields fell after the Democratic party's overwhelming win in the…
- US stock markets and government bonds rally while dollar falls after ...theguardian.com1 day ago ... Wall Street is expected to open higher in less than half an hour, after Democrats secured sweeping victories in the…
- US Midterms: How Markets Are Reacting to Democrat Victoryglobal.morningstar.com17 hours ago ... The Democratic Party has stormed to victory in the US midterm elections ... AI Stocks Under Pressure, Bonds Rally, and…
- US stocks rise, dollar slides as investors digest Democrats' midterm ...theguardian.com22 hours ago ... US stocks have surged as investors digest the Democrats' victories in the midterm elections ... rally. Trump's wealth dented after…
- World shares advance as Democrats' victory eases political ...finance.yahoo.com10 hours ago ... ... stocks rallied on Wednesday after Democrats seized control of both chambers of Congress in the US midterm elections,
- US stocks rally but Tesla's falls after Democrats win big in midtermsapnews.com10 hours ago ... World shares are mostly higher after the U.S. midterm election results showed the Democrats gaining majorities in both houses of…
- Wall Street ends higher after Democrats win Congress; data center ...finance.yahoo.com10 hours ago ... "Stocks are sharply higher today as election clarity reduces uncertainty," said Terry Sandven, chief equity strategist at U.S. Bank Wealth ...
- Stocks Rise as Democrats Flip Control of Congressnytimes.com10 hours ago ... ... midterm election victory that surpassed the party's most optimistic expectations. ... Asian markets turned around and a broad rally…
- US Stocks Surge as Election Drives Oil Down, Fuels Tech Optimismbloomberg.com10 hours ago ... US stocks surged as Democrats' victory in midterm elections ... Overall, stocks have tended to rally after midterm elections. Since ...
- U.S. stocks are surging after President Donald Trump's party lost its ...facebook.com12 hours ago ... WALL STREET RALLIES AFTER DEMOCRATS' HISTORIC MIDTERM VICTORY U.S. stocks ... U.S. Midterm Elections: Democrats Sweep Congress in Major ...
- US stocks rally at open after Democrats win control of Congressaa.com.tr17 hours ago ... Dow Jones jumps more than 1000 points in early trading as Wall Street's volatility gauge falls nearly 15% following US…
- U.S. Stocks Rally Following Democrats' Decisive Midterm Election ...rttnews.com15 hours ago ... Stocks have moved sharply higher during trading on Wednesday, with the major averages all showing strong moves to the upside…
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments