Qualcomm's share price reaction in early November 2026 captured a tension that has defined the semiconductor industry for the better part of a decade: a company can post respectable numbers, forecast encouraging growth in adjacent markets, and still watch its valuation compress because one legacy revenue engine is sputtering. The chipmaker's stock declined after investors weighed upbeat guidance for non-smartphone segments against persistent softness in handset demand, a dynamic that speaks less to any single quarter's results than to the structural question of how quickly a mobile-centric silicon vendor can diversify before its core market matures further.
What makes the episode instructive is the gap between narrative and arithmetic. Qualcomm has spent years building out automotive, Internet of Things, and edge computing franchises, and management has consistently framed these as the growth story of the next decade. Yet the smartphone segment still contributes the overwhelming majority of revenue, which means sentiment toward handsets continues to dominate the share price even when the diversification story is objectively progressing. Investors, in effect, are pricing the present while management is selling the future, and the market's verdict on any given earnings day depends on which of those two clocks is ticking louder.
This analysis examines the forces behind that divergence, from the cyclical mechanics of handset replacement cycles to the competitive and geopolitical pressures shaping Qualcomm's licensing model. It considers how the company's diversification efforts are actually performing, what the smartphone weakness signals about consumer demand in key markets, and how investors should interpret a stock reaction that seems to punish execution on the growth strategy simply because the legacy business remains large enough to obscure it.
On This Page
TL;DR Qualcomm's shares fell in November 2026 despite upbeat guidance for non-smartphone segments, because lingering weakness in handset demand continues to dominate investor sentiment. The company's diversification into automotive, IoT, and edge computing is real and growing, but the smartphone segment remains large enough that its cyclical softness overwhelms the growth narrative on any given earnings day. The episode illustrates a broader truth about semiconductor investing: revenue mix, not revenue growth alone, determines how the market prices a chipmaker's future. Investors should watch segment-level disclosure and design-win pipelines rather than headline guidance, and recognize that the transition from mobile-centric to diversified silicon supplier is a multi-year process that will produce volatile sentiment along the way.
The Anatomy of a Share Price Reaction
When Qualcomm's stock declined following its November 2026 update, the immediate explanation offered by market commentary was straightforward: smartphone weakness overshadowed growth plans. That framing is accurate but incomplete, because it treats the share price as a simple referendum on demand rather than a forward-looking discounting mechanism that weighs the probability and timing of a revenue mix shift. Investors were not rejecting the diversification strategy; they were recalibrating how long it would take for that strategy to matter at the consolidated level, and how much cyclical risk they would absorb in the interim.
Why Guidance Beat but the Stock Fell
The apparent paradox of upbeat non-smartphone guidance coexisting with a falling share price resolves once you examine what the market had already priced in. Qualcomm's automotive and IoT franchises have been the subject of optimistic modeling for several quarters, and when management confirms that optimism, the confirmation itself carries little incremental information. What moves the stock is the surprise component, and in this case the surprise was concentrated on the downside: handset demand that remained softer than consensus had assumed, pushing out the timeline for the recovery that many investors had baked into their models.
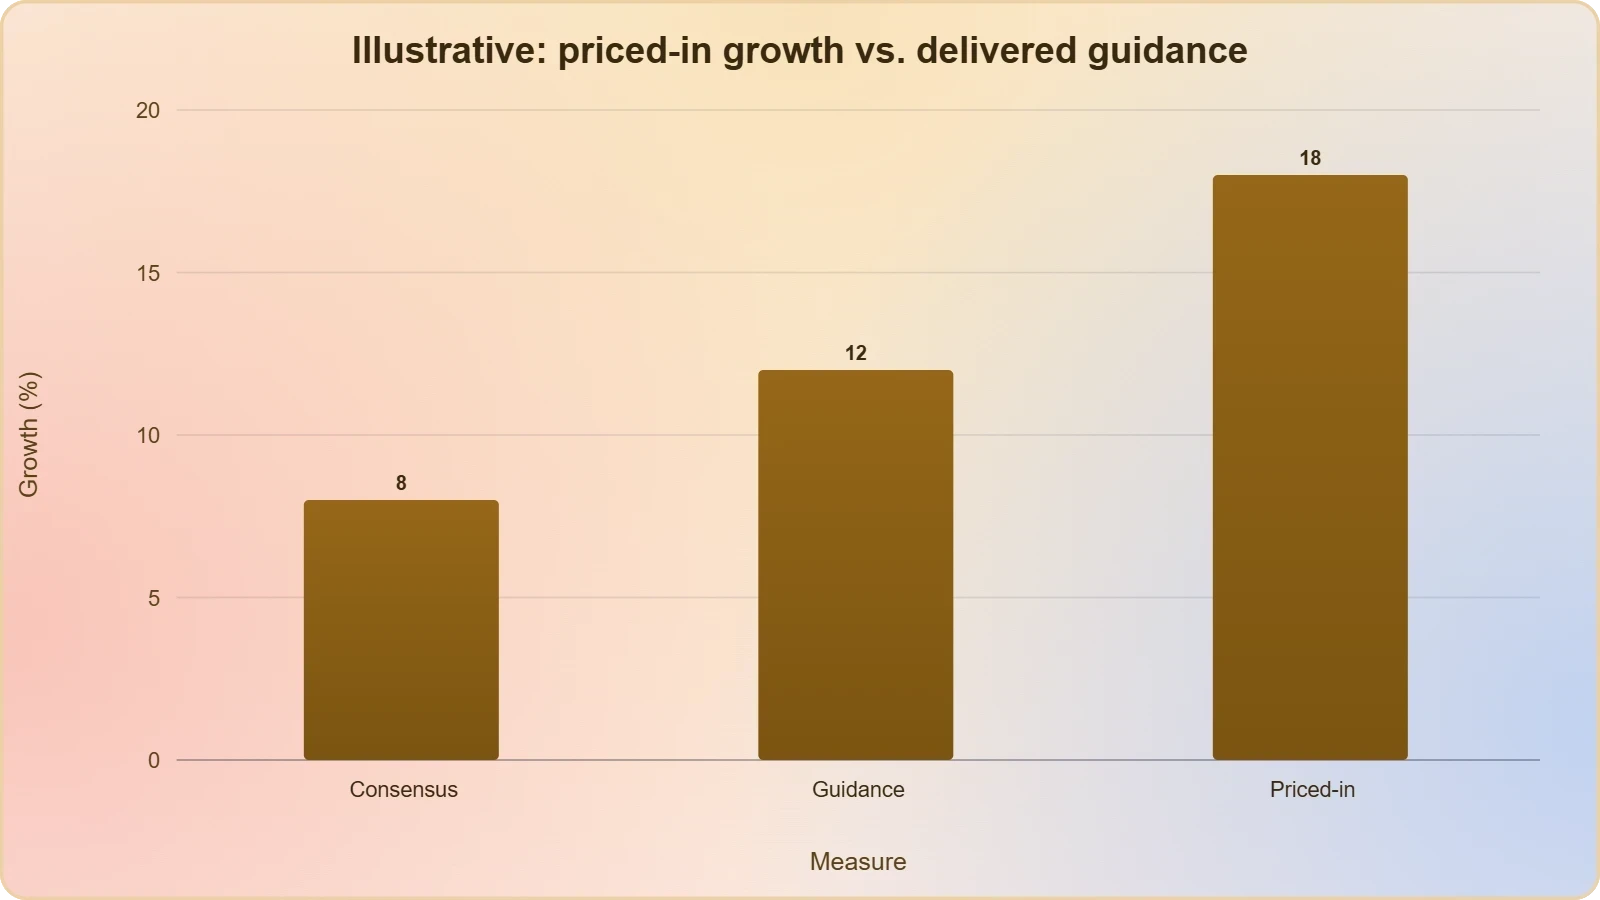
There is also a mechanical dimension worth noting. Qualcomm's licensing business, QTL, generates high-margin revenue tied to handset unit volumes, which means a modest decline in device shipments can produce an outsized effect on profitability and free cash flow. When investors mark down handset expectations, they are simultaneously marking down the most profitable slice of the business, and the resulting earnings revisions can be sharper than the underlying unit decline would suggest. That leverage to volume is a feature of the business model, but in a soft demand environment it amplifies negative sentiment.
The Sentiment Multiplier in Semiconductor Equities
Semiconductor stocks trade at valuations that embed substantial expectations about future growth, which makes them unusually sensitive to changes in the perceived trajectory rather than the current level of demand. A company can meet earnings estimates and still see its multiple compress if the forward narrative weakens, because the multiple is a claim on future cash flows that must now be discounted over a longer or less certain horizon. Qualcomm's reaction fits this pattern precisely: the numbers were defensible, but the story about when handsets would recover became less clear, and the market repriced accordingly.
This sentiment multiplier is not irrational. It reflects the genuine difficulty of forecasting demand in a market where replacement cycles have lengthened, where macroeconomic conditions vary sharply across regions, and where competitive dynamics can shift pricing power quickly. Investors who hold semiconductor equities are compensated for bearing that uncertainty, but they also demand evidence that the uncertainty is resolving in a favorable direction. When the evidence points the other way, even temporarily, the repricing can be swift and disproportionate to the fundamental change.
The Smartphone Market's Structural Softness
The weakness that clouded Qualcomm's growth plans is not a sudden shock but the continuation of a pattern that has been building for several years. Global smartphone shipments have plateaued as penetration saturates in mature markets, replacement cycles have lengthened as device improvements become incremental rather than transformative, and consumers have shown a willingness to hold onto handsets for three or four years rather than the two-year cadence that once defined the industry. These are structural forces, not temporary dips, and they impose a ceiling on the volume growth available to any component supplier.
Lengthening Replacement Cycles and Their Consequences
The lengthening of replacement cycles deserves particular attention because it changes the economics of the entire supply chain. When consumers upgrade less frequently, the installed base ages, and the addressable market for each new device generation shrinks relative to the total user population. For Qualcomm, this means that even maintaining share requires winning a larger proportion of a smaller upgrade pool, and pricing pressure intensifies as device makers compete for fewer buyers. The company's premium-tier positioning offers some protection, but premium handsets are themselves a mature category in most developed markets.
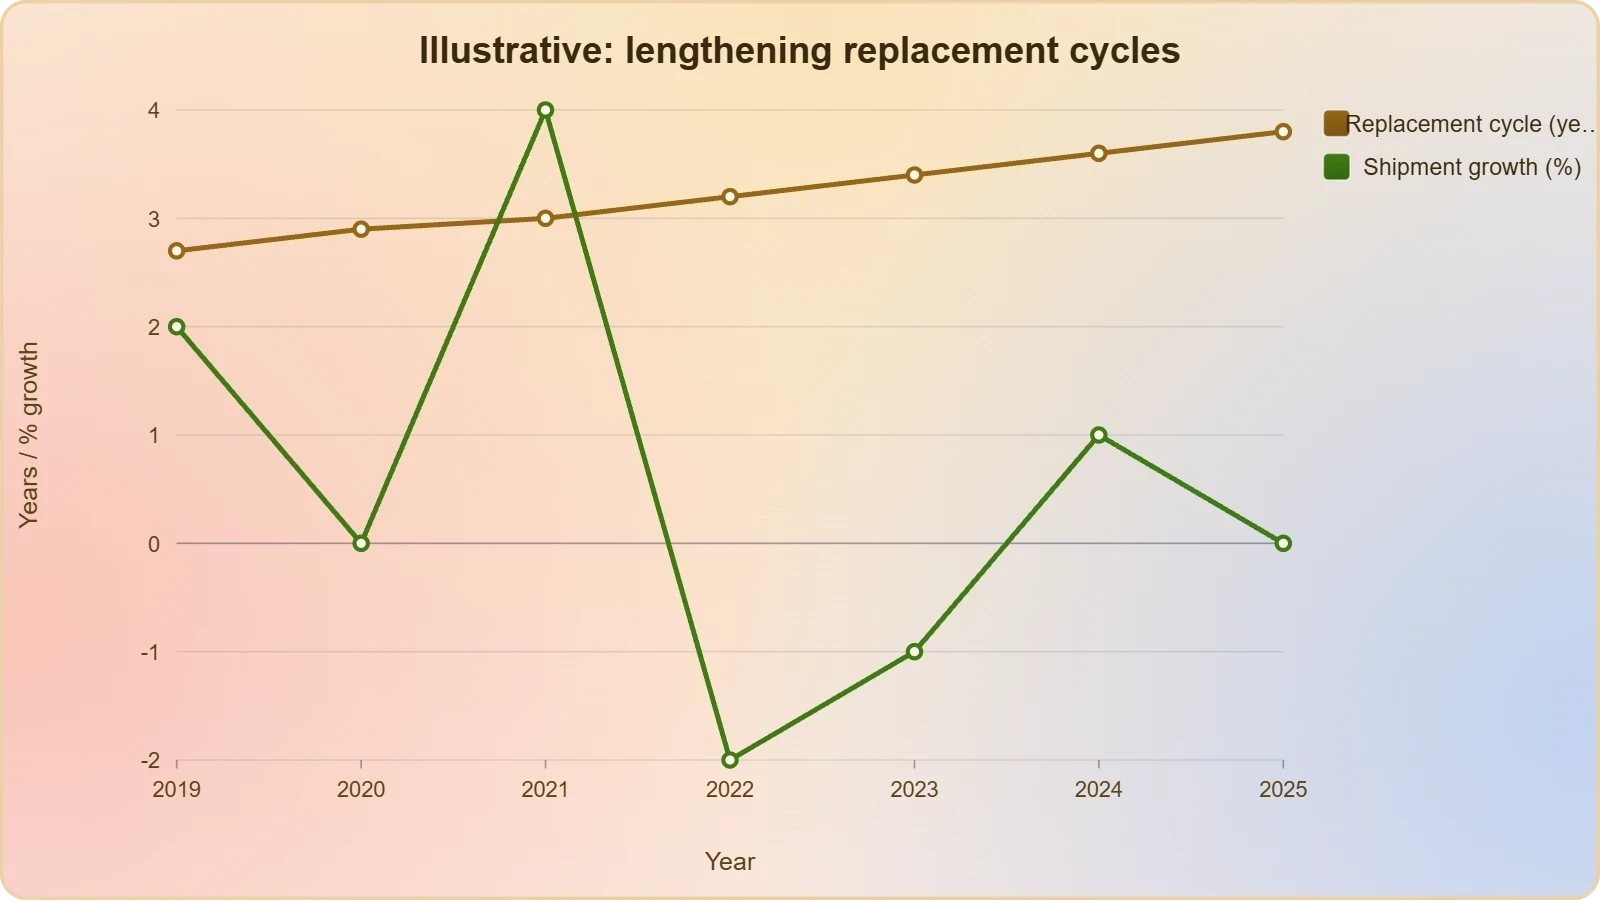
There is a counterargument worth considering: longer cycles concentrate demand into higher-value devices when upgrades do occur, and consumers who wait longer often choose more capable handsets with richer silicon content. That dynamic can support average selling prices and, by extension, Qualcomm's content per device. The problem is that this offset operates at the margin and cannot fully compensate for volume softness in the near term, which is precisely why the market reacted as it did. Structural offsets are real but slow; sentiment responds to the fast-moving volume data.
Regional Divergence in Demand
Smartphone demand is not uniformly weak across the globe, and the regional picture matters enormously for a company with Qualcomm's geographic exposure. Emerging markets continue to show unit growth as first-time buyers enter the ecosystem, but the devices sold there tend to carry lower silicon content and thinner margins. Meanwhile, the premium-heavy markets of North America, Europe, and parts of East Asia are where Qualcomm's most profitable content resides, and those are precisely the markets where replacement cycles have stretched most dramatically. The geographic mix therefore works against the company during soft periods.
China deserves separate consideration given its scale and its role in both demand and competition. Domestic handset makers are a major customer base for Qualcomm, but they are also increasingly developing in-house silicon capabilities and sourcing from alternative suppliers. That creates a dual pressure: softer domestic demand reduces the volume opportunity, while competitive substitution erodes share within whatever volume remains. The net effect is that China, long a growth engine, can become a source of variance in either direction depending on how these two forces balance in a given period.
Diversification: Progress Against a Long Timeline
The most important thing to understand about Qualcomm's diversification is that it is working, just not fast enough to change the consolidated narrative. Automotive has become a genuinely material business, built on design wins that were secured years ago and are now entering production. IoT and edge computing span industrial, networking, and consumer applications that collectively represent a large addressable market. The company has also invested in PC and extended reality silicon, betting that computing will migrate toward mobile architectures. Each of these is a legitimate growth vector, and together they represent a credible path away from handset dependence.
Automotive and the Design-Win Pipeline
Automotive silicon is the clearest proof point because its economics are so different from handsets. A design win in a vehicle platform typically locks in revenue for the life of that model, which can span five to seven years, and the content per vehicle is rising as software-defined architectures require more compute, connectivity, and sensing silicon. This creates a revenue stream that is less cyclical than handsets and more predictable once production begins. The catch is timing: design wins precede revenue by several years, so the pipeline's strength is visible in disclosures long before it appears in the income statement.
Investors who focus only on quarterly revenue therefore miss the most important leading indicator in the automotive story. The relevant metric is the cumulative value of awarded programs, which management has disclosed and which has grown substantially. That pipeline converts into revenue on a schedule that is largely independent of consumer sentiment, which is precisely the quality that diversification is meant to provide. The frustration for shareholders is that this conversion is gradual, and in any given quarter the automotive contribution, however fast it is growing, remains too small to offset a meaningful handset decline.
IoT, Edge Computing, and the PC Bet
The IoT and edge computing portfolio is more fragmented than automotive but collectively larger in addressable terms. It spans industrial automation, retail systems, networking equipment, and consumer devices, each with different cycles and different competitive dynamics. This fragmentation is both a strength and a weakness: it diversifies risk, but it also makes the segment harder for investors to model and therefore easier to discount. Qualcomm has worked to sharpen its disclosure here, but the market still tends to treat IoT as a collection of optionality rather than a dependable earnings base.
The PC initiative represents a longer-dated bet on architecture migration. If computing increasingly shifts toward power-efficient mobile-derived designs, Qualcomm is positioned to capture share in a market historically dominated by x86 incumbents. The early traction has been encouraging, but the addressable opportunity depends on software ecosystem maturity and enterprise adoption cycles that move slowly. Investors should treat this as a call option on a multi-year shift rather than a near-term earnings driver, and should calibrate their expectations accordingly when evaluating the diversification narrative.
We Also Published
- 01
- 02
- 03
- 04
The Licensing Model Under Pressure
Qualcomm's licensing business is the most misunderstood and most consequential part of its financial architecture. QTL collects royalties on handsets that use its patented technologies, and because the marginal cost of licensing is negligible, the segment generates margins that far exceed the chip business. This makes QTL a disproportionate contributor to profitability and free cash flow, and it means that handset volume trends transmit directly into the most valuable part of the enterprise. When device shipments soften, the royalty base contracts, and the earnings impact is amplified by the segment's high margin structure.
Royalty Rates, Litigation, and Regulatory Risk
The licensing model has also attracted sustained legal and regulatory scrutiny across multiple jurisdictions, and the outcomes of those disputes shape the royalty rates Qualcomm can charge. Every renegotiation or adverse ruling carries the potential to reset the economics of the segment, which is why investors monitor legal developments as closely as they monitor demand. The company has generally defended its rate structure successfully, but the recurring nature of the challenges introduces a persistent risk premium into the valuation that would not exist if the licensing revenue were more secure.
There is a strategic dimension to this as well. Licensing revenue depends on the continued relevance of Qualcomm's patent portfolio to the technologies that handsets actually use, particularly in cellular standards. As the industry transitions through successive generations of wireless technology, the company must maintain its position in standard-essential patent pools while also defending against efforts by licensees to reduce rates. This is a continuous process rather than a one-time negotiation, and it requires sustained investment in research that feeds the patent pipeline.
Customer Concentration and Bargaining Power
Qualcomm's customer base is concentrated among a relatively small number of large handset makers, which gives those customers substantial bargaining power in both chip procurement and licensing negotiations. Concentration cuts both ways: it creates dependence on the fortunes of a few key accounts, but it also means that Qualcomm's technology is deeply embedded in the flagship devices those accounts depend on for their own profitability. The balance of power shifts with market conditions, and in a soft demand environment, customers have more incentive to press for favorable terms.
The rise of in-house silicon at major customers adds a further layer of complexity. When a large handset maker develops its own modem or applications processor, it reduces its reliance on Qualcomm for that component, which weakens Qualcomm's position in procurement negotiations and can eventually affect licensing discussions as well. This is a slow-moving threat rather than an immediate one, but it is directionally important because it erodes the structural advantages that have historically supported both the chip and licensing businesses.
Competitive and Geopolitical Crosscurrents
Qualcomm operates in a competitive environment that has become more demanding on several fronts simultaneously. MediaTek has established itself as a formidable rival in the mid-tier and premium Android segments, offering competitive performance at aggressive price points. Apple has progressively brought modem development in-house, reducing its reliance on Qualcomm over time. Chinese handset makers are investing in their own silicon capabilities. Each of these developments erodes the addressable market for Qualcomm's merchant chip business, and together they represent a structural headwind that operates independently of cyclical demand swings.
The MediaTek Rivalry and Premium Tier Defense
The competition with MediaTek is particularly consequential because it plays out in the Android ecosystem where Qualcomm derives a large share of its handset revenue. MediaTek's strategy of offering strong performance at lower price points has won share in mid-tier devices, and its ambitions extend upward into the premium tier. Qualcomm's response has been to emphasize performance leadership and to invest in differentiated capabilities, particularly in AI processing and connectivity, that justify a price premium. Whether that differentiation remains sufficient as MediaTek closes the performance gap is one of the central questions for the handset business.
Premium tier defense matters disproportionately because that is where the margin resides. A device sold at the flagship level carries substantially more silicon value than a mid-tier device, so maintaining share at the top of the market is worth more than equivalent share at the bottom. Qualcomm has historically been strongest in premium Android devices, and that position has been reinforced by its integration of advanced modem, processing, and AI capabilities. The risk is that premium-tier differentiation narrows as competitors improve, compressing the pricing premium over time.
Export Controls and Supply Chain Geography
Geopolitical factors add a layer of uncertainty that is largely outside the company's control. Export controls affecting semiconductor trade between the United States and China can restrict the addressable market for certain products, and the rules have been subject to periodic revision. For a company with substantial exposure to Chinese handset makers, changes in the regulatory environment can alter revenue expectations with little notice. Qualcomm has managed these constraints by operating within the rules and by diversifying its customer base, but the risk remains embedded in the business.
Supply chain geography is a related consideration. The semiconductor industry's dependence on concentrated manufacturing capacity in a small number of locations creates vulnerability to disruptions, whether from natural events, geopolitical tension, or policy changes. Qualcomm is fabless, which means it relies on foundry partners for production, and its ability to secure capacity on favorable terms depends on its relationships and its scale. These arrangements have generally served the company well, but they are a reminder that the business operates within a complex global system that can transmit shocks quickly.
What Investors Should Watch Next
The lesson of Qualcomm's November 2026 share reaction is that headline guidance is a poor guide to how the market will respond. What matters is the relationship between the growth segments and the legacy base, and the pace at which the former can offset the latter. Investors who want to track this transition should focus on a small number of high-signal indicators: the cumulative value of automotive design wins, the trajectory of IoT revenue relative to management's targets, the stability of licensing rates, and the direction of handset unit expectations in premium markets. These metrics reveal the underlying trajectory more reliably than any single quarter's earnings beat or miss.
Segment Disclosure and the Quality of Earnings
Segment-level disclosure is the most valuable tool available to investors trying to see through the consolidated noise. When a company's overall revenue is dominated by one segment, the consolidated figures can obscure rapid growth elsewhere, and the market's reaction can therefore misprice the diversification progress. Qualcomm has improved its disclosure over time, and investors should use it to build a picture of the underlying mix shift. The key question is not whether non-handset revenue is growing, but whether it is growing fast enough to change the consolidated growth rate within a reasonable investment horizon.
Quality of earnings matters here as well. Licensing revenue and chip revenue have very different margin profiles, so a shift in mix between them affects profitability independently of volume. Investors should pay attention to the gross margin trajectory and to management's commentary on the durability of licensing rates, because those factors determine how much of each incremental revenue dollar flows to the bottom line. A company growing its lower-margin segments while its high-margin licensing base contracts may be diversifying successfully in revenue terms while simultaneously eroding its profitability profile.
Valuation Frameworks for a Transitioning Business
Valuing a company in the middle of a revenue mix transition requires more than applying a single multiple to consolidated earnings. A sum-of-the-parts approach, which values each segment according to its growth and margin characteristics, can reveal whether the market is pricing the diversification story at all. If the non-handset segments are being assigned little or no value, that represents an opportunity for investors who believe the transition will succeed. Conversely, if the market is already capitalizing those segments at generous multiples, the risk is that disappointment in the legacy business drags down the whole valuation regardless of progress elsewhere.
The practical implication is that investors should be explicit about what they are paying for. A Qualcomm share at any given price embeds assumptions about handset stabilization, licensing durability, and diversification success, and the relative weight of those assumptions determines the risk profile. Understanding which assumption is doing the most work in the valuation allows investors to monitor the right variables and to react appropriately when the evidence changes. The November 2026 reaction was, in essence, the market revising one of those assumptions downward while leaving the others intact.
The broader significance of Qualcomm's situation extends beyond a single company's share price. It illustrates how the semiconductor industry's largest players must navigate the transition from a dominant growth market to a diversified portfolio, and how the market's patience during that transition is neither unlimited nor evenly distributed. Companies that can demonstrate tangible progress in their new segments while managing the decline of their legacy base will be rewarded; those that cannot will find their valuations anchored to the maturing business regardless of how compelling the long-term story may be. Qualcomm's diversification is real, but the market's verdict in November 2026 was a reminder that real is not the same as sufficient.
From our network :
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
RESOURCES
- Qualcomm shares slide as smartphone weakness clouds growth pushreuters.com8 hours ago ... Qualcomm on Wednesday fell short of Wall Street estimates for fourth-quarter smartphone chip sales on sluggish demand and declining ...
- Qualcomm stock slides after Q3 earnings top revenue expectations ...finance.yahoo.comJul 30, 2026 ... And we're seeing unit growth has gone negative," he added. According to CounterPoint Research, Q2 global smartphone shipments fell 11%…
- Qualcomm vs MediaTek Q1 2026 Earnings: Smartphone Weakness ...linkedin.comApr 30, 2026 ... Qualcomm vs MediaTek: Same headwinds, different growth engines Both #Qualcomm and ...
- Can Qualcomm's QCT Segment Sustain Growth Amid Handset ...tradingview.comJun 22, 2026 ... The company expects this weakness in the smartphone market to continue in the third quarter. Amid this backdrop, the automotive…
- Qualcomm and Arm see momentum in AI, but smartphone weakness ...siliconangle.comJul 29, 2026 ... The chipmaker said it's planning to unveil a new AI ... smartphone sales, overshadowing its expansion in AI data center…
- Can Qualcomm's QCT Segment Sustain Growth Amid Handset ...theglobeandmail.comJun 22, 2026 ... The company expects this weakness in the smartphone market to continue in the third quarter. Amid this backdrop, the automotive…
- Qualcomm Q3 FY 2026: Automotive Growth Offsets Handset ...futurumgroup.comAug 3, 2026 ... ... weakness, automotive growth, pricing actions, and early data center revenue plans ... weakness reflects memory-driven pressure on smartphone ...
- Qualcomm Fell 10% in the Last 30 Days. Here's Where the Stock ...tikr.comApr 1, 2026 ... This month, Qualcomm highlighted progress in its diversification strategy ... Revenue growth remains modest because Qualcomm's core smartphone ...
- Qualcomm forecasts weak quarterly profit, expects Apple revenue ...wmbdradio.comJul 29, 2026 ... ... smartphones. On an earnings conference call, Chief Financial Officer Akash Palkhiwala said growth in Qualcomm's non-handset businesses in ...
- Qualcomm and the Blindness of the Bears: OpenAI Just Changed ...drrobertcastellano.substack.comApr 27, 2026 ... Smartphone Weakness Drives the Bear Case. The primary argument behind recent downgrades centers on the outlook for global smartphone demand ...
- MediaTek and Unisoc Post Double-digit Shipment Growth in ...businesswire.comAug 5, 2022 ... Qualcomm led the smartphone AP market with a 45 percent revenue ... The low-end smartphone market demand is currently weak.…
- Qualcomm Rallies on Data Center Inroads, China Recoverybloomberg.comApr 29, 2026 ... Qualcomm said the Chinese smartphone sector would bottom out in the third quarter "and return to sequential growth in the…
- The Real Engine Driving Qualcomm Stock Isn't A Smartphone - Trefistrefis.comJul 20, 2026 ... That makes the next automotive growth figure the one number to watch. Turning One Good Number Into A Strategy. One…
- Emmanuel – Big Tech & AI Investor on X: "QUALCOMM $QCOM Q4'26x.com11 hours ago ... ... growth strategy. THE NUMBERS ... growth can become large enough to offset the weakness in Qualcomm's traditional smartphone business.
- Qualcomm gave a weak profit forecast for the current quarter ...facebook.comJul 29, 2026 ... Qualcomm plans global job cuts as part of a performance-based ... Qualcomm earnings take hit on weak smartphone sales. Qualcomm ...
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments