The DSE Brokers Association of Bangladesh has formally asked the government to exempt individual and foreign investors from tax on capital gains derived from listed securities until 2030, a proposal submitted last week to Finance and Planning Minister Amir Khosru Mahmud Chowdhury alongside the Prime Minister's Special Assistant for Investment and Capital Market, the Bangladesh Securities and Exchange Commission Chairman, and the National Board of Revenue Chairman. The association argues that a predictable, tax-free horizon would restore investor confidence, deepen market liquidity, and steer domestic savings toward long-term equity participation rather than short-term speculation. The request arrives at a delicate moment for Bangladesh's capital market, where trading volumes have thinned and listed companies struggle to raise equity financing.
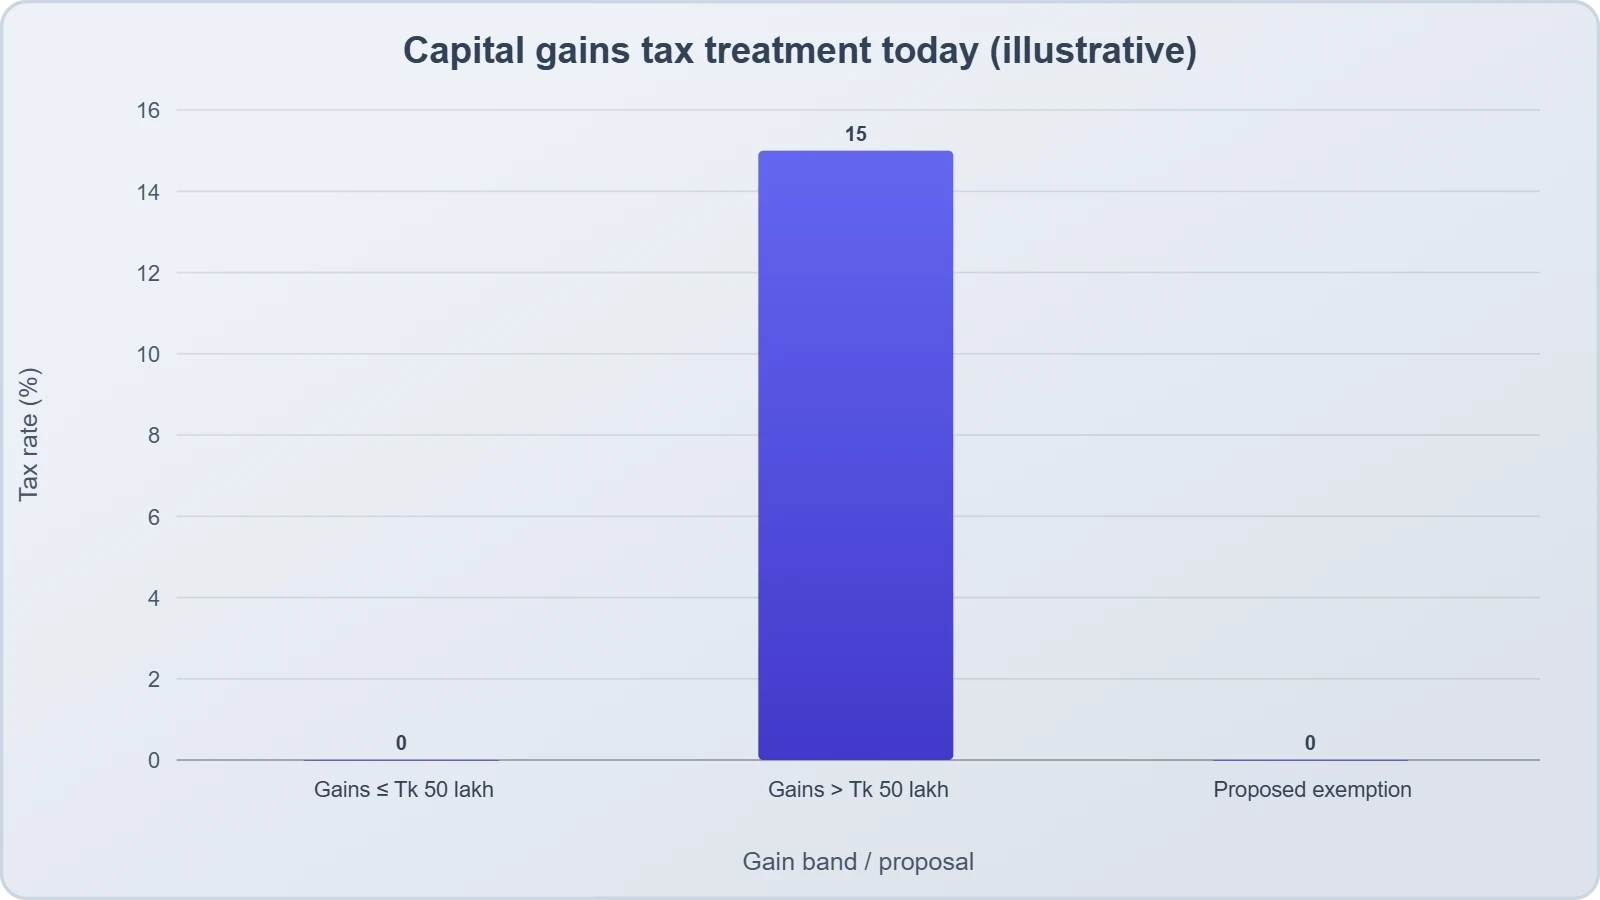
At present, individual investors in Bangladesh pay no tax on capital gains of up to Tk 50 lakh from listed securities, while gains above that threshold are generally taxed at 15 percent. The brokers' body proposes a full exemption for individual investors and a revision of the rules governing foreign individual and institutional investors, framing the change as a catalyst for more trading, the reinvestment of profits, and more productive use of domestic savings. The association also contends that a friendlier tax regime would help listed companies raise equity financing, support the government's capital market development agenda, and align Bangladesh with regional peers that already offer preferential treatment to portfolio investors.
The proposal carries a specific sunset logic: the exemption should remain in place until 2030, when Central Counterparty Bangladesh Limited is expected to be fully operational, making the calculation of capital gains and the determination of tax liabilities materially easier. Notably, the association has supported keeping the existing tax arrangements for sponsors, directors, and institutional investors, drawing a deliberate line between retail and foreign portfolio participants on one side and insiders on the other. This analysis examines the economics, the legal mechanics, and the strategic implications of that request.
On This Page
- The Economic Logic Behind a Capital Gains Holiday
- The Legal Mechanics: Amending the Income Tax Act 2023
- Market Liquidity and the Confidence Channel
- Regional Comparisons and Competitive Positioning
- Implementation Pathways and Policy Sequencing
- Strategic Implications for Bangladesh's Capital Market
- Conclusion: A Test of Policy Credibility
TL;DR Bangladesh's DSE Brokers Association wants individual and foreign investors exempted from capital gains tax on listed securities until 2030, when Central Counterparty Bangladesh Limited should be fully operational and able to simplify gain calculation and tax determination. The group argues the move would restore confidence, improve liquidity, encourage long-term investment, and help listed companies raise equity. Current rules exempt individual gains up to Tk 50 lakh, with a 15 percent rate above that. The proposal would amend the Income Tax Act 2023 for exchange-traded, centrally settled transactions, while leaving tax arrangements for sponsors, directors, and institutional investors untouched.
The Economic Logic Behind a Capital Gains Holiday
Capital gains taxation sits at the intersection of revenue policy and market microstructure, and the Bangladeshi proposal reflects a well-documented tension. When investors expect a significant portion of their returns to be taxed at exit, they shorten holding periods, trade less frequently, or avoid the market altogether. The brokers' association is effectively arguing that the revenue foregone on individual and foreign gains would be more than offset by higher transaction volumes, greater turnover taxes, and a broader investor base. This is the classic elasticity argument: lower effective tax rates can raise total revenue when the tax base expands sufficiently, particularly in thin markets where participation is highly responsive to after-tax returns.
The liquidity dimension deserves particular attention. Bangladesh's premier bourse has contended with subdued turnover and a narrow institutional base, conditions in which transaction costs and tax friction weigh disproportionately on retail participation. A capital gains exemption functions as a direct subsidy to trading activity, reducing the round-trip cost of equity investment and making the market more attractive relative to fixed deposits and savings certificates. The association's framing that the change would encourage "reinvestment of profits and productive use of domestic savings" captures the intended transmission channel: from idle deposits into equity capital formation.
Why Foreign Investors Are Central to the Proposal
Foreign portfolio investment in Bangladesh has historically been constrained by a combination of liquidity concerns, currency risk, and tax uncertainty. The association's call to revise tax rules for foreign individual and institutional investors addresses the last of these directly. For a global allocator comparing frontier and emerging markets, the after-tax treatment of capital gains is a material input in the country allocation decision, and jurisdictions that offer clarity and predictability tend to attract disproportionate flows relative to their economic size. A defined exemption window through 2030 gives foreign investors a calculable horizon.
The timing matters because Bangladesh is competing for a finite pool of frontier-market capital against Vietnam, Sri Lanka, and several African markets that have actively reformed their investment regimes. A tax holiday is a relatively low-cost signal of openness, requiring no fiscal outlay until gains would otherwise have been taxed, and it can be reversed or extended depending on market conditions. The association's proposal therefore functions as a competitive positioning move as much as a domestic stimulus measure, and its success will depend on how credibly the government commits to the 2030 horizon.
The Revenue Trade-off and Fiscal Caution
Revenue authorities rarely embrace base erosion without evidence, and the National Board of Revenue's response will hinge on whether the exemption is expected to be self-financing. In practice, capital gains tax collections from listed securities in Bangladesh are modest relative to consumption taxes and corporate income tax, which lowers the fiscal cost of the proposal but also weakens the argument that the exemption is a major stimulus. The more persuasive case is dynamic: a deeper, more liquid market lowers the cost of equity for listed companies, which in turn supports investment, employment, and eventually broader corporate tax receipts.
Critics will note that tax holidays can distort behavior, encouraging investors to realize gains before the window closes or to structure holdings around the exemption rather than around fundamentals. The association's proposal mitigates this somewhat by tying the exemption to exchange execution and central depository settlement, which keeps transactions onshore and visible to regulators. Still, the design invites a cliff-edge problem in 2030, when the exemption expires and investors may rush to realize gains beforehand, creating a temporary surge followed by a lull unless the transition is carefully managed.
The Legal Mechanics: Amending the Income Tax Act 2023
The association's proposal is not a vague appeal but a specific legislative request: amend the relevant provisions of the Income Tax Act 2023 so that capital gains from eligible transactions are tax-exempt, provided those transactions are carried out through stock exchanges and settled through the designated central depository system. This conditionality is significant because it channels the benefit toward transparent, on-exchange activity and away from off-market block transfers that are harder to monitor and easier to use for tax avoidance. The design effectively rewards market intermediation and formal settlement infrastructure.
Bangladesh's Income Tax Act 2023 consolidated and modernized a patchwork of earlier legislation, and its capital gains provisions have been a source of interpretive friction for brokers and investors alike. By anchoring the exemption to exchange execution and depository settlement, the proposal leverages existing digital infrastructure to create an auditable trail, reducing the administrative burden on the National Board of Revenue. The approach mirrors practices in several emerging markets where tax incentives are conditioned on using regulated market plumbing, ensuring that the fiscal cost buys genuine market development rather than paper transactions.
Central Counterparty Bangladesh Limited and the 2030 Sunset
The 2030 sunset is the proposal's most technically grounded element. Central Counterparty Bangladesh Limited, once fully operational, is expected to centralize clearing and settlement, which in turn makes the calculation of capital gains and the determination of tax liabilities far more tractable. A central counterparty sits between buyers and sellers, guaranteeing trades and maintaining records that can be queried for cost basis and proceeds. In effect, the exemption window buys time for the infrastructure that will eventually make capital gains taxation administratively cheap to enforce.
This sequencing is economically elegant. Rather than asking the revenue authority to build complex cost-basis tracking from scratch, the proposal defers taxation until the market's own plumbing can supply the data. The risk is that the 2030 deadline slips, as infrastructure timelines frequently do, leaving the exemption in place longer than intended or forcing an abrupt reinstatement. The association's implicit bet is that a functioning central counterparty will make the tax politically and administratively palatable by the end of the decade, at which point the exemption can lapse without destabilizing the market.
Why Sponsors and Directors Are Excluded
The association's decision to support keeping existing tax arrangements for sponsors, directors, and institutional investors is a deliberate credibility move. These are the insiders closest to material non-public information, and exempting their gains would invite accusations that the proposal is self-serving. By drawing the line at retail and foreign portfolio participants, the brokers' body positions the request as a market-wide development measure rather than a concession to powerful shareholders. It also aligns with broader regulatory efforts to tighten disclosure and insider trading enforcement.
This distinction has precedent in other markets, where preferential capital gains treatment is often extended to long-term retail holders and foreign institutional investors while insiders face standard rates. The logic is that insiders already possess informational advantages and do not need tax incentives to participate, whereas retail and foreign investors face higher information costs and greater sensitivity to after-tax returns. Whether the National Board of Revenue accepts this segmentation will depend on its assessment of revenue risk and the political optics of granting relief to any investor class while tightening enforcement elsewhere.
Market Liquidity and the Confidence Channel
Liquidity is the lifeblood of any equity market, and Bangladesh's exchange has grappled with thin volumes that amplify price swings and raise the cost of executing large orders. The association's argument that a capital gains exemption would improve liquidity rests on a straightforward mechanism: lower after-tax transaction costs attract more participants, and a broader participant base narrows bid-ask spreads and deepens the order book. In markets where retail investors dominate turnover, tax treatment is a particularly potent lever because retail behavior is highly sensitive to perceived net returns and to the psychological appeal of tax-free gains.
The confidence channel is subtler but arguably more important. Investor confidence in Bangladesh's capital market has been tested by episodes of volatility, regulatory uncertainty, and concerns about governance at listed companies. A credible, time-bound tax exemption signals that policymakers are willing to use fiscal tools to support the market, which can shift expectations about future policy and encourage investors to commit capital rather than wait on the sidelines. Expectations, once anchored positively, can become self-fulfilling as inflows beget liquidity and liquidity begets further inflows.
Encouraging Long-Term Investment
There is an apparent paradox in using a tax exemption to encourage long-term investment, since exempting gains reduces the tax penalty on short-term trading as well. The association's framing resolves this by emphasizing reinvestment of profits and the productive use of domestic savings, suggesting that the target is not holding periods per se but the overall depth of equity participation. In a market where many savers default to fixed deposits and savings certificates, any reduction in the friction of equity investing can shift the allocation toward productive capital, even if some of that capital trades actively.
Long-term investment is more likely to emerge from a stable, liquid market than from a tax code that penalizes exit. Investors hold longer when they are confident they can sell at a fair price when needed, which is precisely what liquidity provides. The exemption, by reducing the cost of entry and exit, may paradoxically support longer holding periods by making equity investment feel less like a trap. The association's emphasis on reinvestment also points to compounding effects that accrue over time, aligning with the government's broader development objectives.
Equity Financing for Listed Companies
For listed companies, the ultimate benefit of a deeper investor base is a lower cost of equity capital. When more investors are willing to participate, issuers can raise funds at more favorable valuations, reducing reliance on debt and strengthening balance sheets. The association explicitly links the tax proposal to this outcome, arguing that a favorable regime would expand financing opportunities for listed companies. In an economy where bank credit is often constrained and expensive, a vibrant equity market offers an alternative channel for corporate investment and growth.
The equity financing argument also connects to the government's capital market development plans, which have long sought to broaden the market's role in mobilizing savings for productive investment. A tax exemption is a relatively blunt instrument, but it can be an effective catalyst when combined with other reforms such as improved disclosure, stronger enforcement, and better market infrastructure. The association's proposal should therefore be read as one component of a broader agenda rather than a standalone fix, and its impact will depend on complementary measures that address governance and transparency.
We Also Published
- 01
- 02
- 03
- 04
Regional Comparisons and Competitive Positioning
Bangladesh's proposal should be read against a regional backdrop in which several emerging and frontier markets have used capital gains tax policy as a tool of market development. Vietnam, for instance, has long applied a modest flat rate on securities transfers, while Sri Lanka has periodically adjusted its capital gains treatment to stimulate investment. India's regime has evolved toward differentiated holding-period rates, with long-term gains often taxed more lightly than short-term gains. Each of these approaches reflects a different balance between revenue needs and market development objectives, and Bangladesh's proposed exemption is among the more generous in the region.
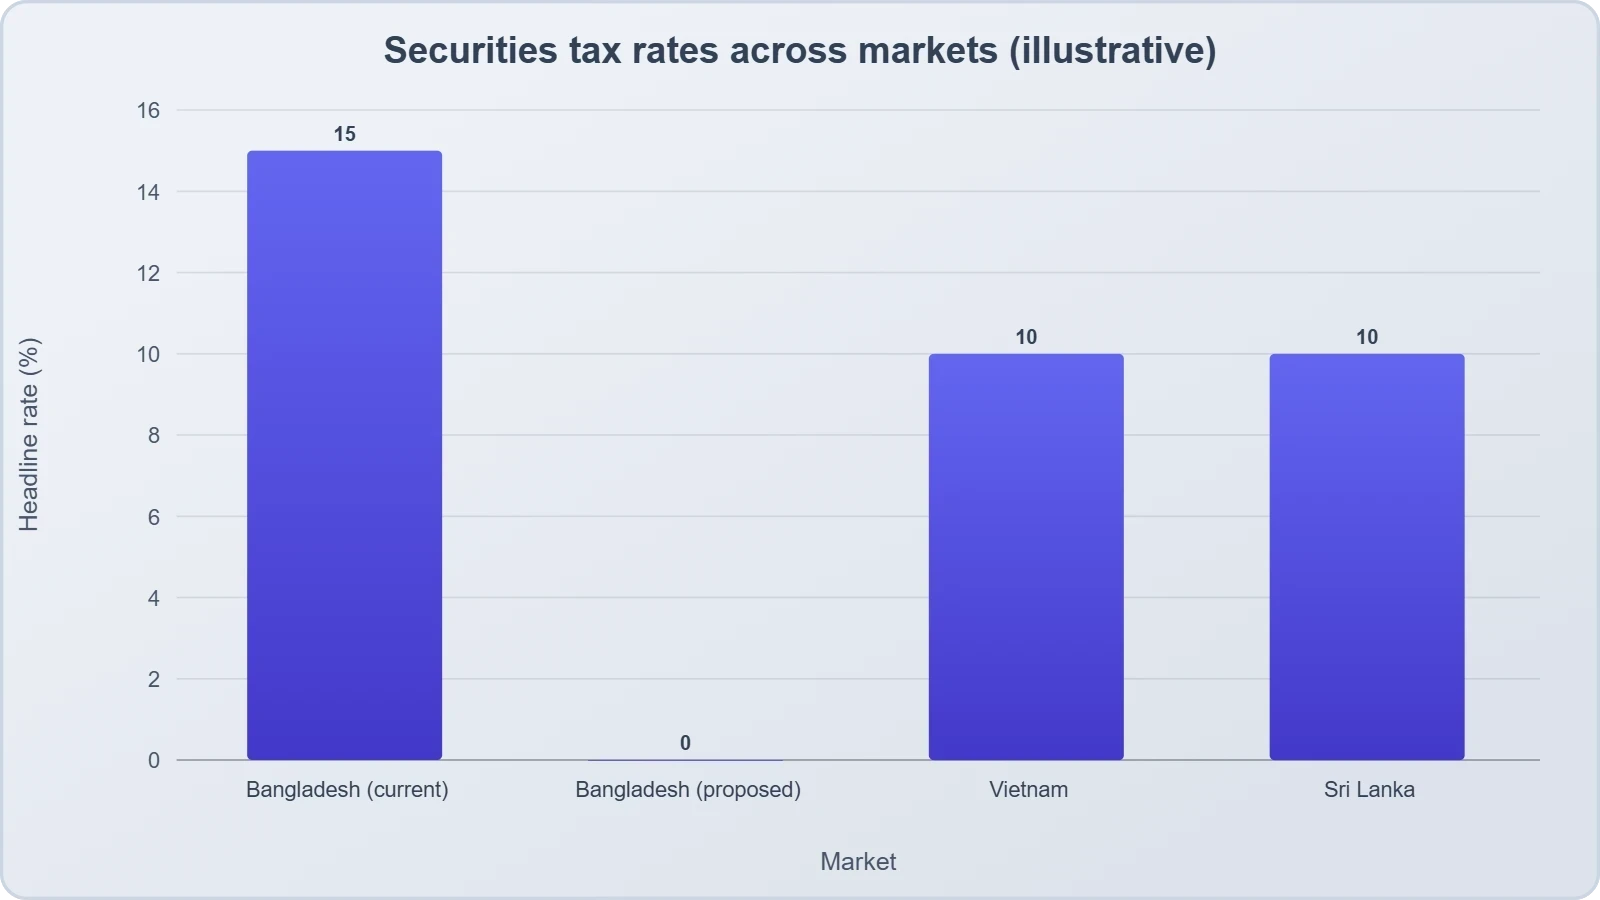
The competitive dimension is real but should not be overstated. Foreign portfolio allocators weigh tax treatment alongside liquidity, currency stability, governance quality, and index inclusion. A tax exemption can tip a marginal allocation decision, but it cannot compensate for persistent illiquidity or weak disclosure. The association's proposal is therefore best understood as removing a friction rather than creating an advantage, and its effectiveness will depend on whether other frictions are addressed in parallel. The 2030 horizon gives policymakers time to sequence reforms and to build the infrastructure that makes the exemption sustainable.
Lessons from Comparable Markets
Comparable markets offer instructive lessons on both the benefits and the pitfalls of capital gains holidays. Jurisdictions that have implemented time-bound exemptions often report initial surges in trading volume and retail participation, followed by normalization as the novelty fades. The durability of the effect depends on whether the exemption is accompanied by improvements in market infrastructure and governance. Where it is not, the volume gains tend to be transient, and the market reverts to its prior equilibrium once the incentive is removed or its novelty wears off.
The design of the sunset matters enormously. A well-communicated, credible expiry date allows investors to plan and reduces the risk of a disruptive cliff. A poorly communicated or repeatedly extended exemption can create uncertainty and encourage gaming. Bangladesh's proposal, by tying the sunset to the operational readiness of Central Counterparty Bangladesh Limited, offers a technically grounded rationale for the deadline, which may enhance its credibility with both investors and revenue authorities. The key will be transparent milestones and regular public reporting on the infrastructure's progress.
Risks of Tax Arbitrage and Distortion
Any tax preference creates incentives for arbitrage, and a capital gains exemption is no exception. Investors may restructure holdings to convert taxable income into exempt gains, or route transactions through exempt channels even when other structures would be more efficient. The association's conditionality on exchange execution and central depository settlement mitigates some of this risk by keeping transactions within the regulated perimeter, but it does not eliminate it entirely. Revenue authorities will need robust monitoring and clear anti-avoidance rules to prevent the exemption from becoming a loophole.
Distortion also arises from the differential treatment of investor classes. Exempting retail and foreign investors while taxing sponsors and directors creates a segmented market in which the same security carries different after-tax values for different holders. This can affect pricing and liquidity in subtle ways, and it may complicate the enforcement of insider trading rules if insiders have incentives to shift holdings to exempt entities. The association's segmentation is defensible on equity grounds, but it requires careful legal drafting to avoid unintended consequences and to maintain the integrity of the tax base.
Implementation Pathways and Policy Sequencing
Translating the association's proposal into law requires navigating a complex institutional landscape. The Finance Ministry must weigh the fiscal implications, the National Board of Revenue must assess revenue risk and design anti-avoidance provisions, and the Bangladesh Securities and Exchange Commission must ensure that market integrity is preserved. The Income Tax Act 2023 provides the legislative vehicle, but amendments must be drafted carefully to define eligible transactions, specify the role of the central depository, and establish the sunset mechanism. Each of these elements carries technical and political implications that will shape the final outcome.
The sequencing of reforms is equally important. A tax exemption introduced before the market infrastructure is ready could create administrative chaos, with disputes over cost basis and eligibility. Conversely, waiting for perfect infrastructure could delay benefits indefinitely. The association's proposal implicitly favors a phased approach: introduce the exemption now, build the central counterparty by 2030, and then transition to a simplified taxation regime. This sequencing allows the market to capture near-term benefits while preparing for a more sustainable long-term framework.
Administrative Feasibility for the NBR
For the National Board of Revenue, the central question is whether the exemption can be administered without eroding the tax base or creating opportunities for abuse. The conditionality on exchange execution and central depository settlement is helpful because it creates a verifiable record of transactions, but the NBR will still need to define what constitutes an eligible transaction and how to handle edge cases such as corporate actions, mergers, and off-market transfers. Clear rules and robust systems will be essential to prevent disputes and to maintain confidence in the regime.
The NBR's capacity to monitor and enforce will also determine the credibility of the sunset. If the exemption is seen as permanent in practice, investors may price it into valuations, and its removal in 2030 could trigger a sharp adjustment. Transparent communication about the expiry and regular reporting on the central counterparty's progress can help manage expectations. The NBR's willingness to commit to a time-bound exemption will depend on its confidence that the infrastructure will be ready and that the transition can be managed smoothly.
What Investors Should Watch
Investors evaluating the proposal should monitor several indicators: the Finance Ministry's public response, the drafting of amendments to the Income Tax Act 2023, the progress of Central Counterparty Bangladesh Limited, and the NBR's statements on revenue impact. Each of these will signal the likelihood and timing of implementation. Investors should also watch for complementary reforms in disclosure, enforcement, and market infrastructure, since the exemption's effectiveness depends on a broader ecosystem of trust and transparency. A tax break alone is unlikely to transform the market without these supporting measures.
The proposal's fate will also be shaped by political dynamics. The government has articulated ambitions to develop the capital market, and a tax exemption is a visible way to demonstrate commitment. However, fiscal pressures and competing priorities may limit the appetite for revenue foregone. The association's strategy of engaging multiple stakeholders, including the Prime Minister's Special Assistant and the BSEC Chairman, suggests a coordinated advocacy effort. Whether that effort succeeds will depend on the persuasiveness of the economic case and the government's willingness to prioritize market development over short-term revenue.
Strategic Implications for Bangladesh's Capital Market
The proposal's significance extends beyond the immediate question of tax rates. It reflects a broader strategic debate about the role of capital markets in Bangladesh's development trajectory. As the economy grows and savings accumulate, the efficient allocation of capital becomes increasingly important. A vibrant equity market can channel savings into productive investment, provide an alternative to bank credit, and offer citizens a stake in the country's growth. The tax exemption is one lever among many, but it signals a willingness to use fiscal policy in service of market development.
The association's emphasis on restoring investor confidence is particularly telling. Confidence is a fragile commodity, easily damaged by volatility and governance failures, and difficult to rebuild. A credible tax reform can help, but it cannot substitute for fundamental improvements in disclosure, enforcement, and market infrastructure. The proposal should therefore be evaluated as part of a package, and its success will depend on whether it is accompanied by the institutional reforms that make markets trustworthy. Tax policy is a catalyst, not a cure.
Balancing Revenue and Growth
The revenue-versus-growth trade-off is a perennial challenge for developing economies, and Bangladesh is no exception. Capital gains tax collections are relatively small, which lowers the fiscal cost of the exemption, but the principle of base erosion matters. The government must weigh the immediate revenue loss against the potential for dynamic gains from a deeper market. The association's proposal offers a time-bound framework that limits the fiscal exposure while allowing the market to develop, which is a pragmatic compromise between competing objectives.
The broader fiscal context also matters. Bangladesh faces significant spending needs in infrastructure, education, and social protection, and every tax exemption competes with those priorities. The case for the capital gains exemption rests on the argument that it will generate more revenue over time by expanding the market and improving compliance. That argument is plausible but not guaranteed, and the government will need to monitor outcomes and adjust policy if the expected benefits fail to materialize. Evidence-based policymaking will be essential to ensure that the exemption delivers value for the public purse.
Signals for Domestic and Foreign Investors
For domestic investors, the proposal signals that the government is attentive to their concerns and willing to use tax policy to support the market. For foreign investors, it signals openness and a desire to attract long-term capital. Both signals are valuable, but they must be backed by credible implementation. Investors have seen many proposals come and go, and they will judge the government by its actions rather than its words. The speed and transparency of the legislative process will be an important test of credibility.
The proposal also has implications for the broader investment climate. A government that responds constructively to market proposals and implements reforms transparently is more likely to attract investment across sectors. Conversely, a government that ignores or delays such proposals may signal a lack of commitment to market development. The association's engagement with multiple stakeholders suggests a sophisticated advocacy strategy, and the government's response will be watched closely by both domestic and international observers. The outcome will shape perceptions of Bangladesh's investment climate for years to come.
Conclusion: A Test of Policy Credibility
The DSE Brokers Association's proposal is a well-structured, technically grounded request that deserves serious consideration. By tying the exemption to exchange execution, central depository settlement, and a 2030 sunset aligned with the operational readiness of Central Counterparty Bangladesh Limited, the association has addressed many of the standard objections to tax holidays. The proposal's emphasis on retail and foreign investors, while leaving sponsors and directors under existing arrangements, further strengthens its credibility. Whether the government accepts it will depend on its assessment of fiscal risk and its commitment to capital market development.
The broader lesson is that tax policy is most effective when it is part of a coherent strategy. A capital gains exemption can catalyze market development, but it cannot substitute for the institutional reforms that make markets trustworthy. Bangladesh's capital market has significant potential, and the proposal offers a pragmatic way to unlock it. The coming months will reveal whether policymakers are willing to act on the association's recommendations and whether the market responds with the confidence and liquidity that the proposal envisions.
From our network :
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
RESOURCES
- Resources will be updated soon.
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments