Bangladesh's passenger car market is contracting under the combined weight of a depreciating currency, elevated import costs, and softening household demand, a slowdown that has now persisted for three consecutive years and shows few signs of reversing in the near term. The Bangladesh Reconditioned Vehicles Importers and Dealers Association (BARVIDA), which represents the country's reconditioned-car trade, has publicly confirmed that the sector — valued at roughly Tk 20,000 crore — is being squeezed from both directions: the cost of bringing vehicles into the country has climbed sharply, while the purchasing power of the middle-income buyers who form the market's backbone has eroded under persistent inflation.
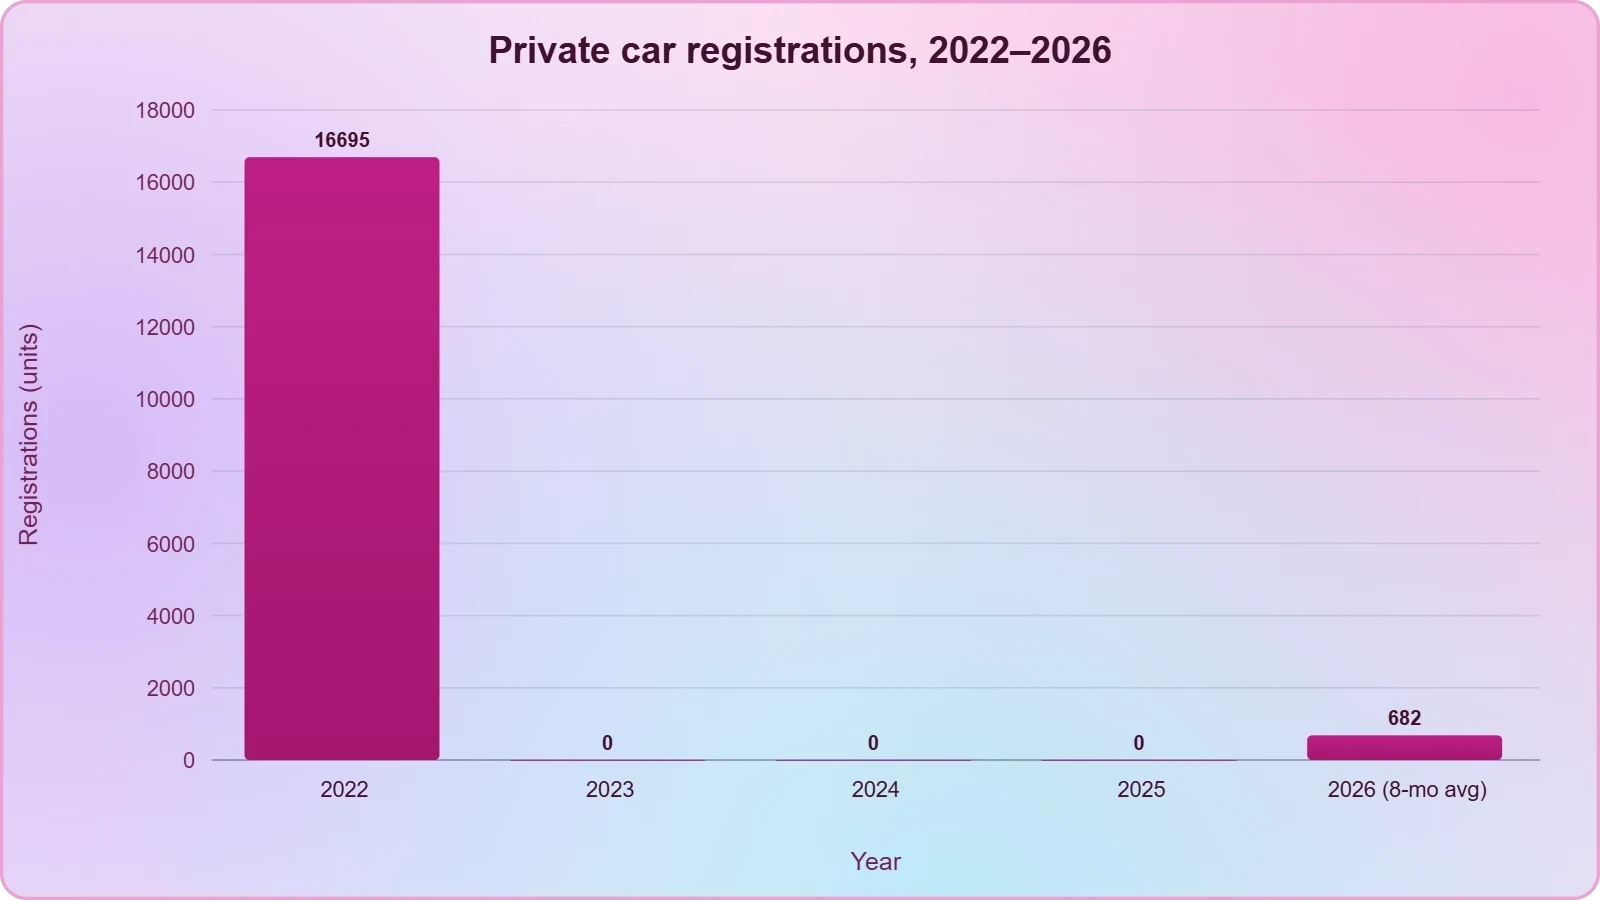
The mechanics of the decline are unusually clear. Currency depreciation has raised the taka cost of every vehicle sourced from Japan, duties and taxes have compounded the burden, and Japanese auction prices have themselves risen, creating a cost stack that importers can neither absorb nor fully pass on. Government registration figures trace the consequence with grim precision: private passenger-car registrations have fallen from 16,695 in 2022 to a projected 8,187 for 2026, a decline of more than half in four years. This analysis examines the structural forces behind that contraction, the fiscal spillovers for the state, and the industry's own response as it prepares to stage the BARVIDA Car Expo 2026 in Dhaka.
What emerges is a case study in how macroeconomic stress transmits through a consumer durable market in a developing economy. The Bangladeshi car market is not simply experiencing a cyclical dip; it is being reshaped by exchange-rate dynamics, tax policy, and shifting affordability thresholds that together determine who can still participate. Understanding this episode offers lessons that extend well beyond South Asia's automotive trade, touching on import-dependent consumption, revenue sensitivity to trade volumes, and the limits of promotional remedies when the underlying arithmetic of affordability has changed.
On This Page
TL;DR Bangladesh's reconditioned car market, worth approximately Tk 20,000 crore, is contracting sharply as taka depreciation has driven import costs up roughly 30 percent over two years, pushing entry-level car prices from Tk 16 lakh to about Tk 24 lakh. Private passenger-car registrations have fallen for three consecutive years, from 16,695 in 2022 to a projected 8,187 in 2026, while reconditioned imports slipped to 21,337 units in FY2024-25 and customs revenue from the segment fell more than 6 percent to Tk 3,864 crore. BARVIDA is responding with a three-day expo in Dhaka from November 5 to 7, showcasing Japanese models and marking 50 years of Japanese cars in Bangladesh.
The Anatomy of a Three-Year Market Contraction
The Bangladeshi passenger car market's decline is best understood not as a single shock but as a compounding sequence of pressures that have tightened year after year. Registration data from the government provides the clearest longitudinal view: 16,695 private passenger cars were registered in 2022, a figure that collapsed to 10,784 in 2023 and continued sliding to 10,499 in 2024 and 9,387 in 2025. The January-to-August 2026 window recorded just 5,458 registrations, averaging roughly 682 per month, which annualizes to approximately 8,187 units — nearly 13 percent below the prior year and less than half the 2022 peak.
This trajectory matters because it inverts the normal pattern of motorization in a growing economy. Emerging markets typically see vehicle penetration rise as incomes expand and middle classes form; Bangladesh is instead experiencing de-motorization among precisely the demographic that should be driving demand. The reconditioned-vehicle segment, which serves buyers seeking quality Japanese models at below-new prices, has been hit hardest because its cost structure is almost entirely import-dependent. Every unit sold carries embedded exposure to the yen-taka and dollar-taka exchange rates, Japanese auction clearing prices, and the layered duty structure that governs vehicle imports.
Registration Data and the Pace of Decline
The registration statistics reveal a market that has found a new, lower equilibrium rather than a temporary trough. The monthly average of 682 units during the first eight months of 2026 represents a fraction of the volumes the dealer network was built to serve, implying significant excess capacity across showrooms, workshops, and financing channels. When a market operates at roughly half its peak volume for multiple years, the strain propagates through the entire ecosystem — dealers, importers, banks offering auto loans, insurers, and the government's own revenue machinery.
Analysts watching the Bangladesh automobile market note that the decline has been remarkably steady rather than volatile, which suggests structural rather than sentiment-driven causes. Consumers have not simply postponed purchases in anticipation of better prices; they have been priced out of the segment altogether. The absence of a sharp rebound after each successive year of decline reinforces the conclusion that affordability, not confidence, is the binding constraint on demand in this market.
Why the Reconditioned Segment Bears the Brunt
Reconditioned vehicles occupy a distinctive position in Bangladesh's automotive landscape: they offer Japanese build quality and reliability at prices below new-car levels, making them the default choice for aspirational middle-income households. That positioning, however, makes the segment acutely vulnerable to exchange-rate movements because the entire product is imported and priced in foreign currency before duties are applied. When the taka weakens, the reconditioned segment's price advantage over new vehicles narrows or disappears, and its customer base — the most price-sensitive tier of car buyers — retreats first.
Importers report that Japanese auction prices have risen independently of currency effects, adding a second layer of cost inflation that cannot be hedged away. The combination means dealers must either absorb margin compression or pass costs to buyers who are already at their affordability ceiling. Most have chosen the latter, which explains why volumes have fallen even as the underlying desire for personal mobility in Bangladesh remains strong. The market has not lost its customers; it has lost their ability to pay.
Currency Depreciation and the Arithmetic of Affordability
At the heart of the Bangladesh car market slowdown lies a straightforward but brutal calculation: the taka has depreciated substantially against the US dollar, and because vehicles are sourced and settled in foreign currency, every percentage point of depreciation translates directly into a higher local price. BARVIDA's leadership estimates that import costs have risen by approximately 30 percent over the past two years, with the dollar climbing nearly 40 percent at one point during that period. For a market where entry-level pricing defines accessibility, such movements are transformative rather than marginal.
The association's own illustration captures the scale of the shift: an entry-level car that once cost Tk 16 lakh now commands around Tk 24 lakh, an increase of 50 percent at the retail level. That figure exceeds the raw currency movement because duties and taxes are levied on the already-inflated import value, creating a multiplier effect. Each layer of the cost stack — vehicle price, freight, insurance, customs duty, supplementary duty, VAT, and registration charges — is calculated on a base that has itself grown by a third, so the final price rises faster than any single component.
The Cost Stack Behind a Tk 24 Lakh Price Tag
Understanding why a car's price can rise by half when the currency falls by a third requires tracing the sequential application of charges. The import value in dollars is converted at the prevailing exchange rate, then customs duty is applied, followed by supplementary duty and value-added tax, each computed on cumulative assessable value rather than the original invoice price. Registration fees and other levies add further increments. The result is that currency depreciation is effectively amplified by the tax structure, and the amplification factor grows with the duty tier of the vehicle.
This structure explains why importers emphasize that duties and taxes, not dealer margins, are the dominant driver of retail prices. It also explains why the government faces a policy dilemma: reducing duties to stimulate demand would sacrifice revenue precisely when import volumes have already shrunk the tax base. The fiscal and consumer interests have diverged, and no adjustment can satisfy both simultaneously without external relief on the currency side.
Inflation and the Middle-Income Squeeze
Currency effects alone would be painful; combined with generalized inflation, they become prohibitive for the middle-income households that constitute the core of Bangladesh's private car demand. When food, fuel, rent, and education costs are all rising, the car is the first major expenditure to be deferred or abandoned. Households that might have stretched to purchase a vehicle at Tk 16 lakh find the arithmetic at Tk 24 lakh simply unworkable, particularly when financing costs have also risen in a higher-rate environment.
The affordability threshold has shifted in a way that excludes a substantial cohort of former buyers. This is not a matter of consumer preference or changing tastes; it is a hard budget constraint. Dealers report that inquiries continue but conversions have collapsed, a pattern consistent with a market where aspiration persists while capacity to transact has evaporated. The middle-income squeeze is therefore both the proximate cause of the current slump and the reason recovery will be slow even if currency conditions stabilize.
Import Volumes, Auction Prices, and the Japanese Supply Chain
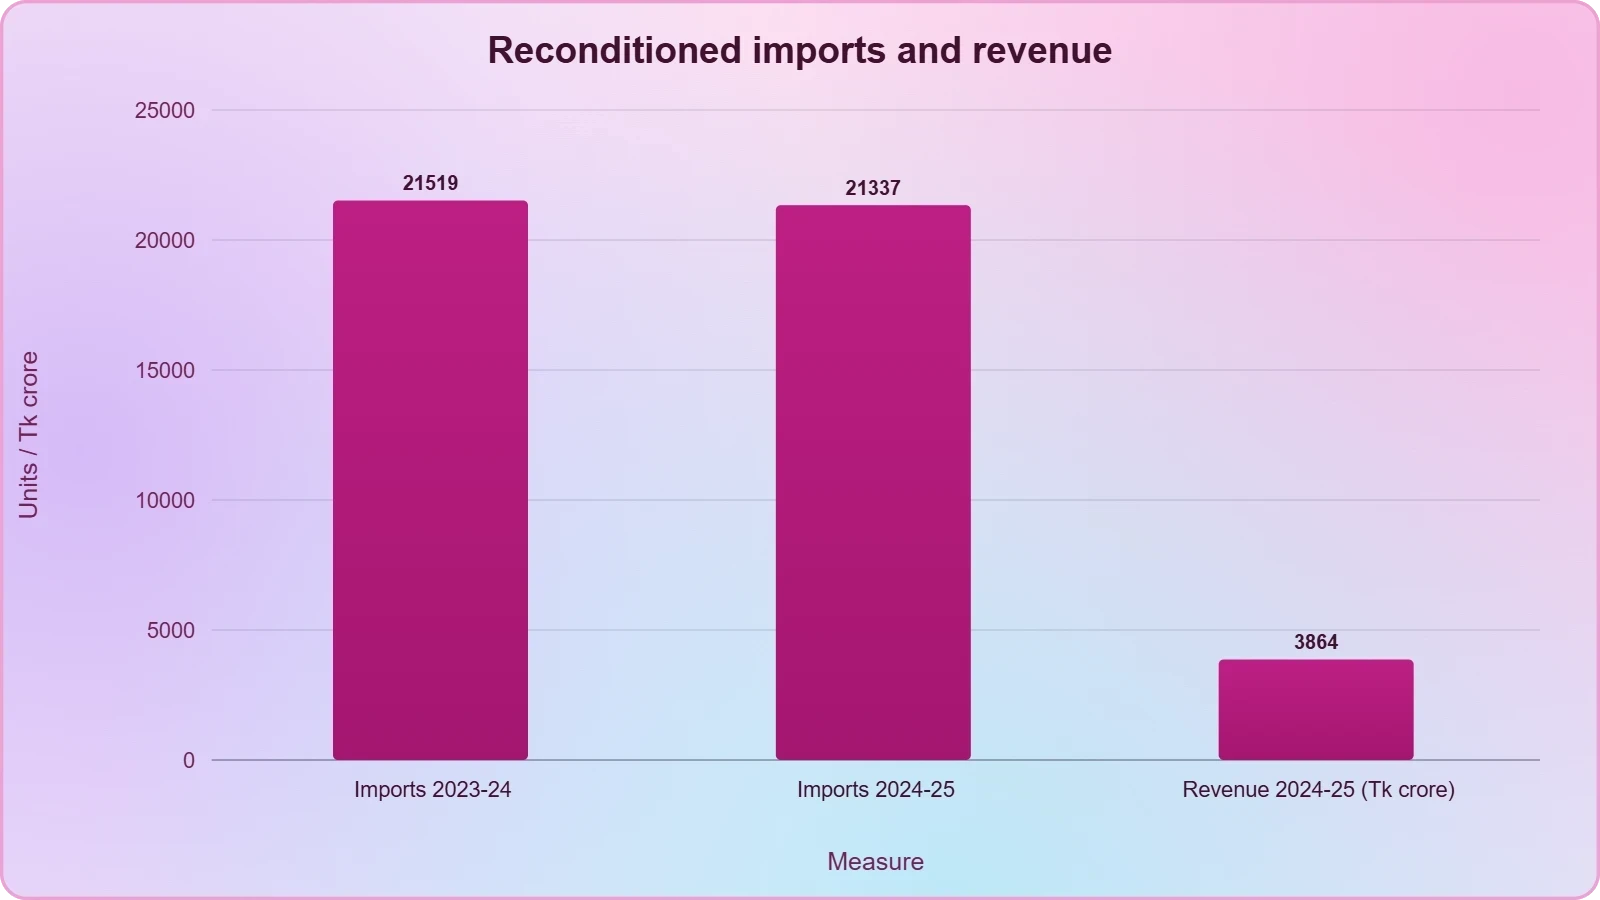
Bangladesh's reconditioned car trade is structurally tied to Japan, and developments in Japanese auction houses transmit directly to Dhaka showrooms. The country imported 21,337 reconditioned vehicles in the 2024-25 fiscal year, a modest decline from 21,519 the year before, but the stability in unit counts masks significant deterioration in value and profitability. Importers report that auction prices in Japan have climbed, meaning each unit now costs more to acquire even before shipping, insurance, and currency conversion are applied.
The Japanese connection is not incidental to the story; it is the defining feature of Bangladesh's vehicle supply model. Reconditioned Japanese cars have dominated the market for five decades, prized for reliability, parts availability, and resale value. The upcoming expo's special exhibition marking 50 years of Japanese cars in Bangladesh acknowledges this relationship explicitly. Yet the same dependence that built the market now transmits Japanese price inflation and yen dynamics directly into Bangladeshi affordability, leaving importers with little flexibility to source cheaper alternatives at comparable quality.
Reading the Import and Revenue Numbers
The fiscal consequences of declining imports are already visible. Reconditioned-car imports generated Tk 3,864 crore in revenue during the 2024-25 fiscal year, more than 6 percent below the previous year's collection. This decline occurred even though unit volumes fell only marginally, which indicates that the revenue loss stems from a combination of lower volumes and changes in the mix of vehicles imported — buyers and importers shifting toward smaller, lower-duty models as affordability tightened.
For a government already managing fiscal pressures, the erosion of automotive import revenue is unwelcome. Vehicles are among the most heavily taxed consumer goods in Bangladesh, and the reconditioned segment has historically been a reliable contributor. The irony is that the tax structure designed to capture revenue from vehicle imports has, at current price levels, suppressed the very volumes that generate that revenue. Fiscal policy and market health are locked in a feedback loop that neither side can easily break.
Japanese Auction Dynamics and Cost Pass-Through
Japanese used-vehicle auctions operate on a competitive bidding model in which Bangladeshi importers compete with buyers from across Asia, Africa, and the Pacific. When demand from other markets rises or supply tightens, clearing prices increase for all participants regardless of their own domestic conditions. Bangladeshi importers therefore face a cost floor set externally, which they cannot influence and can only partially offset through vehicle selection or timing of purchases.
This external cost pressure compounds the currency problem in a way that makes the Bangladesh car market's recovery dependent on factors entirely outside national control. Even a stable taka would not restore affordability if Japanese auction prices continue climbing. The practical implication is that importers must increasingly compete on service, financing facilitation, and after-sales support rather than price, since price leadership is no longer available to anyone in the trade.
- 01
- 02
- 03
- 04
Fiscal Spillovers and the Revenue Dilemma
The decline in vehicle imports carries consequences that extend well beyond the automotive sector. Bangladesh's tax structure relies heavily on import-related duties, and the reconditioned car trade has historically been a meaningful contributor to customs revenue. When volumes fall and the mix shifts toward cheaper vehicles, the state collects less at precisely the moment when economic weakness is straining other revenue streams. The Tk 3,864 crore collected in FY2024-25, down more than 6 percent, illustrates how quickly a healthy revenue line can become a fiscal concern.
Policymakers face a genuine dilemma. Lowering duties could revive volumes and, over time, restore revenue through higher turnover, but the short-term fiscal cost would be immediate and politically difficult. Maintaining current rates protects revenue per unit but accelerates the volume decline, ultimately eroding the base. The experience of other import-dependent emerging markets suggests that revenue-maximizing duty rates exist and that Bangladesh may have passed the peak of its automotive tax curve, but adjusting rates downward requires fiscal space that is currently scarce.
Registration Trends as a Leading Indicator
Registration data functions as a real-time barometer of both consumer capacity and government revenue potential. Each private car registration triggers a cascade of fees and taxes, from import duties already paid to registration charges, road taxes, and annual renewals. When registrations fall by half over four years, the cumulative revenue loss across the vehicle lifecycle is substantial, extending far beyond the initial import transaction into fuel taxation, insurance premiums, and service sector activity.
The three-year consecutive decline in registrations is therefore a signal that should command policy attention beyond the automotive ministry. It indicates weakening household balance sheets, reduced confidence in durable consumption, and a narrowing of the formal economy's consumer base. Analysts tracking the Bangladesh automobile market treat registration trends as a proxy for middle-class economic health, and the current trajectory suggests that the pressures affecting car buyers are broad rather than confined to one product category.
We Also Published
The BARVIDA Car Expo 2026 and Industry Response
Faced with a market that has contracted for three consecutive years, the industry's trade association has chosen visibility and direct engagement as its response. BARVIDA will host a three-day car expo at the International Convention City Bashundhara in Dhaka from November 5 to 7, 2026, bringing buyers and dealers into direct contact in an environment designed to showcase product quality, technology, and value. The event will display popular Japanese models including the Toyota Prius, Corolla Cross, Harrier, Noah, Voxy, and Alphard, allowing visitors to compare features and prices side by side.
The expo's timing is significant. It follows the release of registration data confirming the depth of the slowdown and precedes the year-end period when dealers typically seek to clear inventory. By eliminating intermediaries and creating a comparison environment, organizers hope to convert latent aspiration into transactions. The event is open from 11am to 8pm daily with no entry fee, a deliberate choice that lowers the barrier for the price-sensitive buyers the industry most needs to reach.
Expo Objectives and the Fiftieth Anniversary Exhibition
Beyond immediate sales, the expo serves a strategic purpose: rebuilding awareness of the quality and reliability that Japanese reconditioned vehicles offer relative to their cost. A special exhibition marking 50 years of Japanese cars in Bangladesh will anchor the event, connecting the current market's heritage to its present challenges. The anniversary is a reminder that the Japanese vehicle trade has survived previous downturns and that its institutional knowledge and dealer networks remain intact even as volumes contract.
The direct-connection model also addresses a practical problem in a slow market: buyers need more information and more confidence before committing to a purchase of Tk 24 lakh or more. Dealers who can demonstrate vehicle condition, service history, and after-sales support in person have a better chance of closing sales than those relying on remote marketing. The expo is therefore as much a trust-building exercise as a promotional one, reflecting the reality that in a constrained market, conversion depends on reassurance.
What the Expo Can and Cannot Achieve
An exhibition can stimulate interest, facilitate comparison, and generate leads, but it cannot alter the underlying arithmetic of affordability. If the taka remains weak, duties remain high, and Japanese auction prices continue rising, the expo's impact will be measured in market share shifts among dealers rather than in aggregate volume growth. The industry's own leaders acknowledge that promotional efforts address demand-side hesitation, not the supply-side cost structure that has driven prices beyond middle-income reach.
This distinction matters for how the expo should be interpreted. It is a rational response to a difficult environment, not a solution to the structural problem. The genuine remedies lie in exchange-rate stability, a rationalization of the duty structure, and a broader economic recovery that restores household purchasing power. Until those conditions materialize, events like the BARVIDA expo serve to keep the market functioning at its reduced level and to preserve the dealer networks that will be needed when conditions eventually improve.
Outlook: When Affordability Returns
The Bangladesh car market's recovery path depends on three variables that must align: exchange-rate stability, moderation in Japanese auction prices, and a restoration of middle-income purchasing power. None of these is within the industry's control, and all three have moved adversely in recent years. The most realistic near-term scenario is continued low-volume operation, with the market stabilizing around the 8,000-unit annual level before any meaningful rebound. A return to the 2022 peak of 16,695 registrations would require a substantial reversal in all three variables simultaneously.
There are, however, reasons for measured optimism. Bangladesh's underlying demand for personal mobility remains intact; the country's middle class has not disappeared but has been temporarily priced out. When affordability improves, deferred purchases could create a release of pent-up demand that benefits the reconditioned segment disproportionately, since it serves buyers moving up from two-wheelers and public transport. The dealer networks, import relationships, and institutional knowledge that BARVIDA represents are precisely the assets needed to capture that recovery when it arrives.
Policy Levers and Their Limits
Duty rationalization is the most direct lever available to policymakers, but its fiscal cost limits its use. A targeted reduction on smaller, fuel-efficient vehicles could revive volumes in the most price-sensitive tier while protecting revenue from higher-value imports. Such an approach would also align with environmental objectives, though Bangladesh's vehicle taxation has historically been driven by revenue rather than emissions considerations. Any adjustment would need to be calibrated carefully to avoid a revenue collapse that outweighs the volume gains.
Exchange-rate management is a broader macroeconomic matter that extends far beyond the automotive sector, and no government can sustainably defend a currency at the expense of reserves. The realistic policy posture is to manage depreciation smoothly rather than reverse it, giving importers and consumers time to adjust. For the industry, this means planning for a prolonged period of high prices and developing financing models, trade-in programs, and service offerings that make ownership viable at current price points.
Lessons for Import-Dependent Consumer Markets
Bangladesh's experience offers a transferable lesson for other import-dependent emerging economies: when a consumer durable's cost is denominated in foreign currency and amplified by layered taxation, exchange-rate movements can transform market access faster than any other variable. Markets that appear robust can contract by half in four years without any change in consumer preference or product quality. The vulnerability is structural, and it resides in the interaction between currency exposure and tax design rather than in demand itself.
The corollary is that resilience requires either domestic production, diversified sourcing, or tax structures that flex with currency conditions. Bangladesh's reconditioned car trade has none of these buffers, which is why it has absorbed the full force of the adjustment. As the market looks toward the BARVIDA expo and beyond, the deeper question is whether the current downturn prompts structural reform or merely awaits a change in external conditions that may be slow to arrive.
From our network :
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
RESOURCES
- Resources will be updated soon.
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments