France has entered a perilous season in which street violence, bond-market anxiety, and pension arithmetic converge into a single, unforgiving narrative of national strain. Riots across Paris, Marseille, Bordeaux, and Limoges have inflicted damage estimated in the hundreds of millions of dollars, with roughly 2,400 arrests and a historic city hall reduced to smoldering rubble.
These disturbances did not erupt from nowhere; they followed weeks of student protests over crumbling schools, teacher shortages, and bleak job prospects for the young.
What distinguishes this moment from earlier French convulsions is the economic backdrop against which it unfolds. Long-term interest rates have climbed, the cost of insuring French sovereign debt against default has surged, and investors increasingly doubt that Paris will summon the political will to restore fiscal credibility.
On This Page
- The Anatomy of a Dual Crisis: Streets and Sovereign Bonds
- The Pension System at the Heart of France's Fiscal Reckoning
- Political Paralysis and the Limits of French Liberalism
- Sovereign Risk, Debt Sustainability, and the Math of Default Insurance
- Comparative Perspective: France Among Rich Nations
- Pathways Forward: Reform, Taxation, and the Cost of Delay
The unrest of 2023 and the Yellow Vest years now look like rehearsals for a deeper structural crisis rooted in pensions, deficits, and an aging population.
This analysis dissects the full meaning of France's predicament, tracing how retirement policy, social spending, and political paralysis have combined to place the republic on what economists call an unsustainable fiscal path.
It examines the mechanics of sovereign risk, the pension system's growing share of national output, and the stark choices France has deferred for decades.
TL;DR France is confronting simultaneous social unrest and sovereign-debt anxiety, with riots causing hundreds of millions in damage and roughly 2,400 arrests. Investors doubt Paris will raise taxes or cut spending, and default-insurance costs have risen sharply. Pension costs consume a growing share of GDP, the retirement age remains among Western Europe's lowest, and political opposition has frozen Macron's planned increase to 64 until after the next election. France's government spending exceeds almost every rich nation's, and its fiscal trajectory lacks the emergency justification of war, recession, or pandemic.
The Anatomy of a Dual Crisis: Streets and Sovereign Bonds
France's current turmoil is unusual because it fuses two crises that normally unfold on separate timelines. Street violence typically burns hot and fades; bond-market skepticism accumulates quietly and then reprices a nation's entire cost of capital. Here, both are active simultaneously, and each amplifies the other's damage.
From Limoges Ashes to Market Signals
The destruction in Limoges carries symbolic weight that transcends property damage. A city hall that survived two world wars, including its clock spire, was gutted by fire, suggesting that institutions once considered untouchable now feel fragile. Roughly 2,400 arrests across multiple cities underscore the scale of state mobilization required.
Yet the more consequential damage may be invisible. Credit default swap spreads on French sovereign debt have widened sharply, signaling that investors are pricing genuine repayment doubt rather than routine volatility. When insurance against government default becomes expensive, a nation's borrowing costs ripple through mortgages, corporate credit, and municipal budgets.
Why Investors Doubt Paris
Investors are not questioning France's ability to pay today; they are questioning its willingness to adjust tomorrow. The fear is that Paris will borrow further to cover higher interest costs rather than raise taxes or cut spending, creating a self-reinforcing debt spiral. Economist Paul Krugman has described this as an unsustainable fiscal path.
Debt is already high relative to GDP, and the government runs large budget deficits without the justification of war, severe recession, or pandemic. That absence of emergency context is precisely what unsettles markets: deficits born of choice rather than catastrophe invite skepticism about discipline and political courage.
We Also Published
The Pension System at the Heart of France's Fiscal Reckoning
No single institution better explains France's fiscal bind than its pension system. Pension costs absorb a growing share of national economic output, and because the population is aging, those costs are projected to grow faster than revenue. The arithmetic is unforgiving, and the politics surrounding it have proven nearly immovable.
An Aging Population Meets an Immovable Retirement Age
In 2023, France's official retirement age stood at 62, and the average actual retirement age was lower than anywhere else in Western Europe. Macron's government planned a gradual increase to 64, still modest by advanced-economy standards, yet opposition from far-right and far-left parties froze the change until after the next election.
Demographics compound the problem relentlessly. As the ratio of retirees to workers rises, pension obligations consume an expanding slice of GDP while the tax base that funds them grows more slowly.
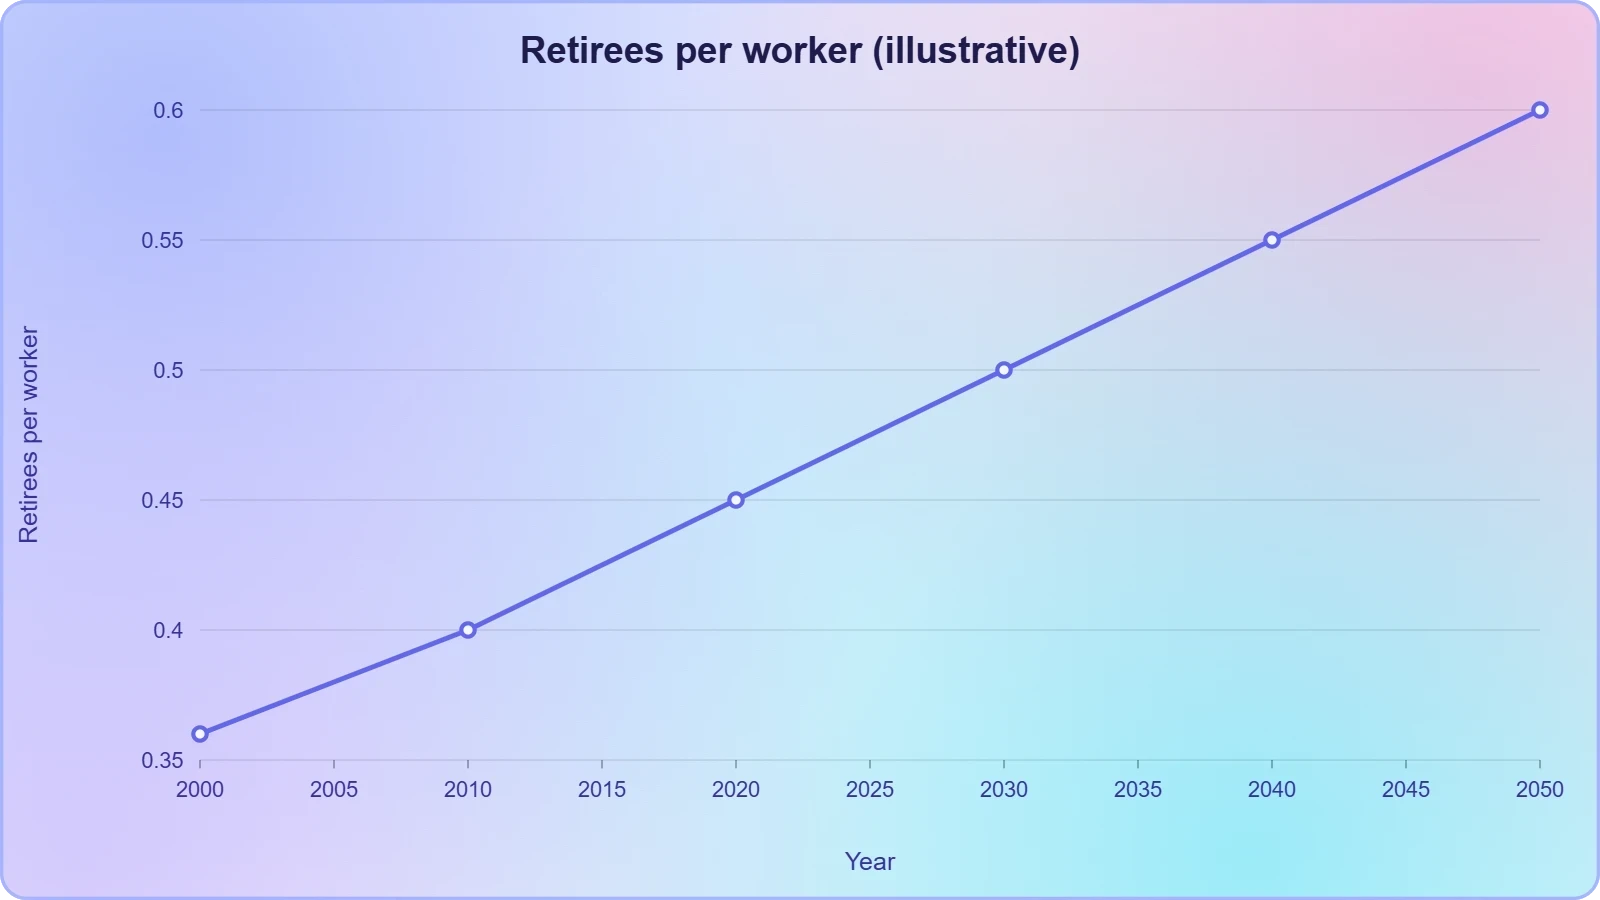
Krugman's diagnosis is blunt: France is on an unsustainable fiscal path, and pension reform is the central lever it has refused to pull.
Social Spending and the Weight of Older Generations
France's government already accounts for a larger share of GDP than almost any other rich country, exceeding even Sweden and Denmark. A substantial portion of that social spending flows to old-age pensions and health care, both heavily weighted toward older citizens rather than the young.
This distributional skew creates a political trap. Any serious deficit reduction must touch pensions or health care, yet those programs benefit the most reliable voters. Raising taxes offers an alternative, but French tax burdens are already elevated, making further increases politically toxic and economically risky.
Political Paralysis and the Limits of French Liberalism
The unrest cannot be separated from France's political configuration, which rewards opposition over governance. Far-right and far-left parties have found common cause in blocking pension reform, while street protests provide pressure that elected officials struggle to withstand. The result is a governing system that identifies necessary reforms but cannot implement them.
Opposition Parties and the Frozen Reform
Macron's pension overhaul was designed as a gradual, negotiated adjustment rather than a shock. Yet the combined weight of opposition parties froze the retirement-age increase until after the next election, converting a fiscal necessity into an electoral football. This deferral signals to markets that France's commitments are contingent on political convenience.
Repeated protest cycles reinforce the pattern. The Yellow Vest demonstrations from 2018 to 2020 and the nationwide unrest of 2023 after a police killing demonstrated that French streets can force policy retreats. Each concession teaches investors that reform promises carry limited credibility.
Student Protests and the Deeper Social Contract
The current unrest began with student protests over poor school conditions, teacher shortages, and weak job prospects, revealing a generational fracture beneath the fiscal debate. Young people facing diminished opportunities are asked to accept longer working lives so that pension obligations to older cohorts can be honored.
That intergenerational bargain is difficult to defend politically and economically. France's social model, celebrated for protecting workers, increasingly transfers resources toward the old while underinvesting in the young. The riots express a frustration that transcends any single policy grievance.
Sovereign Risk, Debt Sustainability, and the Math of Default Insurance
Financial markets translate political doubt into measurable prices, and France's prices have moved decisively. The cost of insuring against a French government default has risen sharply, a signal that investors now assign meaningful probability to fiscal slippage. Understanding this mechanism clarifies why street unrest matters to bondholders.
Reading Credit Default Swaps and Rate Spreads
Credit default swaps function as insurance premiums: buyers pay periodic amounts to protect against non-repayment. When those premiums climb sharply, it indicates that protection sellers demand more compensation for bearing French sovereign risk. Rising long-term rates compound the burden by increasing interest costs on existing debt.
The danger lies in feedback loops. Higher rates raise interest expenses, which widen deficits, which further unsettle investors, which push rates higher still. France's government could borrow more to cover these costs, but that path accelerates the very dynamic markets fear.
The Unsustainable Path in Numbers
Debt sustainability depends on the relationship between interest rates, growth, and primary balances. When the effective interest rate exceeds nominal growth, debt ratios rise even without new borrowing. France's combination of high debt, large deficits, and aging-driven spending growth places it firmly in that vulnerable zone.
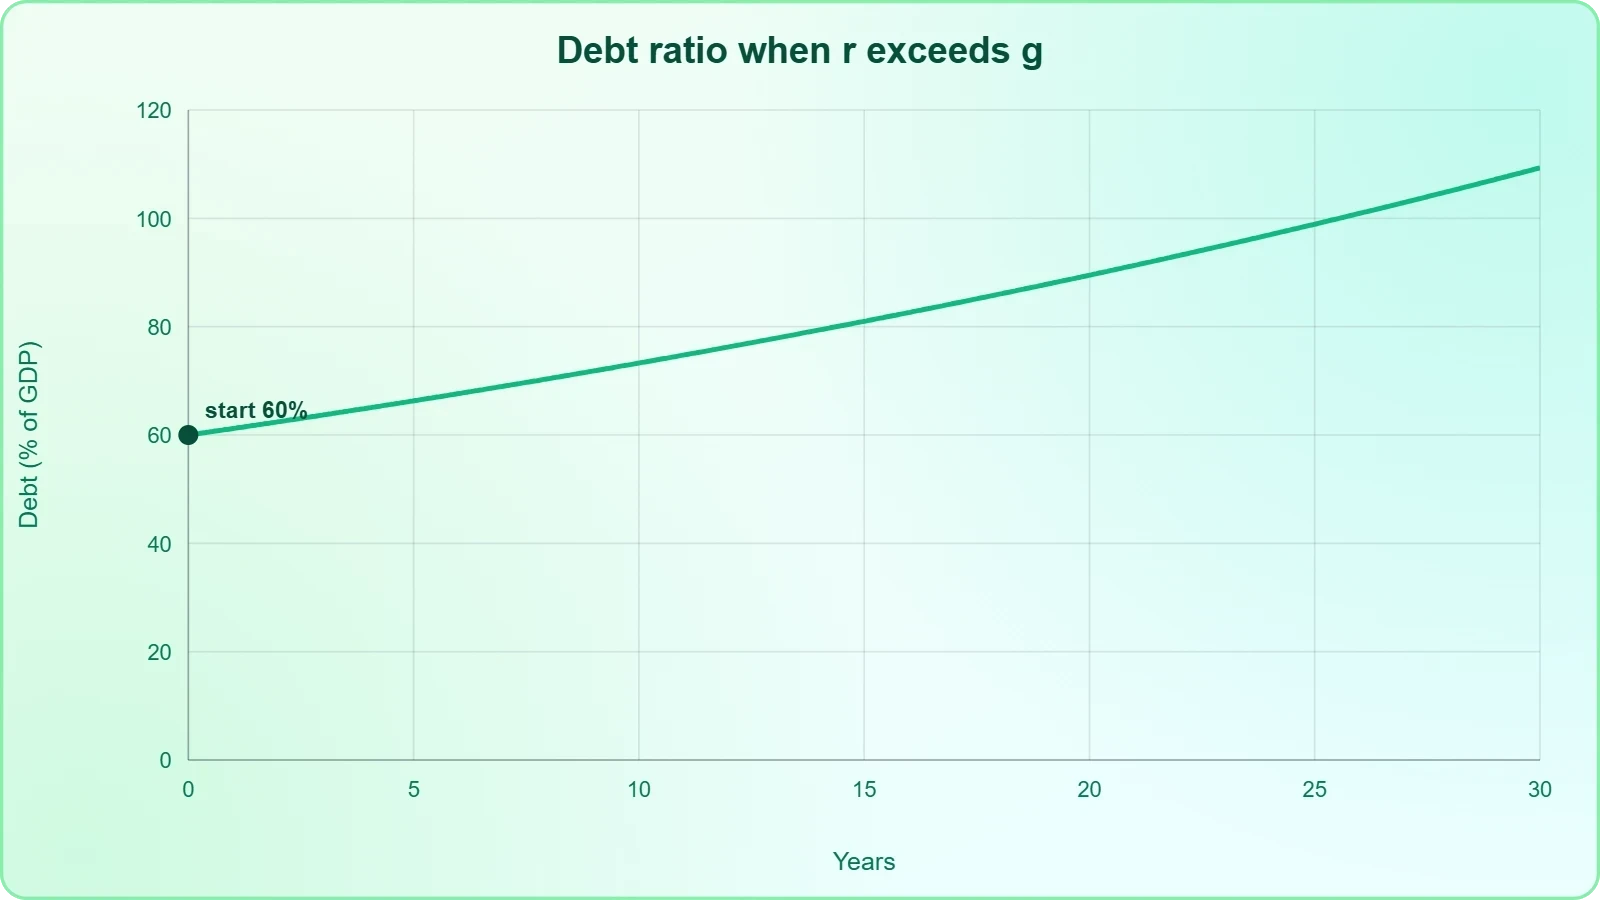
Here ##d## represents the debt-to-GDP ratio, ##r## the effective interest rate, ##g## nominal growth, and ##pb## the primary balance. When ##r > g## and the primary balance is negative, debt expands automatically, requiring painful adjustments simply to stabilize.
Comparative Perspective: France Among Rich Nations
France's fiscal predicament is not unique, but its political response is. Many advanced economies face aging populations and rising debt, yet France stands out for its difficulty in making realistic changes to retirement policy. Comparative analysis reveals both the scale of French spending and the depth of its reform resistance.
- 01
- 02
- 03
- 04
Government Spending and the Nordic Benchmark
France's government accounts for a larger share of GDP than almost any other rich country, surpassing even Sweden and Denmark, which are often cited as high-spending social democracies. That comparison matters because it undercuts the argument that France's model is simply generous rather than structurally unbalanced.
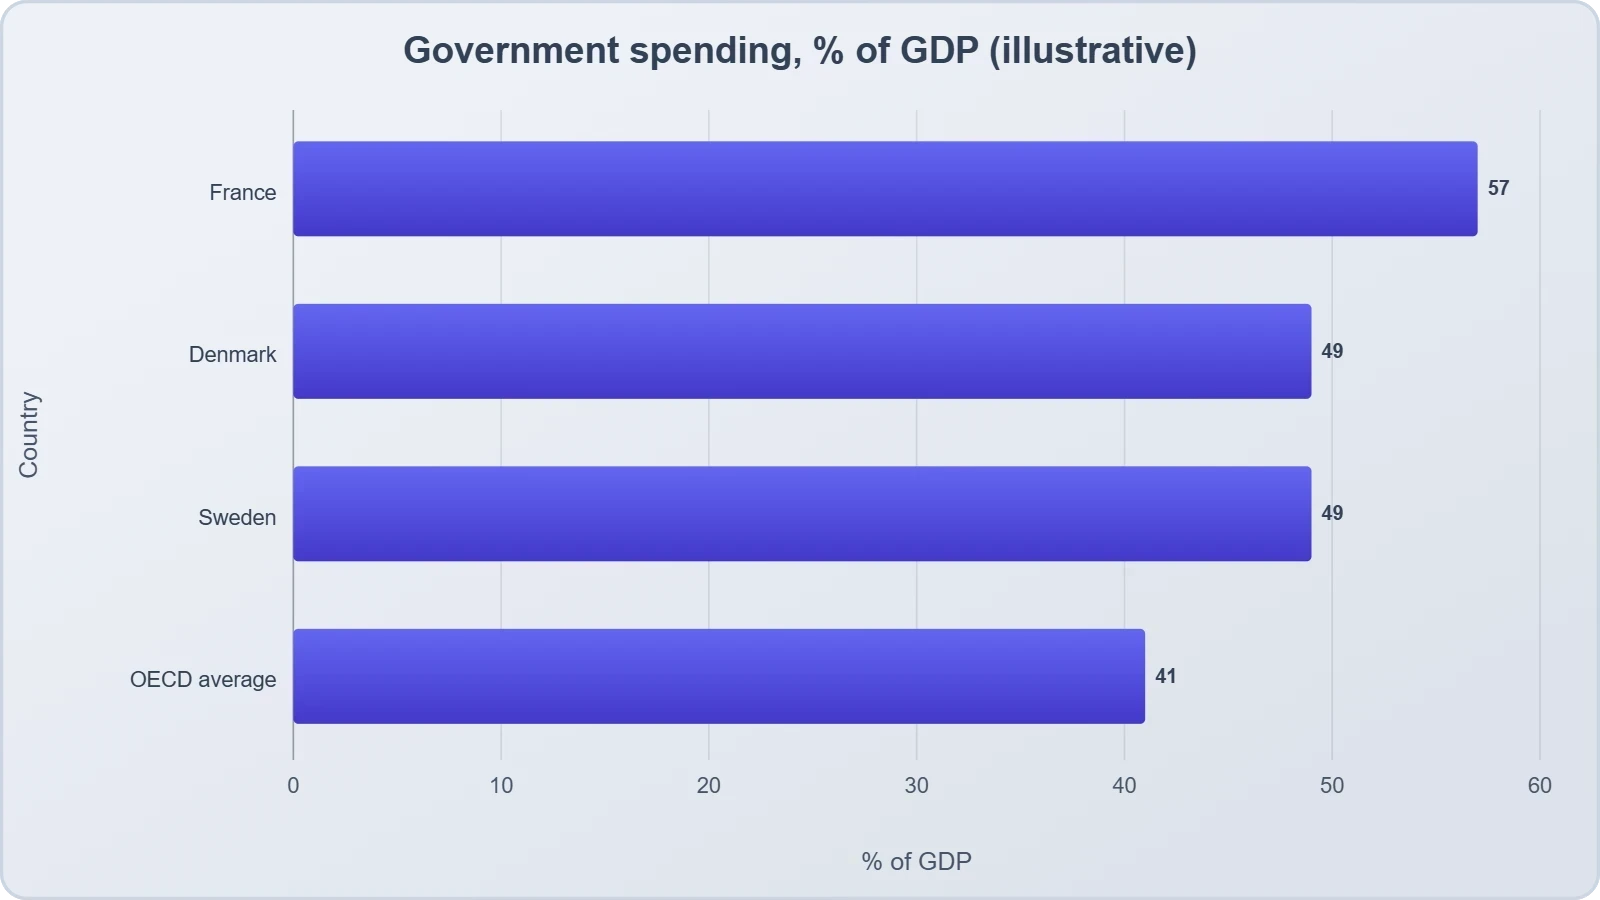
Nordic countries have paired high spending with reform-minded pension and labor policies, adjusting retirement ages and benefit formulas as demographics shifted. France has largely deferred such adjustments, allowing pension costs to grow while the political system resists the necessary corrections.
Why France Struggles to Adjust
France's difficulty stems from a combination of street politics, fragmented party competition, and a social contract that treats retirement as an earned right rather than a fiscal variable. Each attempted reform triggers protests, and each protest strengthens opposition parties that promise reversal.
The result is a nation that recognizes its problem with unusual clarity yet cannot act on that recognition. Krugman's observation that France is on an unsustainable path is widely shared among economists; the disagreement lies in whether the political system can ever deliver the correction.
Pathways Forward: Reform, Taxation, and the Cost of Delay
France's options are narrow and each carries political peril. It can raise taxes, cut spending, reform pensions, or borrow more, and every choice alienates a constituency. The cost of delay, however, compounds relentlessly through higher interest payments and diminished credibility.
Taxation as a Difficult Lever
Raising taxes could reduce the deficit without touching pension formulas directly, but French tax burdens are already among the highest in the developed world. Additional increases risk suppressing growth, which would worsen the debt ratio even if revenue rises nominally.
Wealth and consumption taxes are frequently proposed, yet each faces constitutional, legal, and political obstacles. The Yellow Vest experience demonstrated that visible tax increases can ignite nationwide resistance, making taxation a fragile instrument for fiscal consolidation.
The Cost of Deferral and the Generational Question
Deferring reform until after elections converts a solvable problem into a compounding one. Each year of delay raises the eventual adjustment required, and markets price that expectation into borrowing costs today. The young, already protesting poor prospects, will inherit both the debt and the diminished services.
France's predicament ultimately asks whether a democratic system can impose present sacrifice for future stability. The riots, the frozen retirement age, and the widening credit spreads are all expressions of that single unresolved question, and the answer will shape Europe's fiscal landscape for years.
From our network :
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
RESOURCES
- 2023 French pension reform strikes - Wikipediaen.wikipedia.orgA series of protests began in France on 19 January 2023 with a demonstration of over one million people nationwide, organised by opponents of…
- What Does France's Political Instability Mean for Europe?cfr.orgDec 17, 2024 ... ... pension system, and steering the European Union ... financial markets that France can realistically bring down its level of…
- Unrest in France challenges Macron's ambitions - Brookings Institutionbrookings.eduMar 31, 2023 ... Macron also committed to working with unions on implementing the pension reform. Another option on the table — which Macron…
- France's new PM faces a bumpy ride with budget challenges ... - PBSpbs.orgSep 17, 2025 ... ... France's budget crisis, a deeply divisive issue in Parliament. ... They also continue to protest against Macron's pension reform…
- France Protests Test Government's Commitment to Rightshrw.orgMar 24, 2023 ... ... pension reform plan that increases the retirement age by two years, to 64 ... Riot police scuffle with protesters…
- France has demonstrated resilience amid recent global shocks, but ...facebook.comJul 6, 2026 ... ... France BBC and Financial Times reporting on Yellow Vest protests and pension reform French Ministry of Economy and Finance…
- French prime minister backs suspending unpopular pension reform ...aljazeera.comOct 14, 2025 ... Prime Minister Sebastien Lecornu faces two no-confidence motions this week as France's political crisis deepens ... France's ratio of debt ...
- 'France, truly, is on the brink' and days away from a make-or-break ...fortune.comOct 17, 2026 ... ... debt crisis, analyst warns, as protests turn into riots. Jason Ma. By ... France's retirement largesse to the student…
- France's riots and mounting debt reveal a country in disarray ahead ...chathamhouse.org3 days ago ... In any case, it was one of the largest mobilizations since protests against the government's pension reform bill in 2023,…
- French pension reform: 14th day of national protest ends with low ...lemonde.frJun 6, 2023 ... Despite already being signed into law, opponents of the pension reform bill took to the streets across France on Tuesday…
- Greece debt crisis: Scuffles at pension reforms protest - BBC Newsbbc.comJan 8, 2016 ... Scuffles break out during a protest against proposed pension reforms, which the Greek government says are needed to satisfy international ...
- Markets focus on French debt amid government upheavalallianzgi.comSep 9, 2025 ... Markets are monitoring a political crisis in France after the collapse of Prime Minister François Bayrou's government. ... pension reform.
- Understanding France's Polycrisis - The New York Timesnytimes.comOct 6, 2026 ... ... pension reform to bike lanes were part of everyday life. ... France has suddenly been engulfed by crisis —…
- Pension reform in France: Diagnosis of a crisis - GIS Reportsgisreportsonline.comMar 31, 2023 ... March 23, 2023: Protesters take part in a nationwide strike in central Paris, France, against a pension reform plan by…
- S&P hands crisis-prone France surprise downgrade - Reutersreuters.comOct 17, 2025 ... S&P downgrades French debt, cites political instability · Lecornu survives no-confidence votes, sacrifices pension reform · Finance minister urges ...
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments