Nigeria's state-owned energy champion is preparing to invite outside capital into its share register for the first time in its modern corporate life. NNPC Limited, the commercial entity carved out of the old Nigerian National Petroleum Corporation under the Petroleum Industry Act 2021, is weighing the sale of a 5% to 10% equity stake through an initial public offering anchored in Lagos, with a possible secondary listing in London or New York. Group Chief Executive Officer Bashir Bayo Ojulari framed the move less as a fundraising sprint and more as a governance reset, telling Reuters that transparency and corporate discipline rank above the cash itself.
The timing matters enormously. Nigeria's domestic bourse has just absorbed the Dangote Petroleum Refinery offer, which drew orders worth roughly N6.4 trillion against a target near $1.6 billion, a demonstration of retail and institutional appetite that few expected at this scale. That success has given policymakers and NNPC executives a template: sell a minority slice to citizens, retain state control, and use public-market scrutiny as an external audit function. The proposal also carries geopolitical weight, since a London or New York listing would place Africa's largest oil company inside the disclosure regimes that global asset managers trust.
What follows examines the ownership architecture under consideration, the legal scaffolding of the Petroleum Industry Act, the readiness gaps in financial reporting and corporate governance, the Dangote precedent, and the realistic timeline stretching toward 2028. It also weighs the risks that could derail the offering, from valuation disputes to political resistance over foreign ownership of national resources. The story is ultimately about whether a state oil company can behave like a listed corporation without surrendering the strategic levers of the state.
On This Page
- The Ownership Architecture Behind a Partial Float
- The Petroleum Industry Act as Legal Foundation
- The Dangote Precedent and Domestic Appetite
- Timeline, Readiness, and the Road to 2028
- Risks, Valuation, and the Politics of National Assets
- What the Offering Signals for African State Enterprise Reform
- The Road Ahead for NNPC and Its Investors
TL;DR NNPC Limited is exploring an IPO of 5% to 10% of its shares, primarily on the Nigerian Exchange with a possible secondary listing in London or New York. CEO Bashir Bayo Ojulari says the primary objective is stronger transparency and corporate governance, with capital raising secondary. Preparations could consume all of 2025, and the company has previously targeted a 2028 listing roadmap. The Petroleum Industry Act 2021 underpins the plan, requiring NNPC to operate profitably, pay dividends, and retain 20% of profits. The Dangote refinery's heavily oversubscribed offer has boosted momentum for domestic retail participation.
The Ownership Architecture Behind a Partial Float
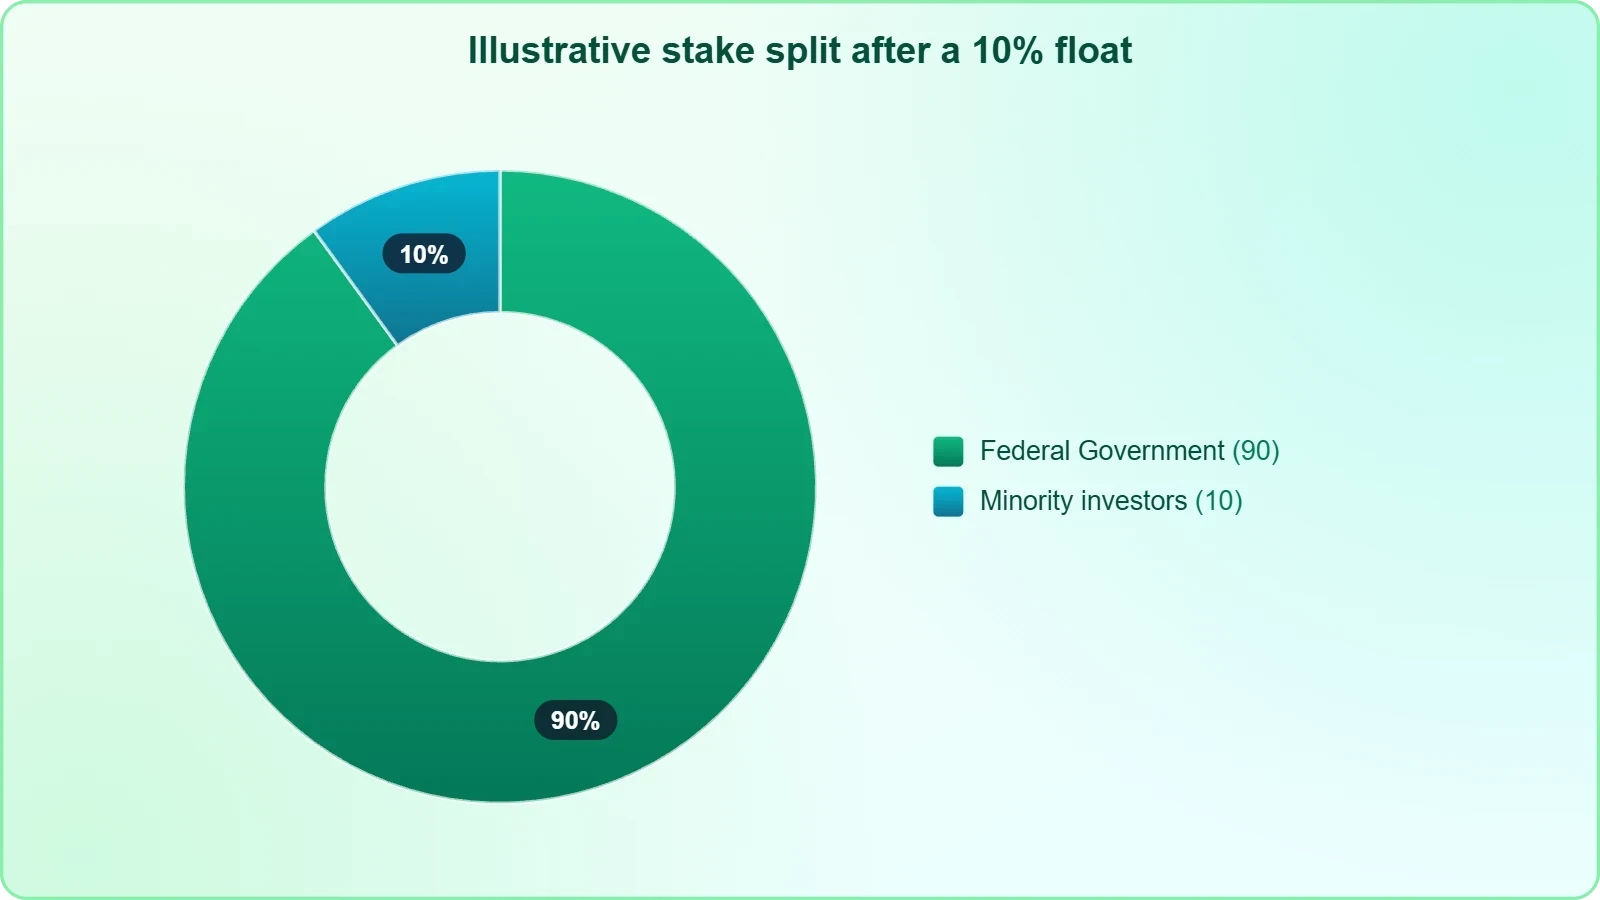
The design being contemplated is deliberately conservative. NNPC would release a minority stake of between 5% and 10%, keeping the Federal Government firmly in control of operational decisions while allowing Nigerian citizens and institutions to hold a financial interest in the national oil company. Ojulari described a model in which Nigerians own shares and the state retains strategic command, a structure that echoes partial privatisations across emerging markets where governments seek capital discipline without ceding sovereignty over natural resources. The approach also protects the company from the hostile takeover dynamics that a larger free float might invite.
This minority-sale logic carries real consequences for how the company will be governed afterward. A small float still triggers continuous disclosure obligations, quarterly reporting, and independent director expectations, which is precisely the discipline the company says it wants. Yet a 5% to 10% stake limits the influence of outside shareholders, meaning governance improvements will depend on regulatory pressure and board composition rather than activist investors. The balance is delicate: enough public ownership to import accountability, but not enough to threaten state control over crude allocation, subsidy decisions, or strategic partnerships.
Domestic First, International Second
The sequencing of the listing is central to the strategy. Ojulari indicated the share sale would focus mainly on Nigeria's domestic capital market, with international listings possibly following as a secondary step. That ordering reflects both political sensitivity and practical reality. Selling first in Lagos allows the government to frame the offer as a national wealth-building exercise, letting ordinary Nigerians participate in the oil company they collectively own. It also tests the depth of the local market before subjecting the company to the scrutiny of London or New York investors.
A secondary listing abroad would bring different benefits and different costs. London and New York offer access to deep pools of institutional capital, index inclusion, and the credibility that comes with stringent disclosure rules. But they also expose NNPC to litigation risk, short-seller scrutiny, and the demanding reporting standards of the US Securities and Exchange Commission or the UK Financial Conduct Authority. For a company still closing governance gaps, that is a formidable step, which explains why executives describe international listing as a possibility rather than a commitment.
Subsidiary Listings as a Parallel Track
Beyond the parent company, NNPC may pursue listings of individual subsidiaries, a model that mirrors the approach taken by the UAE's state oil firm ADNOC. ADNOC has floated units across refining, distribution, drilling, and gas, creating a family of listed entities that together broaden investor access while the parent retains control. For NNPC, subsidiary listings could unlock value in discrete business lines, allow targeted capital raising, and create benchmarks that help the market value the parent. It is a modular strategy that spreads execution risk across several transactions rather than concentrating it in one enormous offer.
This modular path also has political advantages. Each subsidiary listing can be presented as a distinct national achievement, and each can be timed to favourable market conditions. It allows the company to build a track record of successful capital-market transactions before attempting the flagship parent listing. Investors, in turn, gain exposure to specific segments of the value chain, from upstream production to downstream retail, without taking on the full complexity of an integrated national oil company. The approach rewards patience and sequencing over a single dramatic debut.
The Petroleum Industry Act as Legal Foundation
Every element of this offering traces back to the Petroleum Industry Act 2021, the legislation that transformed the former Nigerian National Petroleum Corporation into a commercially driven limited liability company in July 2022. The law did more than rename an institution; it imposed a new operating philosophy. NNPC Limited must now operate profitably without relying on government funds, declare dividends to shareholders, and retain 20% of its profits to support business growth. Those requirements create the financial discipline that a public listing would formalise and expose to market judgment.
The Act effectively converted a fiscal arm of the state into a company expected to stand on its own balance sheet. That shift is profound in a country where the national oil company has historically functioned as a conduit for subsidies, joint-venture cash calls, and revenue remittances to the federation account. Under the new framework, the company must account for profit and loss, justify capital allocation, and demonstrate that it can fund operations without periodic government injections. The IPO is the logical endpoint of that transition, converting statutory discipline into market discipline.
Profitability, Dividends, and the 20% Retention Rule
The retention rule deserves particular attention because it shapes the company's capital structure. Keeping 20% of profits for growth means NNPC can reinvest in upstream projects, refinery upgrades, and gas infrastructure without returning to the government or to debt markets for every expansion. For prospective investors, that retention signals a company building internal financing capacity rather than distributing everything to shareholders. It also creates a visible metric against which the market can assess management's stewardship, since the dividend and retention split becomes a public statement of priorities each financial year.
Dividend policy will be one of the most closely watched elements of any prospectus. A state-controlled company that pays reliable dividends while retaining enough capital for growth offers an attractive profile to pension funds and retail investors seeking income. But the government's dual role as controlling shareholder and recipient of dividends creates potential conflicts, particularly if fiscal pressure tempts policymakers to favour higher payouts over reinvestment. The listing documents will need to address that tension explicitly, and independent directors will carry unusual weight in arbitrating between national fiscal needs and minority shareholder interests.
Governance Gaps Identified by Advisers
Ojulari has been candid that advisers identified gaps in financial reporting and corporate governance during readiness assessments. Those gaps are not trivial. Public companies must produce audited financial statements on fixed schedules, maintain robust internal controls, disclose related-party transactions, and separate management from political direction. For an entity that until recently operated as a government corporation, building those systems requires new talent, new technology, and a cultural shift in how decisions are documented and defended. The company says it has completed a baseline assessment and is now closing the identified deficiencies.
The governance question extends beyond accounting. Investors will ask who appoints the board, how independent directors are selected, whether the CEO can be removed for performance rather than political reasons, and how conflicts between the company and the state are resolved. These are the questions that determine whether a listed state-owned enterprise trades at a premium or a discount to peers. NNPC's answers will shape its valuation as much as its oil reserves, and the credibility of those answers will be tested the first time the company must choose between commercial logic and political convenience.
The Dangote Precedent and Domestic Appetite
Momentum for the NNPC offering has accelerated because of a transaction that had nothing directly to do with the state oil company. Dangote Petroleum Refinery's public offer, which closed on 27 October, attracted orders worth approximately N6.4 trillion, or about $4.78 billion, from Nigerian retail and institutional investors. That was almost three times the refinery's target of roughly $1.6 billion. The oversubscription demonstrated that domestic investors will mobilise enormous sums for a well-presented industrial asset, and it gave NNPC a ready-made argument that the Nigerian market can absorb a landmark energy listing.
The Dangote result also carries symbolic weight. It showed that Nigerian retail investors, long confined to banking and consumer stocks, are willing to commit capital to heavy industry and energy. For NNPC, that is encouraging because a domestic-first IPO depends on broad citizen participation, not just a handful of pension funds. The refinery offer created a template for marketing, allotment, and public communication that NNPC can study closely. It also raised expectations: investors who were rewarded by Dangote will expect similar treatment from the national oil company.
Reading the N6.4 Trillion Order Book
The scale of the Dangote order book deserves careful interpretation. An oversubscription of nearly three times target suggests either that the offer was conservatively sized or that domestic liquidity is deeper than previously assumed. Both readings favour NNPC's planning. A conservatively sized offer protects the share price after listing, while deep liquidity means a larger NNPC tranche could still be absorbed. The final allotment and proceeds remain subject to the post-offer process, so the headline figure reflects demand rather than settled capital, but the signal is unmistakable.
For policymakers, the Dangote experience validates the idea that national assets can be shared with citizens through public markets. That narrative is politically potent in a country where wealth concentration and foreign ownership of strategic resources are sensitive topics. NNPC can position its IPO as an extension of economic inclusion, letting Nigerians own a piece of the oil company whose revenues have long flowed through government channels. Whether that framing survives contact with valuation realities and allotment mechanics is another matter, but the political logic is clear.
Implications for Retail and Institutional Investors
Retail investors would gain direct exposure to Africa's largest oil company, an asset previously inaccessible outside government channels. Institutional investors, particularly pension funds managing vast domestic pools, would acquire a liquid, dividend-paying energy holding that helps match long-dated liabilities. The combination could deepen the Nigerian Exchange, improve price discovery for energy assets, and create a benchmark against which other state enterprises might be valued. It also gives the bourse a marquee name capable of attracting foreign passive flows once index inclusion follows.
The risks for investors are equally real. State-controlled enterprises often trade at discounts because minority holders cannot influence strategy, related-party transactions can disadvantage outsiders, and political interference can override commercial logic. NNPC's prospectus will need to address these concerns with credible protections, including independent directors, related-party approval rules, and clear dividend commitments. Investors who remember the history of opaque oil revenue management will demand more than assurances; they will want structural safeguards written into the company's articles and enforced by regulators.
We Also Published
- 01
- 02
- 03
- 04
Timeline, Readiness, and the Road to 2028
The calendar is the least glamorous but most consequential variable. Ojulari has said preparations could take at least all of next year, and the company previously outlined a roadmap to list on the Nigerian Exchange by 2028. In September 2026 he confirmed that no date had been fixed and that the final decision rested with shareholders. That combination of ambition and caution is telling: management wants to be ready as soon as possible, but it refuses to commit to a date it cannot control. The gap between readiness and execution is where most state-enterprise listings fail.
Investors should therefore treat any timeline as indicative rather than binding. The sequence runs from closing governance gaps, to audited financials, to adviser sign-off, to shareholder approval, to regulatory filing, to marketing, and finally to listing. Each stage can slip. Political transitions, oil price swings, and market volatility can all delay a transaction that depends on favourable conditions. The 2028 target is best understood as a directional commitment rather than a promise, and the company's language has consistently preserved that flexibility.
Why the Decision Rests With Shareholders
Ojulari's insistence that the IPO decision belongs to shareholders rather than management reflects the company's legal structure. As a limited liability company owned by the state, NNPC answers to a shareholder base ultimately represented by the Federal Government. Management can prepare, advise, and execute, but it cannot unilaterally sell equity in a national asset. That governance feature is appropriate, yet it introduces political risk: a change in administration, a shift in fiscal priorities, or public opposition could halt the process at any stage, regardless of how much preparatory work has been completed.
The shareholder dimension also shapes how the offer will be marketed. Because the government is both seller and controlling owner, the transaction must be framed as a national decision rather than a corporate one. That means extensive consultation with legislators, state governors, and civil society, all of whom will have views on whether selling a stake is prudent. The company's communication strategy will need to reassure sceptics that control is retained while emphasising the governance and transparency benefits that public ownership brings.
Preparing Financial Reporting and Controls
The technical work of readiness is substantial. Public companies must produce audited financial statements prepared under recognised accounting standards, maintain internal controls over financial reporting, and disclose material risks in a prospectus. For NNPC, that means reconciling years of accounts, documenting related-party transactions with government entities, and building systems that can produce reliable numbers on tight deadlines. Advisers have already flagged gaps in these areas, and closing them is the precondition for any credible offer.
Beyond accounting, readiness includes investor relations, board independence, and disclosure culture. A company that has never answered to public shareholders must learn to communicate quarterly results, explain strategic decisions, and accept market criticism without treating it as disloyalty. That cultural transformation may prove harder than the technical fixes. The most successful state-enterprise listings, from Saudi Aramco to ADNOC's units, invested heavily in governance infrastructure before approaching investors, and NNPC will need comparable commitment to convince a sceptical market.
Risks, Valuation, and the Politics of National Assets
No discussion of this offering is complete without confronting the risks. Valuation is the first and most contentious. NNPC has not disclosed a valuation, and pricing a national oil company is inherently difficult when oil price assumptions, production targets, subsidy obligations, and joint-venture liabilities all interact. A low valuation risks accusations that the government is selling national assets cheaply, while a high valuation risks a weak aftermarket and disappointed retail investors. The company must find a price that satisfies fiscal expectations, political scrutiny, and market discipline simultaneously.
Political risk is equally significant. Selling equity in the national oil company touches deep sensitivities about sovereignty, resource control, and the role of foreign capital. Opposition politicians may frame the IPO as a disguised privatisation, even though the state retains control. Civil society groups may demand guarantees on transparency and revenue remittance. Regional interests may question how proceeds are distributed. These debates can delay or derail the transaction, and management's insistence that shareholders decide is partly a recognition that the political process must run its course before any offer can proceed.
Valuation Uncertainty and Market Conditions
Market conditions add another layer of uncertainty. Oil prices are volatile, and investor appetite for energy listings fluctuates with the commodity cycle. A listing launched during a price slump would likely price poorly, while one launched during a boom might attract accusations of opportunism. The company's decision to prepare thoroughly before committing to a date reflects this reality. It also explains why a domestic-first approach is attractive: Nigerian investors may be more forgiving of valuation debates than international institutions applying strict comparables to a state-controlled entity.
The absence of a disclosed valuation also complicates public communication. Without a number, the government cannot quantify what Nigerians will own or what the proceeds will fund. That ambiguity can breed suspicion. A credible prospectus will need to present reserves, production, cash flow, debt, and dividend capacity in transparent detail, allowing investors to form their own judgments. The quality of that disclosure will determine whether the IPO is seen as a genuine market transaction or as a fiscal manoeuvre dressed in corporate clothing.
Balancing State Control With Minority Rights
The central tension of the entire project is the coexistence of state control and minority rights. The government will remain the dominant shareholder, appoint the board, and shape strategy. Minority investors will hold a financial stake but limited voting power. The success of the listing therefore depends on credible protections: independent directors with real authority, transparent related-party rules, a clear dividend policy, and regulatory oversight that treats all shareholders equally. Without those safeguards, the stock will trade at a discount and the governance objectives will remain rhetorical.
International experience offers both encouragement and caution. Saudi Aramco's listing delivered scale but limited liquidity and persistent governance questions. ADNOC's subsidiary listings have been well received because they combined clear commercial logic with strong disclosure. NNPC can learn from both. The path to a successful offering runs through demonstrable governance reform, not marketing. If the company can show that public ownership has changed how decisions are made, investors will respond; if it cannot, no amount of national pride will sustain the share price.
What the Offering Signals for African State Enterprise Reform
Beyond Nigeria, the NNPC proposal carries a broader message about how African state enterprises are approaching capital markets. For decades, national oil companies operated as opaque extensions of government, shielded from investor scrutiny and insulated from commercial pressure. The shift toward partial listings reflects a recognition that transparency and capital discipline can strengthen rather than weaken state control. Governments are discovering that selling a minority stake, if structured carefully, imports the governance standards that domestic institutions have struggled to impose through regulation alone.
The model is not without critics. Some argue that partial privatisation creates the appearance of reform without its substance, leaving control concentrated and accountability ambiguous. Others contend that public markets are the most effective external discipline available to states with weak regulatory capacity. NNPC's experience will become a test case for the continent, watched by governments in Angola, Algeria, and beyond who face similar pressures to modernise their national oil companies. The outcome will shape how African policymakers think about the relationship between sovereignty and capital markets for years to come.
Lessons From ADNOC and Saudi Aramco
The closest comparables are instructive. ADNOC's subsidiary listings succeeded because each entity had a clear commercial story, strong disclosure, and a credible dividend policy. Saudi Aramco's listing achieved unprecedented scale but faced persistent questions about liquidity, valuation, and governance. NNPC's proposed structure, with a domestic-first parent listing and possible subsidiary offerings, borrows from both playbooks. The emphasis on governance over capital raising aligns with the ADNOC approach, while the scale and national symbolism echo Aramco. The synthesis may prove more durable than either model alone.
What distinguishes NNPC's situation is the depth of the domestic investor base it can draw upon. Saudi Arabia and the UAE relied heavily on sovereign and institutional capital, supplemented by retail participation. Nigeria's Dangote offer demonstrated genuine retail appetite, suggesting that NNPC could build a broad citizen shareholder base. That would be a distinctive achievement, creating a constituency for transparency and commercial performance that extends beyond institutional investors. If successful, it could become a template for other African state enterprises seeking to broaden ownership without surrendering control.
Implications for Nigeria's Capital Market
A successful NNPC listing would transform the Nigerian Exchange. It would add a marquee energy name, deepen liquidity, attract foreign passive flows, and create a benchmark for valuing other state assets. It would also strengthen the case for pension fund allocation to domestic equities and encourage more companies to consider public listings. The Dangote offer already demonstrated the market's capacity to absorb large transactions; NNPC would test whether that capacity extends to a state-controlled entity with a more complex governance profile.
The broader economic implications are equally significant. A listed NNPC would face market pressure to improve operational efficiency, reduce waste, and allocate capital rationally. Those improvements could translate into higher oil production, better refinery utilisation, and stronger fiscal contributions over time. The listing would also give Nigerians a direct financial stake in the oil wealth that has historically flowed through government channels, potentially strengthening public support for difficult reforms. The risks are real, but the potential upside for governance and market development is substantial.
The Road Ahead for NNPC and Its Investors
The offering remains a proposal, not a transaction. No formal timetable, valuation, or prospectus has been published, and the final decision rests with shareholders who answer to the Nigerian public. What exists today is a direction of travel: a state oil company preparing to invite outside capital, a government willing to share minority ownership, and a domestic market that has just demonstrated remarkable appetite for industrial assets. The next two years will determine whether that direction becomes a listing or remains an aspiration.
For investors, the opportunity is a rare chance to own a stake in Africa's largest oil company, with the caveats that accompany state control. For Nigeria, the stakes are larger than any single transaction. A successful listing could strengthen governance, deepen capital markets, and give citizens a tangible share in national wealth. A failed or poorly executed one could set back the cause of state enterprise reform for a generation. The company's emphasis on readiness over speed is therefore encouraging, even if it tests the patience of those eager for a debut.
The most important variable is not oil prices or market conditions but credibility. NNPC must convince investors that public ownership will change how decisions are made, that minority shareholders will be protected, and that the company will operate on commercial rather than political logic. Those assurances cannot be marketed into existence; they must be demonstrated through disclosure, board composition, and behaviour. If the company delivers on governance, the capital will follow. If it does not, no listing venue or national narrative will compensate for the discount investors apply to promises they have heard before.
From our network :
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
RESOURCES
- Resources will be updated soon.
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments