Moody's decision to hold France at Aa3 with a negative outlook is a masterclass in sovereign restraint: the agency declined to strip the republic of its investment-grade standing, yet it pointedly refused to bless the trajectory.
The verdict lands two notches beneath the United States and three beneath Germany, a humbling placement for the eurozone's second-largest economy. Fitch and S&P Global already sit one notch lower, meaning Moody's now stands as the most generous of the three major houses toward Paris.
That relative leniency is not a compliment; it is a warning shot fired across the bow of a fractured political class.
On This Page
The substance behind the rating is fiscal arithmetic colliding with democratic paralysis. France's public debt has climbed to a record $4 trillion, equal to 119% of GDP, the heaviest burden since the immediate aftermath of the Second World War.
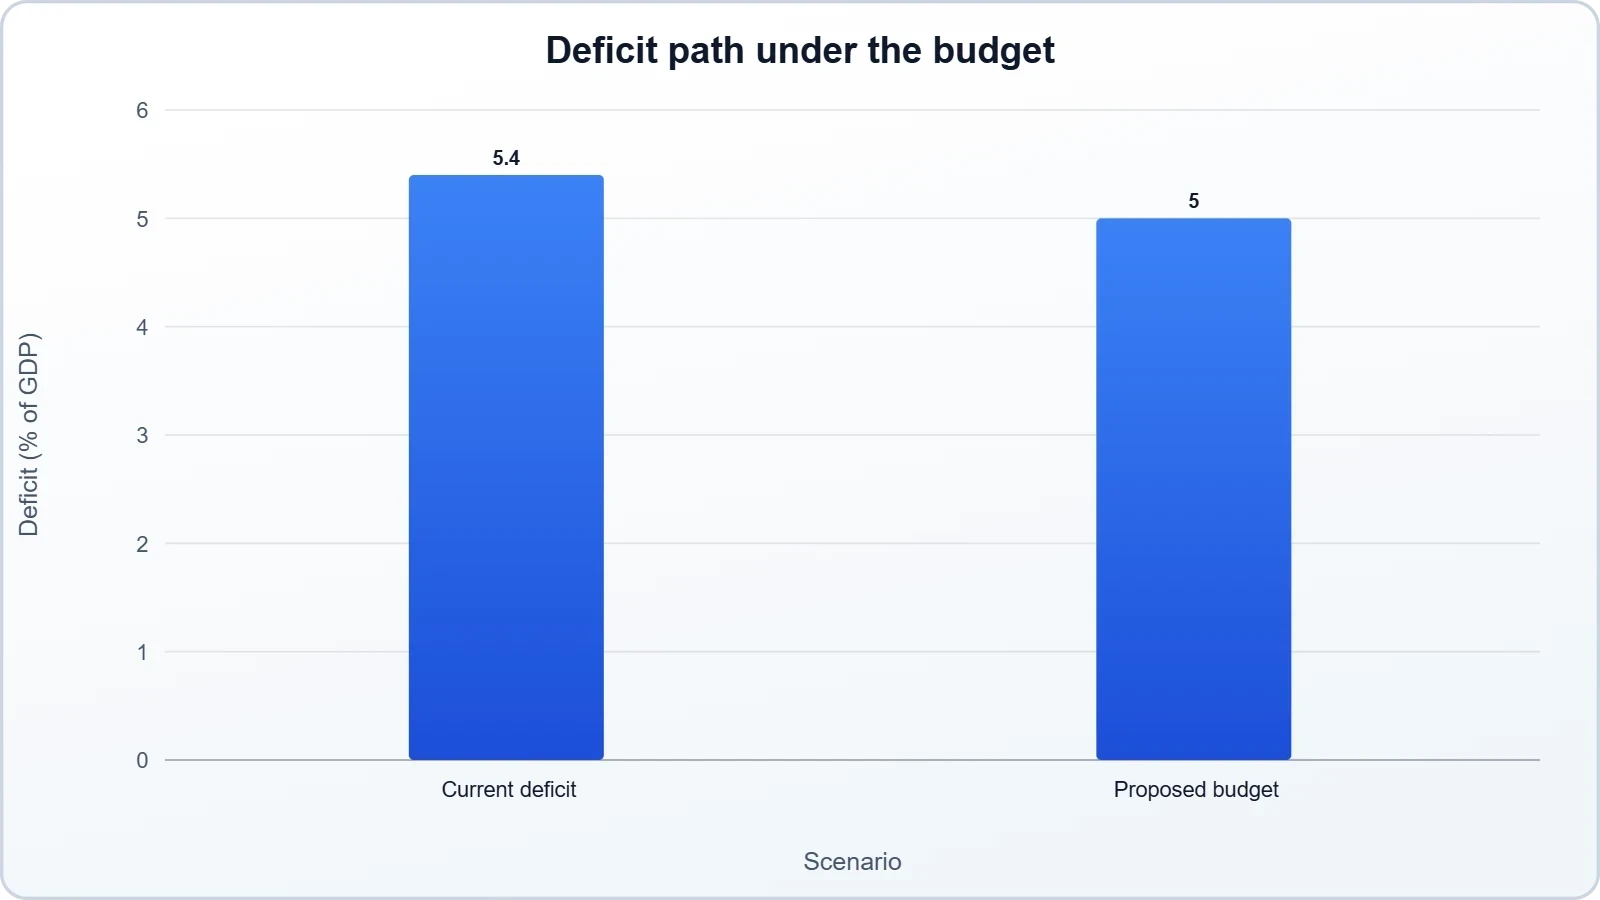
Bond yields have surged to their highest level in twenty-four years, a signal not witnessed since the eurozone debt crisis of 2011. A budget designed to trim the deficit modestly, from 5.4% to 5% of GDP, remains stalled in a National Assembly that cannot agree on the price of fiscal discipline. Moody's expects adoption eventually, perhaps by decree, but projects only a 5.2% outcome.
What elevates this story beyond a routine ratings note is the social combustion surrounding it. For more than a month, French streets have hosted protests that escalated into widespread riots last weekend, beginning with students demanding investment in public education and widening into a cost-of-living revolt as fuel prices climbed.
Similar unrest has flickered across other European countries, suggesting a continental pattern rather than a purely French affliction. With far-right and far-left candidates leading ahead of the spring presidential election, markets are quietly losing faith that either extreme will administer the bitter medicine required.
This analysis dissects the rating logic, the debt mathematics, and the political trap that together define France's fiscal predicament.
TL;DR Moody's retained France's Aa3 rating with a negative outlook, acknowledging a wealthy economy and capable institutions while warning that parliamentary fragmentation and social unrest obstruct deficit reduction. Public debt has reached a record $4 trillion, or 119% of GDP, with bond yields at twenty-four-year highs and the deficit stuck near 5.4% of GDP. Moody's expects only a modest decline to 5.2%, projects debt near 122% next year, and sees the burden rising through the decade absent a significant post-election fiscal effort. An 8.5-year average debt maturity buys Paris time, but event risk from geopolitics and domestic instability remains acute.
The Anatomy of a Negative Outlook
A negative outlook is sovereign finance's version of a suspended sentence: no punishment today, but an explicit statement that the court is watching. Moody's framed its decision around two competing realities, one flattering and one damning.
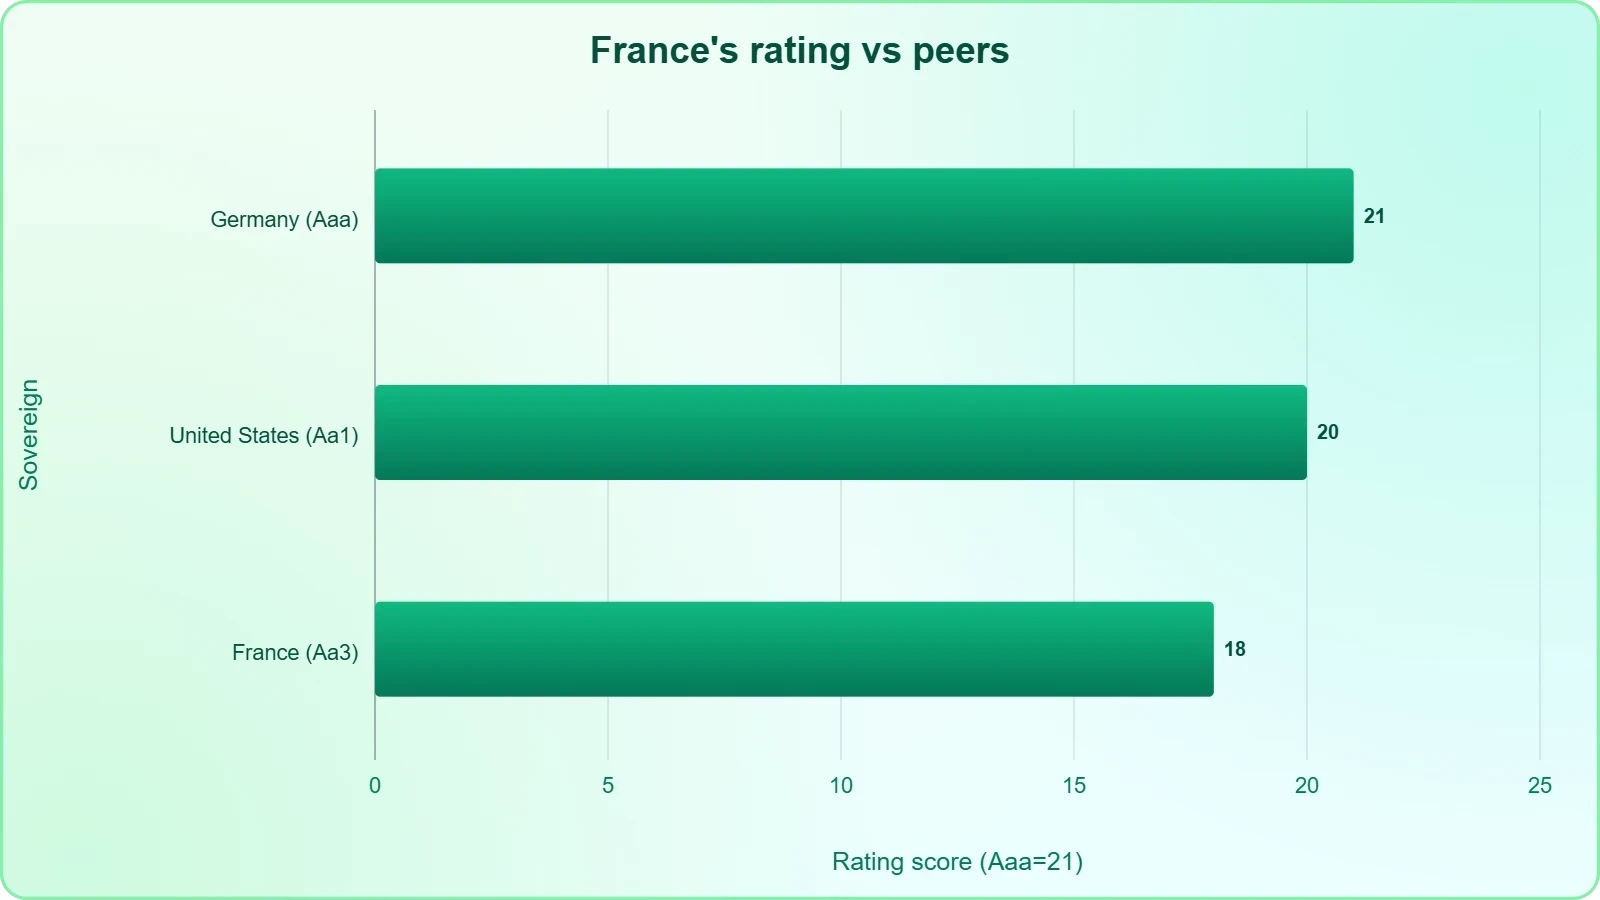
On the credit side, the agency affirmed that France possesses a wealthy, diversified economy and public institutions capable of competent administration. Against that, it warned that political divisions could block the government from taking the difficult steps needed to cut the deficit.
The outlook, in other words, is a bet that institutional quality will eventually overcome legislative chaos, a bet the agency itself seems unsure of winning.
Why Aa3 Survived the Review
The rating survived because France's underlying credit fundamentals remain genuinely strong. A large, high-productivity economy, deep capital markets, and a proven administrative apparatus give the republic buffers that many peers lack.
Moody's explicitly cited these strengths, and its restraint reflects a judgment that the sovereign's capacity to service obligations is not yet in question. Ratings measure willingness and ability together, and France's ability remains intact even as its willingness wobbles.
Timing also mattered. The agency noted that France has room to maneuver because the average maturity of its debt is roughly 8.5 years. Higher borrowing costs must persist for a long stretch before they materially degrade debt affordability.
That structural cushion lets Moody's wait for evidence rather than act on fear, buying the sovereign a window in which political actors could still choose fiscal seriousness over electoral convenience.
The Meaning of the Negative Watch
A negative outlook signals elevated probability of downgrade over the medium term, typically twelve to eighteen months. Moody's tied that signal directly to governance: the growing risk that a fragmented political landscape will continue to impair the functioning of France's legislative institutions.
This is a political judgment dressed in financial language, and it targets the machinery of lawmaking rather than the economy itself. When parliaments cannot pass budgets, creditors notice.
The agency also flagged France's special vulnerability to event risk, both geopolitical and domestic. In sovereign analysis, event risk describes shocks that bypass gradual trends and strike suddenly, such as riots, government collapse, or external conflict. France now carries both varieties simultaneously, an unusual combination for a core European economy. The negative outlook is therefore less a forecast about numbers than a statement about fragility.
The Debt Arithmetic Behind the Warning
Numbers tell the story more bluntly than any communiqué. France's public debt has reached a record $4 trillion, equivalent to 119% of GDP, the highest ratio since just after the Second World War.
That comparison is not rhetorical decoration; it places contemporary France in the same fiscal neighborhood as its postwar reconstruction era, when the state rebuilt an economy from rubble. Today there is no rubble, only a structural gap between what the state promises and what it collects.
Deficit Trajectory and Budget Gridlock
The budget under discussion would reduce the deficit modestly, from 5.4% to 5% of GDP, yet it has not passed because of political gridlock. Moody's expects eventual adoption, possibly by decree as the National Assembly delays, but projects the deficit falling only to 5.2% of GDP.
Weaker growth than the government forecasts and the political difficulty of genuine spending cuts explain the gap between ambition and outcome.
That shortfall matters because deficit reduction compounds slowly. A 0.2 percentage point miss may appear trivial in a single year, but repeated annually it accumulates into tens of billions of euros of additional debt. Moody's is effectively telling Paris that even its best-case legislative scenario produces underwhelming fiscal consolidation. The agency's arithmetic assumes political friction as a permanent feature, not a temporary inconvenience.
Bond Yields and Market Confidence
Bond yields have risen to their highest level in twenty-four years, a warning sign not seen since the eurozone debt crisis in 2011. Yields are the market's price for lending to a government, and their climb signals that investors demand compensation for perceived risk. For France, the world's fourth-largest sovereign borrower, even modest yield increases translate into substantial annual interest obligations.
The 8.5-year average maturity of French debt provides a genuine buffer, since recent higher borrowing costs must persist for a long time to significantly worsen debt affordability. Yet that cushion cuts both ways: it delays the pain, but it also delays the market discipline that might force political action.
France can drift for years before refinancing costs bite, which paradoxically reduces urgency in a system already allergic to urgency.
Political Fragmentation as a Fiscal Constraint
Moody's report reads at times like a political science essay wearing a credit analyst's suit. The agency pointed to a divided parliament that often conflicts with the government, alongside political and social instability, as direct threats to debt reduction.
This framing is deliberate: sovereign creditworthiness depends not merely on economic capacity but on a state's ability to make and execute decisions. A parliament that cannot pass a budget is, in rating terms, a broken transmission mechanism between revenue and obligation.
The Street and the Ballot Box
For more than a month, France has witnessed protests that turned into widespread riots last weekend. Students first demonstrated against a lack of investment in public education, and others later joined to protest the high cost of living as fuel prices rose.
Similar protests have occurred in other European countries, hinting at a shared continental strain over purchasing power and public services.
The electoral dimension sharpens the danger. With far-right and far-left candidates leading ahead of the spring presidential election, markets are losing confidence that either side will take the steps needed to restore fiscal order.
Both extremes have historically favored spending promises over consolidation, and both draw energy from the same popular anger now filling the streets. The ballot box and the barricade are reinforcing each other.
Why Institutions Still Matter
Yet Moody's also affirmed that France has capable public institutions, and that judgment carries weight. Institutions are the machinery that converts political will into policy, and France's administrative state remains among the world's most professional.
The agency's expectation that the budget will eventually be adopted, possibly by decree, reflects faith in procedural mechanisms that can bypass legislative paralysis when necessary.
That faith has limits. Governing by decree may pass budgets, but it does not build durable fiscal consensus, and it can inflame the very instability the rating warns against. Moody's is thus caught between respect for French institutional competence and alarm at French political dysfunction.
The negative outlook is the honest resolution of that tension: credit for the machinery, skepticism about the operators.
The European and Global Context
France's predicament is not hersmetically sealed within French borders. Similar protests have occurred in other European countries, suggesting that the cost-of-living shock and the strain on public services are continental phenomena.
When multiple sovereigns face the same social pressures simultaneously, the fiscal room available to any single government shrinks, because regional growth weakens and political contagion spreads. France's rating is therefore a bellwether as much as a verdict.
Lessons from the Eurozone Crisis
The comparison to 2011 is instructive and ominous. During the eurozone debt crisis, rising yields on peripheral sovereign debt exposed the fragility of a currency union lacking fiscal integration. France was then a pillar of stability, a core creditor whose strength anchored the system.
Today the warning sign appears on French debt itself, a reversal that would have seemed implausible fifteen years ago.
Yet the institutional architecture has changed since 2011. Banking union, the European Stability Mechanism, and the European Central Bank's willingness to act as a backstop have thickened the safety net.
France benefits from these defenses, and its status as a core economy means its distress would trigger systemic responses unavailable to smaller members. The buffer is real, but it is a buffer, not a cure.
Implications for Global Investors
For global investors, the Moody's note is a reminder that sovereign risk in advanced economies is no longer a theoretical curiosity. France's debt is held widely across pension funds, insurers, and central bank reserves, making its yield movements a global benchmark.
A sustained rise in French borrowing costs would ripple through corporate spreads, bank balance sheets, and cross-border capital flows.
The agency's expectation that the debt burden will keep rising through the rest of the decade is the crucial forward-looking signal. Rising debt in a low-growth environment creates a compounding trap, where interest costs crowd out discretionary spending and reduce the fiscal space needed for reform. France has time, but time is precisely the resource that political systems tend to waste.
- 01
- 02
- 03
- 04
We Also Published
What Comes After the Election
Moody's is explicit that a significant and sustained fiscal effort will be needed after the presidential election to stabilize the debt, which is on track to reach 122% next year.
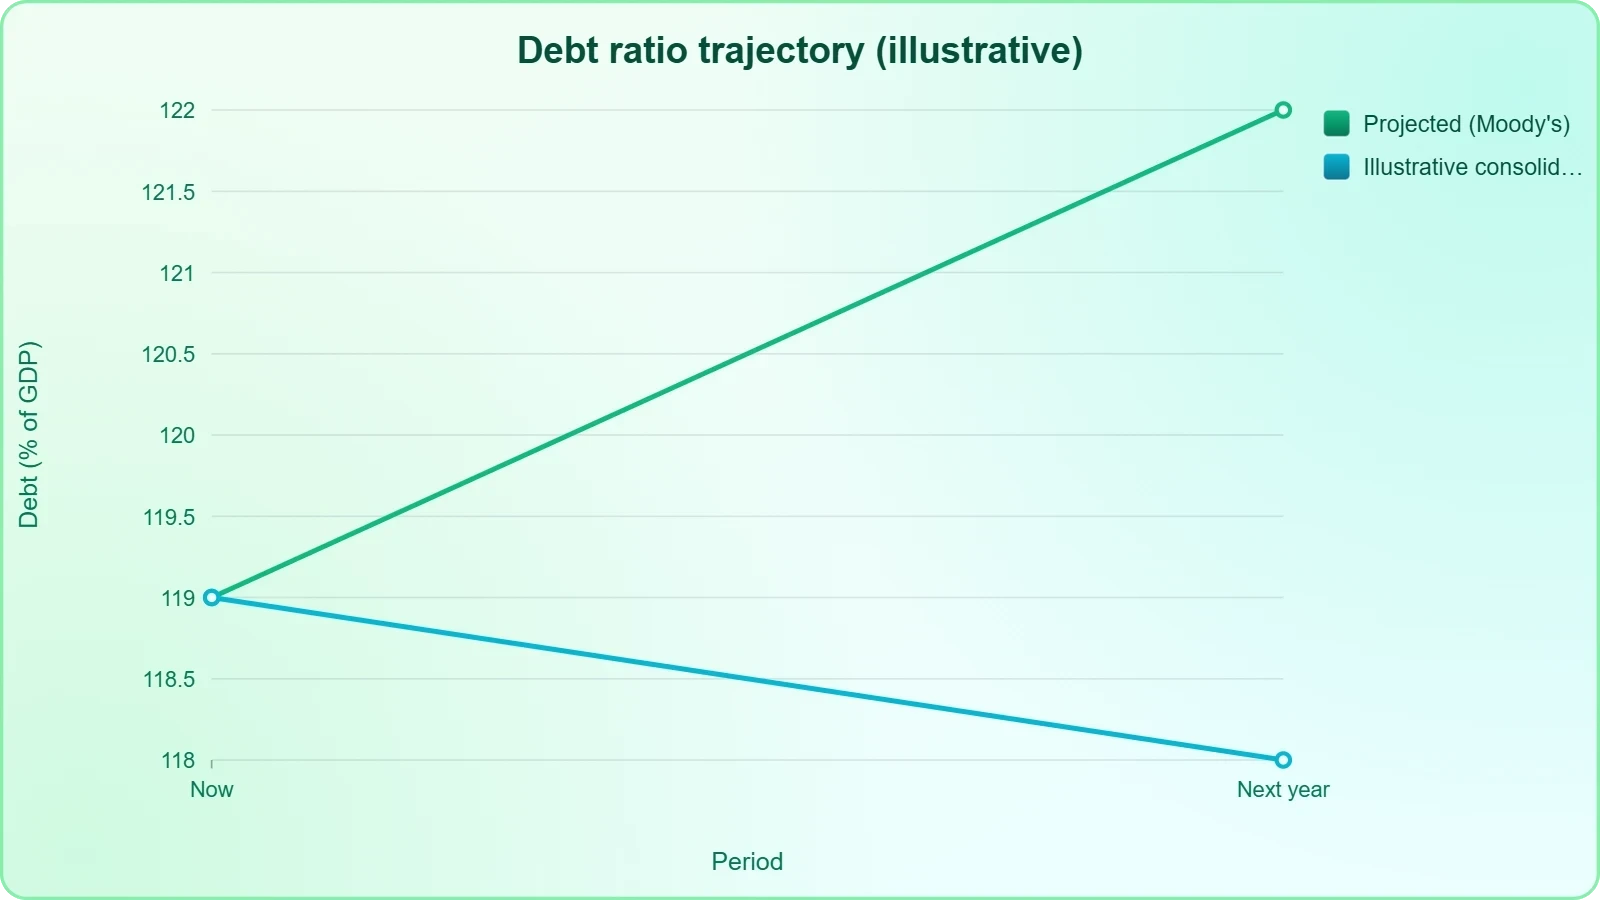
The agency also judges it unlikely that the next president and government will reduce the deficit quickly, given social tensions, a fragmented political environment, and weak GDP growth. This is a forecast of continued drift, not imminent crisis, and the distinction matters enormously for how markets should price French risk.
The Reform Imperative
Stabilizing debt at such elevated levels requires primary surpluses, meaning the state must collect more than it spends before interest payments. France has not run such surpluses in decades, and achieving them demands politically toxic choices: spending restraint, revenue increases, or both. Moody's notes the political difficulty of making real spending cuts, a diplomatic phrasing for a brutal reality.
Growth could ease the arithmetic, but weak GDP expansion is precisely what the agency cites as a constraint. Higher growth would raise tax receipts without explicit rate increases, yet France's trend growth remains modest and its reform agenda contested.
The reform imperative therefore rests on decisions that no candidate wants to campaign on and no parliament wants to legislate.
Scenarios for the Rating Trajectory
Three broad paths present themselves. In the benign scenario, a new government secures a credible consolidation plan, growth surprises to the upside, and the negative outlook is eventually removed. In the central scenario, partial measures and decree-driven budgets produce slow deterioration, keeping the outlook negative and inviting further warnings.
In the adverse scenario, political rupture or external shock triggers a downgrade and a sharp repricing of French debt.
Moody's language leans toward the central scenario, with meaningful weight on the adverse one. The agency's emphasis on event risk, both geopolitical and domestic, signals that it is watching for discontinuities rather than gradual trends.
For investors and policymakers alike, the message is that France's fiscal future will be decided less by economics than by politics.
The Verdict and Its Broader Meaning
Moody's has done what prudent analysts do when confronted with a sovereign that is neither failing nor fixing itself: it has withheld punishment while sharpening its warning. The Aa3 rating stands, the negative outlook deepens, and the reasoning centers on a single insight.
France's problem is not a lack of wealth or institutional competence, but a political system increasingly unable to convert those assets into fiscal decisions. The rating is a mirror held up to governance, and the reflection is unflattering.
The numbers reinforce the narrative at every turn. Debt at 119% of GDP, heading toward 122% next year, with deficits stuck above 5% and yields at twenty-four-year highs, describes a sovereign drifting rather than steering.
The 8.5-year maturity profile grants a rare luxury of time, yet time without political will merely postpones the reckoning. Moody's expects the debt burden to keep rising through the rest of the decade, a projection that should concentrate minds in Paris and Brussels alike.
What ultimately emerges is a lesson about the indivisibility of credit and politics in modern democracies. Markets can forgive debt if they trust the institutions that manage it, and they can forgive political noise if the fiscal trajectory is credible.
France currently offers neither reassurance in full measure, and the negative outlook is the price of that ambiguity. The next president inherits not merely a budget problem but a credibility problem, and the rating agencies will be watching how the inheritance is handled.
From our network :
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
RESOURCES
- Moody's keeps France's credit rating but places it on negative outlooklemonde.frOct 25, 2025 ... While maintaining its 'AA3' rating on Friday, the US ratings agency warned about France's 'political fragmentation' much more than its ...
- Moody's Keeps France's Credit Rating Unchanged - Morningstarmorningstar.com2 days ago ... Moody's Ratings kept France's credit rating unchanged on Friday, despite a steady rise in its debts and the political fragmentation…
- France avoids downgrade from Moody's in boost for Macron's ...facebook.com1 day ago ... Moody's downgrades France credit rating over 'political fragmentation' ... rating downgraded, with debt forecast to keep rising amid political ...
- Moody's Ratings changes France's outlook to negative, affirms Aa3 ...ratings.moodys.comOct 24, 2025 ... Any debt issued by the SPPE is backed by unconditional and irrevocable guarantees from the French government for any issuance…
- Moody's sees no quick resolution of French political fragmentationreuters.comOct 2, 2026 ... Moody's is due to update its Aa3 rating on France On Oct. ... Bond dealers see small rise in UK…
- Moody's maintains French credit rating but warns of 'negative' outlookfrance24.comOct 25, 2025 ... Credit ratings agency Moody's on Friday maintained France's Aa3 sovereign rating but downgraded its outlook to “negative” from “stable”, ...
- Moody's hands France surprise downgrade over deteriorating financesreuters.comDec 13, 2024 ... Credit ratings agency Moody's unexpectedly downgraded France's rating ... The political crisis put French stocks and debt under pressure ...
- Moody's Keeps France's Credit Rating Unchanged - WSJwsj.com2 days ago ... ... debts and the political fragmentation that has made it difficult to rein in borrowing. ... France's Debt Crisis Deepens…
- Moody's downgrades 7 French banks amid debt crisis and ... - Fortunefortune.comDec 19, 2024 ... Moody's downgraded the ratings of banks including BNP Paribas and Credit Agricole amid fears over France's debt situation.
- France's Debt Rating Cut on Fears of Political Instabilitynytimes.comSep 12, 2025 ... ... fragmentation and polarization of domestic politics,” Fitch said in a ... ratings agencies, Moody's and S&P Global Ratings, since…
- Moody's downgrades France's credit rating - DW.comdw.comDec 14, 2024 ... Moody's cited France's "political fragmentation" in its decision. ... What to know about the crisis in France. The decision comes…
- France's borrowing costs rise after Fitch downgrade - CNBCcnbc.comSep 15, 2025 ... Fitch downgraded France's credit rating on Friday, and analysts say other agencies could follow suit. France has seen ongoing political ...
- France credit rating downgrade will have wider repercussions - OMFIFomfif.orgOct 16, 2024 ... The rating agency added that 'high political fragmentation and a ... Moody's does not view individual rating changes as a…
- Fitch downgrades France's credit rating amid political crisis | Euronewseuronews.comSep 13, 2025 ... "Fiscal consolidation is difficult in a context of political fragmentation ... debt levels and the legacy of the sovereign debt…
- Could another France downgrade put the EU's credit rating at risk?uk.finance.yahoo.comOct 17, 2026 ... The analysts concluded that political resistance could ultimately constrain the expansion and permanence of the EU bond market without ...
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments