Bangladesh's capital market has long carried a structural imbalance that few regulators care to discuss openly: it leans heavily on the daily trading impulses of individual retail investors, while the patient, long-horizon capital that mature markets rely upon remains conspicuously thin. Masud Khan, chairman of the Bangladesh Securities and Exchange Commission, addressed this imbalance directly at a stakeholder meeting in Dhaka on 29 October 2026, convened to review the Bangladesh Securities and Exchange Commission (Mutual Fund) Rules, 2025. His central argument was unambiguous — a market that depends solely on retail participation cannot achieve sustainable growth, and mutual funds represent the most credible vehicle for broadening the investor base while drawing institutional players into the fold.
The meeting drew a genuinely representative cross-section of the market ecosystem. Representatives from the Dhaka Stock Exchange, the Chittagong Stock Exchange, Central Depository Bangladesh Limited, mutual fund trustees, asset management companies, custodians and other capital market institutions joined BSEC commissioners and officials, with Md Mahmoodul Hoque, executive director of the commission, opening proceedings with a presentation titled "Review on the Bangladesh Securities and Exchange Commission (Mutual Fund) Rules, 2025." The gathering was not merely ceremonial; it formed part of a deliberate regulatory review aimed at identifying amendments that would make the framework more effective and market friendly, guided by international best practice and stakeholder recommendations.
What elevates this consultation above routine regulatory housekeeping is the emphasis Khan placed on financial literacy as a precondition for market depth. He called on market institutions and stakeholders to collaborate in strengthening investors' financial knowledge and awareness, arguing implicitly that informed investors are the foundation upon which mutual funds and institutional participation can flourish. He also offered an assurance that carries weight in a market where regulatory predictability matters enormously: the commission, he said, would not make unreasonable or unjustified decisions, and stakeholders should have confidence in its intentions. The following analysis examines the substance of this consultation, the structural logic behind the mutual fund push, and what it signals for Bangladesh's capital market trajectory.
On This Page
TL;DR BSEC Chairman Masud Khan has positioned mutual funds and institutional investors as the twin engines required for sustainable growth in Bangladesh's capital market, arguing that retail investors alone cannot carry the market. At a 29 October 2026 stakeholder consultation on the Mutual Fund Rules, 2025, the commission signalled openness to amendments grounded in international best practice, paired with a push for stronger financial literacy and a pledge of regulatory restraint. The consultation reflects a broader maturation agenda: widening the investor base, deepening institutional participation, and building a rulebook that can withstand scrutiny from trustees, asset managers, custodians and exchanges alike.
The Structural Case for Mutual Funds in a Retail-Dominated Market
Bangladesh's stock exchanges have historically functioned as arenas for short-term retail speculation rather than venues for long-term capital formation. When a market's daily turnover is driven predominantly by individual investors with limited holding periods, price discovery becomes noisy, volatility amplifies, and companies seeking stable equity capital face an unreliable funding environment. Khan's diagnosis cuts to this core weakness: growth cannot rest on retail shoulders alone. Mutual funds, by pooling capital under professional management, convert fragmented retail savings into disciplined institutional flows — a transformation that changes not merely who invests, but how the market behaves.
The mechanism matters because mutual funds introduce intermediation where none effectively exists. A retail investor buying shares directly bears full information asymmetry, timing risk and behavioural bias; a unit holder in a professionally managed fund delegates those burdens to asset managers bound by fiduciary and regulatory obligations. This shift does not eliminate risk, but it redistributes it more rationally across diversified portfolios. More importantly, it creates a class of institutional counterparties whose trading is research-driven rather than sentiment-driven, which in turn improves liquidity quality and reduces the whipsaw dynamics that have long characterised the Dhaka and Chittagong exchanges.
Why Retail Reliance Creates Fragility
Retail-heavy markets are not inherently defective, but they are structurally fragile in specific, predictable ways. Individual investors tend to concentrate holdings, react to unverified news, and exit positions during drawdowns precisely when liquidity is most needed. In Bangladesh, this pattern has repeatedly produced sharp index swings disconnected from underlying corporate fundamentals. When institutional investors hold meaningful positions, they provide counter-cyclical liquidity and a stabilising bid during panic episodes, because their mandates and time horizons differ from those of retail traders. Khan's emphasis on widening the investor base is therefore not a rhetorical flourish but a direct response to a documented fragility.
There is also a governance dimension that rarely receives sufficient attention. Institutional investors, particularly mutual funds with published mandates and fiduciary duties, exercise voting rights and engage with issuers on disclosure quality. Their presence raises the cost of poor corporate governance because they can and do escalate concerns through formal channels. In a market where minority shareholder protection has historically been uneven, this monitoring function carries value beyond price stability. The commission's push for institutional participation thus doubles as an indirect corporate governance reform, disciplining issuers through the credible threat of informed, organised capital withdrawing or voting against management.
The Institutional Investor Multiplier
Institutional participation generates compounding benefits that extend well beyond the trading floor. Pension funds, insurance companies and asset managers bring actuarial and research capabilities that raise the analytical standard of the entire market. Their presence attracts custodians, brokers and research houses that serve institutional clients, deepening the financial services ecosystem. Over time, this ecosystem supports derivative markets, bond market development and structured products — all of which remain underdeveloped in Bangladesh. Each layer of institutional infrastructure makes the next layer viable, creating a multiplier effect that retail-only markets simply cannot replicate.
Khan's framing implicitly acknowledges this sequencing logic. Mutual funds are the entry point because they are accessible to retail savers while operating under institutional discipline. A saver who would never negotiate a custody arrangement can nonetheless participate in professionally managed portfolios, and the aggregate effect of millions of such decisions is a market with a genuinely institutional character. The regulatory task, as the commission appears to recognise, is to design rules that make this transition attractive to asset managers while protecting unit holders from conflicts of interest and operational failure.
Inside the Mutual Fund Rules, 2025 Review
The consultation centred on a formal presentation by Md Mahmoodul Hoque, executive director of the BSEC, titled "Review on the Bangladesh Securities and Exchange Commission (Mutual Fund) Rules, 2025." The framing of the session as a review rather than a drafting exercise is significant: it signals that the commission views the existing rules as a working foundation requiring refinement, not replacement. Stakeholders were invited to identify provisions that impede market development, and Khan committed the commission to considering amendments grounded in international best practice alongside the recommendations received. This consultative posture is itself a departure from more prescriptive regulatory traditions.
The breadth of attendance reinforces the seriousness of the exercise. Trustees, asset management companies, custodians and both exchanges were present, meaning the discussion spanned the full operational chain of the mutual fund industry. Each participant class holds distinct concerns: trustees focus on unit holder protection and compliance oversight, asset managers on product flexibility and distribution economics, custodians on operational standards and settlement efficiency, and exchanges on listing and trading infrastructure for fund units. A rules review that engages all of these perspectives simultaneously is more likely to produce a coherent framework than one drafted in isolation.
What a Rules Review Actually Changes
Mutual fund rules govern the entire lifecycle of a collective investment scheme, from authorisation and trustee appointment through valuation, disclosure, distribution and winding up. Small textual adjustments in such rules can have outsized market effects. A relaxation of eligibility criteria for asset managers, for instance, could expand the number of sponsors; a tightening of valuation norms could improve NAV accuracy and investor trust; revised fee caps could shift the economics of distribution. The commission's review therefore touches the commercial viability of the industry as much as its regulatory compliance, which explains why asset managers and trustees engaged so directly with the process.
International best practice offers a useful benchmark but not a template. Jurisdictions with deep mutual fund industries — India, Malaysia, and mature Western markets — developed their frameworks alongside particular tax regimes, distribution channels and investor demographics. Bangladesh's circumstances differ: financial literacy is uneven, distribution infrastructure is concentrated in urban centres, and the tax treatment of collective investment vehicles has historically influenced product design. A credible review must therefore translate international principles into locally workable provisions, which is precisely the balancing act Khan described when he spoke of amendments based on best practice and stakeholder recommendations together.
The Assurance of Regulatory Restraint
Khan's assurance that the commission would not make unreasonable or unjustified decisions deserves careful reading. In emerging markets, regulatory unpredictability is itself a risk factor: investors discount valuations when they cannot forecast the rules of the game. By explicitly asking stakeholders to have confidence in the commission's intentions, Khan was addressing a credibility gap that has historically deterred institutional capital. The statement functions as a commitment device, raising the reputational cost of arbitrary intervention and signalling that the review process will be evidence-led rather than reactive to short-term political or market pressures.
This matters enormously for mutual fund sponsors, who make multi-year investments in systems, personnel and distribution before a single unit is sold. Predictable regulation lowers their cost of capital and encourages product innovation. Conversely, a commission perceived as capricious will find few takers for complex or long-dated fund structures. The chairman's language therefore carries practical commercial weight: it tells prospective institutional entrants that the regulatory environment is stable enough to justify the sunk costs of market entry, which is a precondition for the institutional deepening he advocates.
Financial Literacy as Market Infrastructure
Financial literacy is often treated as a consumer protection afterthought, but Khan positioned it as core market infrastructure. His call for market institutions and stakeholders to collaborate in strengthening investors' knowledge and awareness reflects a recognition that mutual fund growth depends on investors who understand what they are buying. A saver who mistakes a fund for a fixed deposit will exit at the first NAV decline, destabilising the very vehicle meant to stabilise the market. Literacy is thus not charity but the demand-side foundation of the mutual fund industry, and its absence caps growth regardless of how well the supply side is regulated.
The collaborative framing is equally instructive. The commission alone cannot deliver financial literacy at scale; exchanges, asset managers, trustees and custodians all touch investors directly and possess distribution channels through which education can flow. By asking these institutions to work together, Khan is effectively proposing a shared infrastructure of investor education, with the regulator setting expectations rather than executing every programme. This distributed model is more sustainable than regulator-led campaigns because it embeds education within commercial relationships where investors actually make decisions, and it aligns institutional incentives with the goal of an informed client base.
From Awareness to Informed Decision-Making
Khan's phrasing distinguished carefully between knowledge and awareness, and the distinction is operationally meaningful. Awareness means investors know that mutual funds exist; knowledge means they understand how a fund's returns are generated, what risks they bear, and how fees affect outcomes. Bangladesh's challenge is less about awareness — mutual funds are widely known — and more about the depth of understanding required for sound decisions. A market full of aware but uninformed investors produces exactly the behaviour Khan seeks to avoid: chasing past performance, misjudging risk, and treating professional management as a guarantee rather than a service.
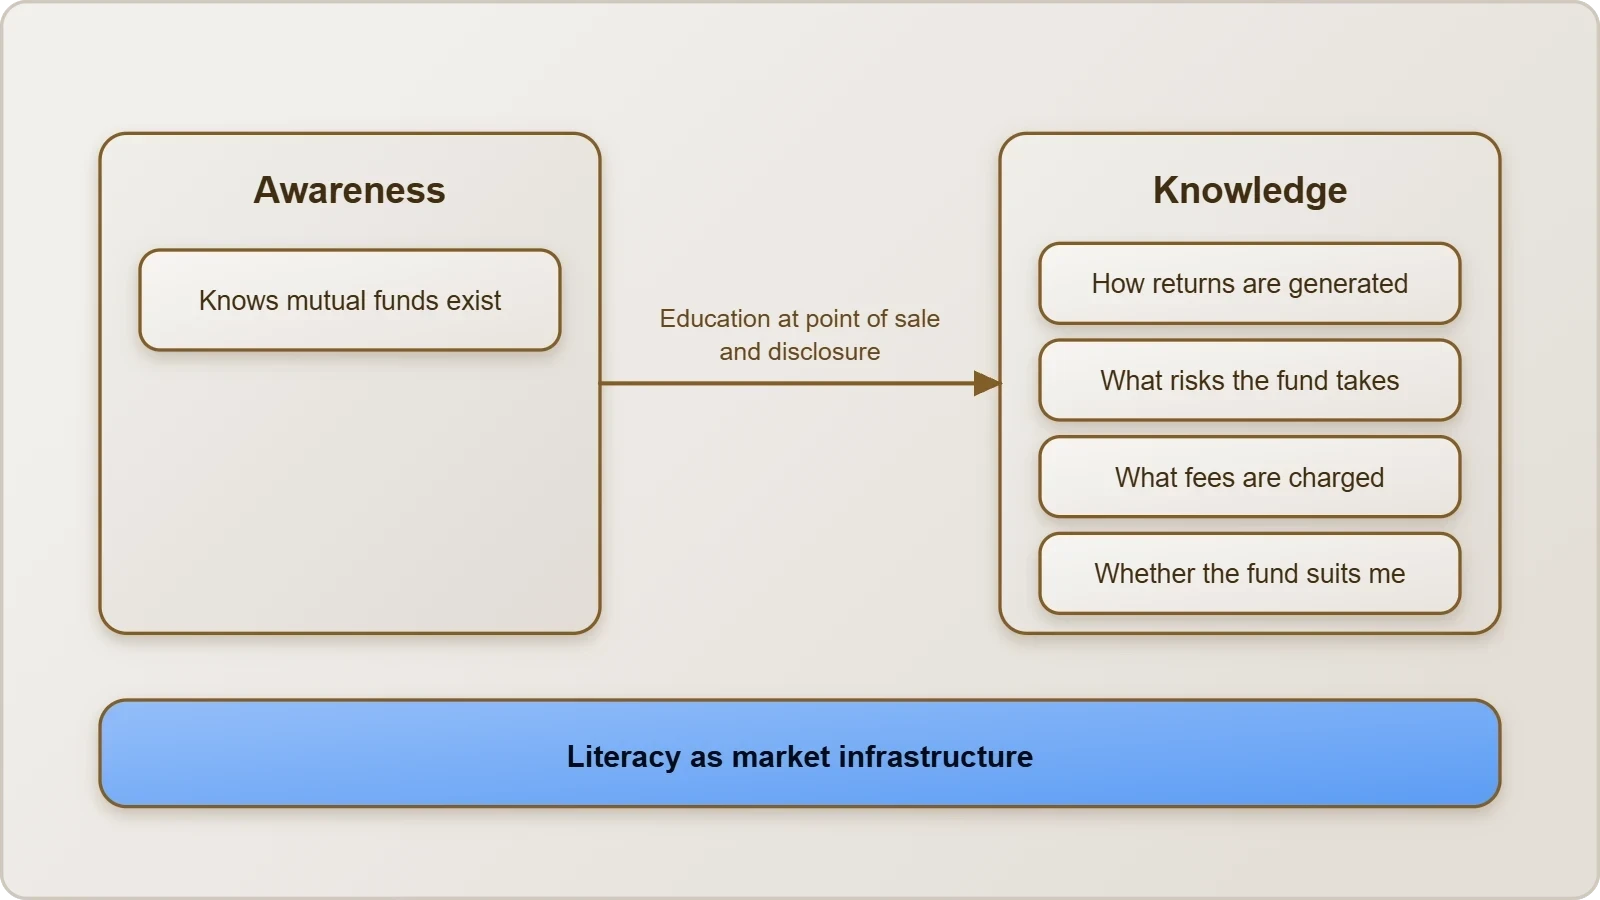
Closing this gap requires sustained, practical education delivered at the point of sale and reinforced through disclosure. Simplified key information documents, clear fee illustrations and standardised performance reporting all contribute, but they work only if investors possess the baseline literacy to interpret them. This is why the commission's collaborative call is well judged: asset managers have the client relationships, exchanges have the platforms, and trustees have the oversight mandate. Together they can deliver education where it is most effective, converting awareness into the informed decision-making that underpins a durable mutual fund industry.
- 01
- 02
- 03
- 04
We Also Published
Regulatory Philosophy and Market Confidence
The consultation reveals a regulatory philosophy that blends ambition with restraint. Khan wants a larger mutual fund sector and more institutional participation, but he explicitly disclaims arbitrary intervention and promises decisions that can be justified. This combination — developmental intent disciplined by procedural fairness — is precisely what institutional investors look for when assessing regulatory risk. Markets do not require regulators to be passive; they require them to be predictable, reasoned and open to evidence. The chairman's assurances, delivered before an audience of trustees, asset managers and exchange representatives, were calibrated to establish exactly that reputation.
Confidence, once established, compounds. Institutional investors who trust the regulatory process are more willing to commit capital, sponsor new funds and engage with issuers on governance. That engagement, in turn, improves disclosure and market integrity, which attracts further capital. The commission's consultative approach thus has a strategic dimension beyond the specific rules under review: it is building the reputational capital that a developing market needs to compete for institutional allocations. In a region where capital is mobile and regulatory environments are compared, this reputational asset is as valuable as any single rule amendment.
Balancing Development and Protection
Every mutual fund regulator walks a line between encouraging industry growth and protecting unit holders. Rules that are too permissive invite mis-selling, fee opacity and operational failures that destroy retail confidence for a generation; rules that are too restrictive make fund sponsorship uneconomic and leave the market retail-dominated by default. Khan's review appears to seek the productive middle: amendments that make the framework market friendly without diluting investor safeguards. The presence of trustees and custodians at the table is reassuring in this regard, since these parties have institutional incentives to defend unit holder interests against excessive commercial pressure.
The international best practice reference point provides a further check against regulatory capture. When amendments are benchmarked against jurisdictions with mature fund industries, departures from global norms require explicit justification. This disciplines the process and gives stakeholders a shared vocabulary for debate. It also signals to foreign institutional investors that Bangladesh's framework is legible within global standards, which reduces the due diligence burden of entering the market. The review's credibility will ultimately be judged by whether the resulting amendments are published, reasoned and consistently applied.
Signals for Domestic and Foreign Institutions
For domestic institutions, the consultation signals that the commission views them as partners in market development rather than merely regulated entities. Asset managers and trustees who contribute constructively to the review can shape rules that determine their own commercial futures, an opportunity that should not be underestimated in a market where regulatory engagement has historically been one-directional. For foreign institutions, the signal is subtler but no less important: a regulator that consults openly, cites international benchmarks and pledges restraint is a regulator with whom long-term capital can do business. Both signals point toward a more institutional market character.
The practical test will come in the amendments themselves. Institutional investors will watch whether the revised rules simplify fund authorisation, clarify valuation and disclosure standards, and provide stable fee frameworks. They will also watch the commission's conduct after the rules are issued, since predictability is demonstrated through consistent enforcement rather than through consultation alone. If the review delivers on its promise, Bangladesh's mutual fund sector could begin to close the gap with regional peers, and the market's dependence on retail sentiment would gradually give way to a more balanced, institutionally anchored structure.
Implications for Bangladesh's Capital Market Trajectory
Bangladesh's capital market stands at a point where incremental reforms can produce disproportionate results. The mutual fund sector remains small relative to the size of the economy and the pool of household savings, which means the growth runway is substantial if the regulatory and distribution foundations are right. Khan's emphasis on widening the investor base, deepening institutional participation and improving financial literacy addresses the three binding constraints simultaneously. None of these levers works in isolation, but together they form a coherent strategy for transforming a retail-driven exchange into a market capable of financing long-term economic development.
The broader economic context reinforces the urgency. As Bangladesh's economy matures, its savings pool grows and its financing needs diversify beyond bank credit. Capital markets that can channel household savings into productive equity and debt instruments become essential infrastructure, and mutual funds are the most accessible bridge between the two. A well-regulated fund industry also supports pension and insurance sector development, since institutional asset managers provide the investment capability those sectors require. The consultation of 29 October 2026 is therefore best understood not as a technical rules review but as a step in building the financial architecture of a maturing economy.
Risks That Could Derail the Agenda
Optimism should be tempered by the obstacles that have slowed similar reforms elsewhere. Distribution remains concentrated in urban centres, limiting mutual fund reach to a fraction of the population. Tax treatment can undermine fund competitiveness relative to direct equity or bank deposits, and any adverse change could stall growth regardless of regulatory goodwill. Market volatility, if severe, can trigger retail redemptions that shrink fund assets precisely when institutional support is most needed. These risks are manageable but not trivial, and they require coordinated policy responses beyond the securities regulator's remit.
There is also the question of institutional capacity within the commission itself. A rules review of this scope demands analytical resources, market surveillance capability and enforcement follow-through. Khan's assurance of reasoned decision-making implicitly depends on the commission possessing the expertise to evaluate stakeholder recommendations and international benchmarks rigorously. Building that capacity is a slower, less visible task than amending rules, but it determines whether the amendments achieve their intended effect. Stakeholders who welcomed the consultative approach will ultimately judge it by the quality and consistency of implementation.
What to Watch Next
The next milestones are concrete and observable. Publication of the revised Mutual Fund Rules, 2025 will reveal whether stakeholder input translated into substantive change. Guidance on financial literacy collaboration will show whether the commission's call for joint effort produces institutional commitments or remains aspirational. And the pace of new fund authorisations will indicate whether asset managers regard the revised framework as commercially viable. Each of these signals can be tracked, and together they will determine whether the 29 October consultation marks a turning point or merely a well-attended meeting.
For investors and institutions alike, the appropriate posture is engaged vigilance. The direction of travel is clear and constructive: a regulator seeking to broaden the investor base, deepen institutional participation and modernise its rulebook. The execution will determine the outcome. Bangladesh's capital market has the savings base, the institutional infrastructure and now, apparently, the regulatory intent to support a more mature mutual fund industry. Whether that potential converts into durable growth depends on the discipline with which the commission follows through on the commitments articulated in Dhaka.
From our network :
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
RESOURCES
- Resources will be updated soon.
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments