When a major artificial intelligence listing dominates the financial press, the temptation for ordinary investors is to treat every other opportunity as background noise. That instinct deserves scrutiny. A November column from The Globe and Mail took the opposite tack, deliberately looking past the noise surrounding a prospective Anthropic initial public offering to nominate two stocks the author considers worth buying that month. The framing is instructive because it captures a recurring tension in equity markets: the gravitational pull of a marquee event versus the quieter, often more durable case for businesses already generating revenue and free cash flow.
What makes this item worth unpacking is less the identity of the two picks — the excerpt does not name them — and more the editorial logic it reveals. The author positions the Anthropic IPO as a spectacle that absorbs market attention, then argues that attention is a scarce resource misallocated by crowds. That is a classic contrarian posture, and it carries real analytical weight when valuations in a hot sector become detached from near-term earnings. The piece is explicitly an opinion column rather than financial advice, a distinction that matters enormously in an era when retail investors increasingly treat published commentary as actionable guidance.
The broader context is a market in which private AI champions command extraordinary private valuations while public investors wait for liquidity events. Anthropic, the maker of the Claude family of models, has been the subject of persistent IPO speculation as competition with OpenAI intensifies and compute costs mount. Against that backdrop, the Globe and Mail column functions as a reminder that public equity markets still contain businesses with audited financials, disclosed risk factors, and dividend histories — attributes a pre-IPO AI story cannot yet offer. The analysis below examines what this framing means for portfolio construction, how to read opinion-driven stock commentary responsibly, and why the "watch the spectacle, buy the boring" instinct has both merit and limits.
On This Page
- The Editorial Logic Behind Looking Past a Marquee IPO
- Reading Opinion Columns Without Mistaking Them for Advice
- Anthropic, Private AI Valuations, and the Public Market Gap
- Portfolio Construction When Headlines Compete for Capital
- Verification Habits for the Discerning Investor
- The Media Cycle, Retail Behavior, and Market Efficiency
- Practical Takeaways for the November Decision
- Conclusion: What the Column Actually Teaches
TL;DR A Globe and Mail opinion column chose two stocks to buy in November while the market fixated on a prospective Anthropic IPO, illustrating a contrarian editorial stance rather than a formal recommendation. The episode highlights the difference between attention-driven hype and fundamentals-driven investing, the risks of treating columnist picks as advice, and the structural gap between private AI valuations and public market disclosure. Investors should read such pieces as argument starters, verify every claim independently, and size positions according to their own risk tolerance rather than a headline's confidence.
The Editorial Logic Behind Looking Past a Marquee IPO
Financial journalism operates on attention economics, and few stories command attention like a hotly anticipated technology listing. When a company of Anthropic's profile edges toward public markets, editors know the topic will draw clicks, and columnists know their work will be read against that backdrop. The Globe and Mail piece exploits this dynamic deliberately: by framing two stock picks as the antidote to IPO fever, the author borrows the spectacle's gravity while redirecting it toward ordinary, already-listed businesses. That is a sophisticated rhetorical move, and it signals a publication willing to publish counter-programming rather than simply amplify the loudest story of the week.
There is a substantive argument buried in that framing. IPO frenzies tend to compress diligence timelines, because investors who fear missing out allocate capital before reading prospectuses. Meanwhile, established companies trading at reasonable multiples receive less scrutiny precisely because they are familiar. The columnist's implicit claim is that mispricing flourishes where attention is absent, a proposition consistent with decades of behavioral finance research on neglect and coverage gaps. Whether the two specific picks vindicate that claim is unknowable from the excerpt, but the reasoning pattern is worth recognizing because it recurs across market cycles and across publications.
Why Attention Scarcity Creates Opportunity
Markets are information-processing machines, but human attention remains the binding constraint. When a single event absorbs the collective gaze, the marginal analyst hour shifts away from everything else, and prices in neglected corners can drift from intrinsic value for extended periods. Academic work on investor attention, including research linking search volume and news flow to short-term price pressure, supports the intuition that visibility itself moves prices. A columnist who deliberately looks elsewhere is, in effect, betting that the crowd's peripheral vision is poor. That bet is not always right, but it is structurally sound when the neglected assets are liquid, well-covered by auditors, and generating cash.
The counterargument deserves equal weight. Attention gravitates toward IPOs for reasons beyond hype: new listings often sit at the frontier of technological change, and frontier exposure historically drives disproportionate long-run returns. Dismissing an entire category because crowds are excited about it risks conflating popularity with error. The disciplined position is neither reflexive contrarianism nor reflexive enthusiasm, but a willingness to underwrite specific businesses on specific numbers regardless of where the spotlight happens to point in any given month.
The Columnist's Pick as a Genre
Monthly stock-pick columns occupy a peculiar genre. They are shorter than research reports, more confident than they should be, and published on deadlines that preclude deep diligence. Their value lies less in the specific tickers than in the reasoning on display: which metrics the author weights, which risks are acknowledged, and how the thesis would be falsified. A reader who extracts the framework gains something durable; a reader who extracts only the ticker gains a position they cannot defend when the thesis breaks. The Globe and Mail piece, at least in its excerpted form, offers the frame — buy what the crowd ignores — without the supporting detail that would let a reader evaluate it.
This is not a criticism unique to one publication. The genre's constraints are structural. A columnist writing eight hundred words cannot replicate the scenario analysis, channel checks, and balance-sheet forensics that institutional research demands. What the genre can do is surface ideas for further investigation and model a way of thinking about market psychology. Treating it as a screening tool rather than a decision tool preserves its usefulness while avoiding its hazards.
Reading Opinion Columns Without Mistaking Them for Advice
The most important sentence in the source item may be the disclaimer: this is an opinion piece and not financial advice. That line is not boilerplate to be skimmed past. It marks a boundary between journalism and advisory services, and crossing that boundary carelessly has real consequences for portfolios. A columnist has no fiduciary duty to readers, no knowledge of their time horizons, tax positions, or liabilities, and no obligation to update a thesis when conditions change. A reader who converts a November pick into a January position without independent verification has imported someone else's conviction into a context it was never designed for.
Regulatory frameworks recognize this distinction. In most jurisdictions, personalized recommendations require licensing, suitability assessments, and documented rationale. General commentary published to a mass audience falls outside those requirements precisely because it cannot account for individual circumstances. The practical implication is straightforward: treat published picks as hypotheses, not instructions. A hypothesis can be tested against filings, earnings calls, and valuation models. An instruction can only be obeyed or ignored, and obedience without understanding is how retail investors end up holding positions they cannot justify when volatility arrives.
Separating Signal From Confidence
Columnists write with a confidence that the underlying evidence rarely supports. A phrase like "my top two stocks to buy" implies ranking and certainty, yet the same author would likely concede that any single month's outcome is dominated by noise. Research on forecast calibration consistently finds that confident language correlates poorly with accuracy, particularly in domains as noisy as equity returns. Readers who mentally discount the confidence while retaining the reasoning get more value from the genre than readers who take the tone at face value. The question to ask is never "what did the author pick?" but "what would have to be true for this pick to work?"
That reframing also protects against hindsight bias. When a pick performs well, the columnist's reasoning appears vindicated; when it fails, the failure is attributed to unforeseeable events. Neither interpretation is reliable without a pre-committed thesis and a defined falsification condition. Sophisticated readers impose that discipline themselves, writing down what they expect and why before the outcome is known. It is unglamorous work, but it converts casual reading into genuine learning.
The Role of Disclosure and Conflict
Publications vary in how transparently they disclose columnist positions, affiliate relationships, and editorial independence from advertising. Readers should look for those disclosures and weight the commentary accordingly. A columnist who owns the stock they recommend faces a different incentive structure than one who does not, even when both act in good faith. Similarly, a publication whose advertising base includes asset managers has structural pressures that may shape coverage emphasis, if not specific picks. None of this renders opinion columns worthless; it simply argues for reading them with the same skepticism applied to any other interested party's claims.
The Globe and Mail, as a major Canadian newspaper, operates within established editorial standards, and the excerpt carries an explicit advisory caveat. That is a baseline of professionalism worth acknowledging. But standards at the publication level do not substitute for diligence at the reader level. The final filter is always the investor's own verification, applied to primary sources rather than secondary commentary.
Anthropic, Private AI Valuations, and the Public Market Gap
Anthropic's position at the center of this story reflects a broader structural feature of the current technology cycle. The most valuable AI developers have remained private far longer than equivalent companies in previous cycles, sustained by enormous venture and strategic funding rounds. That has concentrated exposure to frontier AI among private investors and left public market participants with indirect routes: cloud providers, chip designers, and infrastructure suppliers. When IPO speculation surfaces, it represents the market's appetite for direct exposure finally meeting a potential supply. Whether that supply arrives on the timeline rumor suggests is another matter entirely.
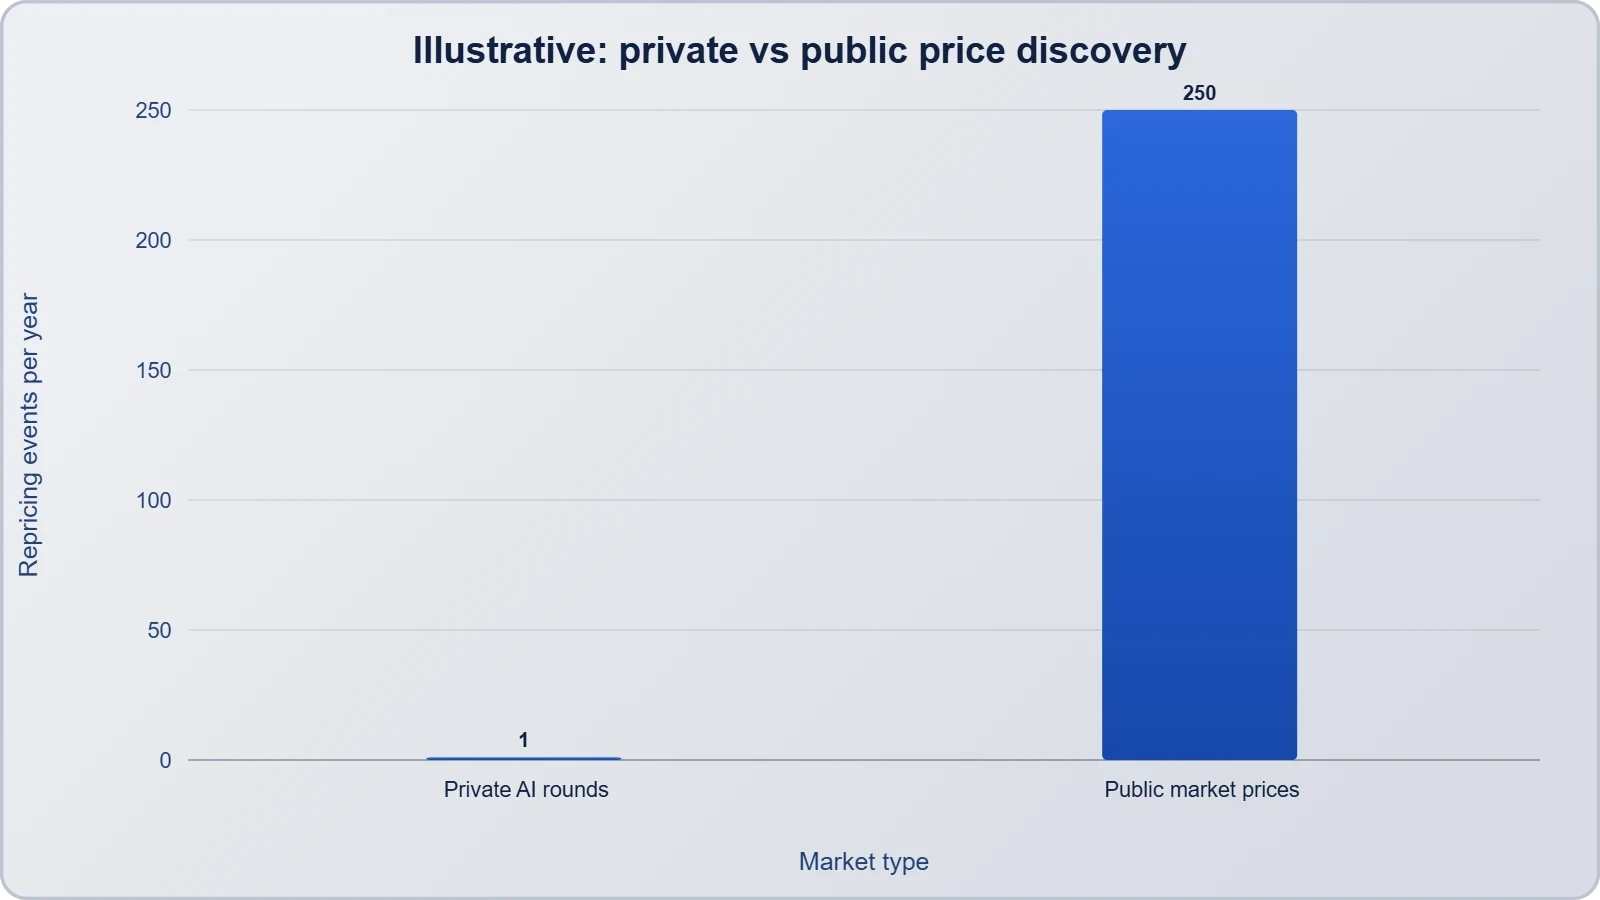
The valuation gap between private and public AI assets is not merely a curiosity. Private marks are set in negotiated rounds with limited liquidity and infrequent price discovery, while public marks update continuously against disclosed financials. Comparing the two requires care, because a private valuation reflects terms, preferences, and investor composition that public multiples do not capture. Investors who anchor their expectations for a future IPO on the last private round may be surprised by how public markets price the same business once scrutiny, lock-up dynamics, and quarterly reporting obligations enter the picture.
What an AI Listing Would Actually Change
A successful Anthropic listing would alter the competitive landscape in several concrete ways. It would create a public currency for acquisitions and employee compensation, impose quarterly disclosure discipline on a company that has operated with considerable opacity, and give retail investors a direct vehicle for expressing views on frontier model development. It would also subject the company to the full apparatus of securities regulation, including insider trading rules, material disclosure obligations, and shareholder litigation risk. Those constraints are not incidental; they shape strategy, and competitors who remain private retain flexibility that public peers surrender.
For investors in already-listed technology companies, the effect is more ambiguous. A high-profile AI listing could lift sentiment across the sector, drawing capital and attention that benefits adjacent businesses. It could also drain liquidity from smaller names as portfolios rebalance toward the new entrant. Historical precedent from other landmark listings suggests both effects occur, with the net result depending heavily on the valuation at which the new shares debut and the macro environment prevailing at the time.
Why the Columnist's Alternative Deserves a Hearing
Given all that uncertainty, the case for looking at established businesses has practical appeal. A company with a decade of audited results, a disclosed customer base, and a track record of capital allocation offers something an IPO candidate cannot: evidence. That evidence can be wrong about the future, but it is at least real about the past. In a market where narrative premiums have grown large, the discipline of paying for demonstrated cash flow rather than projected possibility has historically offered a margin of safety, albeit at the cost of missing the most spectacular winners.
The columnist's framing implicitly accepts that trade-off. It does not claim the two picks will outperform an AI listing; it claims they are worth considering while the crowd looks elsewhere. That is a modest, defensible proposition. Investors who internalize the modesty while extracting the analytical habit — look where coverage is thin, verify what you find — will benefit regardless of whether the specific picks prove prescient.
Portfolio Construction When Headlines Compete for Capital
Every allocation decision is implicitly a decision about what to ignore. A portfolio that chases each month's most discussed opportunity will accumulate positions with no coherent thesis, high turnover costs, and exposure concentrated in whatever narrative dominated at purchase. A portfolio built around explicit criteria — valuation bands, quality thresholds, position sizing rules — can absorb new ideas without being driven by them. The Globe and Mail column, whatever its specific picks, illustrates the value of having a framework that determines what enters the portfolio rather than letting the news cycle decide.
Position sizing deserves particular attention in this context. A columnist's pick arrives without a recommended weight, which means the reader must supply one. Standard practice ties position size to conviction and to the downside scenario rather than the upside story. A stock that could plausibly halve deserves a smaller allocation than one with a narrower range of outcomes, regardless of how compelling the narrative. Investors who size by excitement rather than by risk discover their error precisely when it is most expensive to correct.
Diversification Across Attention Regimes
Markets cycle between regimes where momentum dominates and regimes where valuation reasserts itself. A portfolio tilted entirely toward either extreme will experience periods of severe underperformance. Holding some exposure to high-growth, narrative-driven names alongside cash-generative, reasonably valued businesses smooths the ride without requiring perfect timing. The columnist's instinct to look past the IPO is, in portfolio terms, a call for balance rather than a call for wholesale abandonment of growth exposure. That distinction is frequently lost when contrarian arguments are compressed into headlines.
Rebalancing discipline operationalizes the balance. When one sleeve outperforms dramatically, trimming it and adding to the laggard enforces the contrarian logic mechanically, without requiring a forecast. The approach has well-documented limitations, including tax consequences and the risk of adding to genuine value traps, but it prevents the drift toward concentration that unchecked enthusiasm produces. For readers inspired by a contrarian column, a rebalancing rule is a more durable takeaway than any individual ticker.
Liquidity, Taxes, and the Cost of Acting on Ideas
Acting on a monthly column carries frictions that the column never mentions. Commissions, bid-ask spreads, and capital gains taxes all reduce the return available from any idea, and short holding periods amplify their effect. An investor who rotates positions monthly based on published picks may generate substantial activity while capturing little of the underlying thesis, which typically requires quarters or years to play out. The friction argument favors fewer, better-researched positions over frequent rotation driven by external prompts.
Liquidity matters most in stress. Positions in thinly traded names can be difficult to exit when sentiment turns, and the same attention dynamics that create opportunity on the way in can reverse violently on the way out. Established large-cap businesses generally offer deeper markets and more orderly exits, which is part of why the columnist's alternative to an IPO spectacle has practical appeal for individual investors with limited ability to absorb slippage.
- 01
- 02
- 03
- 04
Verification Habits for the Discerning Investor
The gap between reading a stock pick and acting on it responsibly is filled by verification. That process begins with primary documents: annual reports, quarterly filings, proxy statements, and earnings call transcripts. It continues with competitive analysis, including how the business's advantages might erode and what management has said about capital allocation. None of this guarantees a good outcome, but it converts an inherited opinion into a personal thesis, which is the minimum standard for deploying one's own capital. The Globe and Mail excerpt, by design, provides none of this scaffolding, and readers must supply it.
Verification also means checking the arithmetic behind any claim. Valuation multiples, growth rates, and margin assumptions can be recomputed from filings, and doing so often reveals that a compelling narrative rests on generous extrapolation. The exercise is tedious, but it is precisely the tedium that separates informed conviction from borrowed enthusiasm. Investors who cannot articulate the bear case for their own holdings have not finished the work, regardless of how persuasive the original column was.
Building a Personal Checklist
A repeatable checklist reduces the influence of mood and headline pressure. Reasonable items include: does the business generate free cash flow, and is it growing? Is the balance sheet capable of surviving a downturn without dilution? Is the valuation defensible under conservative assumptions? What would have to happen for the thesis to be wrong, and how would I know? Answering these questions before purchase creates a record that can be reviewed later, turning each position into a learning opportunity rather than an isolated bet.
The checklist should also include a source audit. Where did this idea originate, what does the source gain from my attention, and what would a skeptical analyst say? These questions are not cynical; they are the minimum due diligence for anyone whose savings are at stake. Applied consistently, they filter out most of the noise that competes for investor attention each month.
When to Ignore the Crowd Entirely
There are moments when the contrarian instinct should be overridden. If a new technology genuinely restructures an industry, the businesses at its center may deserve premium valuations despite the crowd's enthusiasm, and avoiding them out of reflexive skepticism can be costly. The discipline is to distinguish between hype about a category and evidence about a specific business. Anthropic's technology may well justify extraordinary value; the question is whether any given entry price leaves room for error. That question cannot be answered by contrarianism alone.
Conversely, there are moments when the crowd is simply wrong, and the neglected corner contains genuine bargains. Recognizing which moment one is in requires the same fundamental work regardless of direction. The columnist's contribution is to remind readers that both possibilities exist simultaneously, and that attention is not the same as analysis.
The Media Cycle, Retail Behavior, and Market Efficiency
Financial media does not merely report on markets; it participates in them. Coverage influences flows, flows influence prices, and prices influence subsequent coverage, creating feedback loops that can persist longer than fundamentals justify. Research on retail trading behavior has documented elevated volume and volatility following prominent media mentions, particularly for names with limited prior coverage. Understanding this dynamic does not require cynicism about journalists, most of whom work diligently under tight deadlines. It requires recognizing that the information ecosystem itself has mechanical effects on prices.
For the individual investor, the practical response is to separate the informational content of a piece from its market impact. A column may contain a genuinely useful insight while also moving the stock it discusses. Both things can be true, and the second does not invalidate the first. What matters is whether the insight survives independent scrutiny after the attention effect fades. Ideas that require continued media coverage to work are not investments; they are momentum trades wearing an analytical costume.
How Retail Flows Amplify Headline Effects
Retail participation has grown substantially as commission-free trading and mobile platforms have lowered barriers. That growth has changed the microstructure of how news transmits into prices. A widely read column can now generate measurable order flow within hours, particularly in stocks with high retail ownership. The effect is usually temporary, but it can create entry points for patient buyers or exit opportunities for holders, depending on direction. Sophisticated participants anticipate these flows; ordinary investors are more often caught in them.
Recognizing the pattern allows for better timing discipline. Buying immediately after a favorable mention means paying the attention premium; waiting for it to decay often yields a better entry, provided the underlying thesis remains intact. The same logic applies in reverse for unfavorable coverage. Patience is not merely a virtue in this context; it is a measurable source of return.
What Efficiency Arguments Miss
Efficient market theory holds that publicly available information is rapidly incorporated into prices, which would render published stock picks largely useless as a source of excess return. The theory has substantial empirical support, yet anomalies persist, particularly in less-covered segments of the market. The reconciliation is that efficiency varies by market segment and by the cost of acquiring and processing information. Where coverage is thin and analysis is expensive, mispricing can survive; where coverage is dense, it rarely does.
This nuance supports the columnist's implicit strategy. Looking where attention is scarce is a bet on segment-level inefficiency rather than a rejection of market efficiency altogether. It is a more defensible position than either extreme, and it explains why contrarian ideas sometimes work without implying that markets are systematically irrational.
We Also Published
Practical Takeaways for the November Decision
For readers encountering this column in real time, the actionable content is a set of questions rather than a set of tickers. What are the two businesses, and do their financials support the author's confidence? How does the Anthropic IPO timeline affect the competitive landscape for those businesses? What position size would allow for being wrong without impairing the broader portfolio? Answering these questions requires work the column cannot do on the reader's behalf, and that work is the actual investment process. The column is a prompt; the portfolio decision belongs to the reader.
It is also worth noting what the excerpt does not contain. There is no valuation analysis, no discussion of risks, no time horizon, and no performance track record for prior picks. Those omissions are typical of the format but should temper any impulse toward immediate action. A reader who treats the absence of detail as an invitation to investigate is using the genre correctly; one who treats it as permission to buy is not.
Position Sizing and Risk Budgets
A disciplined approach begins with a risk budget expressed in percentage terms. If a single position losing half its value would cause unacceptable portfolio damage, the position is too large regardless of conviction. Common frameworks cap individual positions at a small fraction of total capital and aggregate exposure to any single theme at a somewhat larger fraction. These limits are arbitrary in detail but essential in principle, because they prevent any single idea, however well researched, from becoming an existential threat to the portfolio.
Risk budgets also clarify when to act. If a new idea fits within existing limits without displacing higher-conviction holdings, it can be considered on its merits. If it requires selling something better understood, the bar rises considerably. Most published picks fail this test, which is itself a useful filter.
Reviewing the Thesis Over Time
Positions require maintenance. Quarterly results, management changes, competitive developments, and shifts in the macro environment all provide occasions to revisit the original thesis. A disciplined review asks whether the reasons for ownership remain intact and whether the valuation still offers an acceptable expected return. Positions that fail review should be reduced or exited, regardless of the original source of the idea. Loyalty to a columnist is not an investment strategy.
Recording the review process creates an institutional memory for personal portfolios. Over time, patterns emerge: which types of ideas work, which fail, and where the investor's own judgment is systematically biased. That self-knowledge compounds more reliably than any single stock pick, and it is available to anyone willing to keep honest records.
Conclusion: What the Column Actually Teaches
The enduring value of the Globe and Mail item lies in its demonstration of editorial independence from the news cycle. By choosing to write about two ordinary stocks while the market watched an AI listing, the author modeled a habit of mind that serves investors well: deciding what deserves attention rather than accepting the agenda handed to you. That habit is more portable than any recommendation. It applies whether the spectacle of the moment is an IPO, a meme stock, or a macroeconomic scare, and it scales from a single position to an entire portfolio.
The caveats remain essential. Opinion columns are not advice, excerpts are not analysis, and confidence is not evidence. Readers who internalize both the lesson and the caveats gain a durable framework for processing financial media. Those who take only the tickers inherit someone else's conviction without the reasoning that sustains it. The difference between those two outcomes is not intelligence but process, and process is available to anyone willing to do the work.
From our network :
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
RESOURCES
- Resources will be updated soon.
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments