A single sentence from the Associated Press — that the major United States stock indexes closed lower on Tuesday, November 3, 2026 — carries far more analytical weight than its brevity suggests. On the surface, it is a routine market bulletin: the Dow, the S&P 500, and the Nasdaq Composite all finished the session in negative territory, and the wire service recorded that outcome without attaching point moves, percentage declines, or any explanation of what drove the selling. Yet the very sparseness of the dispatch is itself a signal worth reading carefully, because it tells us that the day's decline was not dramatic enough to demand a narrative, nor trivial enough to ignore.
Financial markets are storytelling machines, and the stories they tell on any given day are shaped as much by what reporters leave out as by what they include. When a closing report omits sector breakdowns, individual stock moves, and macro catalysts, the most defensible interpretation is that the decline was broad, orderly, and unremarkable — the kind of quiet drift lower that happens when investors trim exposure, wait for data, or simply lack a reason to buy. This analysis treats that omission not as a gap to be filled with speculation, but as evidence about the character of the session itself.
What follows is a structured reading of the November 3, 2026 close: how to interpret a bare-bones market report, why the absence of detail matters, how such sessions fit into the broader rhythm of equity markets, and what disciplined investors should take away from a day when the indexes simply went down. The goal is not to invent numbers the source never provided, but to extract genuine meaning from a minimal data point and place it within the professional frameworks that govern how markets are understood.
On This Page
TL;DR The Associated Press reported that major US stock indexes closed lower on Tuesday, November 3, 2026, without specifying point or percentage changes, individual stock performance, or market-moving factors. Read professionally, this minimal dispatch indicates an orderly, broad-based decline rather than a crisis event — the kind of session driven by routine positioning, caution ahead of catalysts, or simple absence of buying interest. The absence of detail is informative: dramatic selloffs generate rich narratives, while quiet declines generate terse ones. Investors should treat such reports as confirmation of direction, not as a complete picture, and should consult primary market data for magnitude and context.
The Anatomy of a Minimal Market Report
A wire-service closing report is a peculiar literary form. It exists to answer one question — where did the market finish? — and it answers that question with the smallest possible expenditure of words. The November 3, 2026 dispatch from the Associated Press follows this template precisely: it identifies the day, the direction, and the benchmarks, then stops. There is no color, no attribution to traders, no reference to earnings or economic releases. Understanding why such reports look the way they do is the first step toward extracting meaning from them.
What the Report States and What It Withholds
The report states four facts with certainty: the date (Tuesday, November 3, 2026), the geography (United States), the instrument class (major stock indexes), and the direction (lower). Everything else — magnitude, breadth, sector leadership, volume, volatility — is absent. In journalism terms, this is a "bare bones" closing item, typically filed when the move is unremarkable or when fuller coverage is handled elsewhere. The withholding is not accidental; it reflects editorial judgment about newsworthiness.
For analysts, the key inference is that the decline did not cross the threshold that triggers expanded coverage. Major outlets typically attach percentage moves and explanatory context when indexes fall sharply, when a single catalyst dominates, or when volatility spikes. A terse report therefore implies a moderate, diffuse decline. It also implies that no single narrative — a Fed surprise, a geopolitical shock, a mega-cap earnings miss — was compelling enough to anchor the story of the day.
Why Brevity Itself Is a Data Point
Market communication follows an inverse relationship between drama and detail: the more dramatic the session, the richer the reporting. A crash produces thousands of words; a quiet drift produces dozens. This means the length and texture of a closing report can be read as a rough proxy for the severity of the move. The November 3 item sits at the sparse end of that spectrum, which argues against interpreting the session as a crisis.
There is a second layer to this. Wire services operate under strict standards of factual accuracy, and they avoid asserting causes they cannot verify. When the cause of a decline is unclear or contested, the safest professional choice is to report direction and omit explanation. The absence of stated causes may therefore reflect genuine ambiguity about what moved the market — a condition common on days when selling is driven by positioning flows, rebalancing, or simple sentiment drift rather than identifiable news.
Contextualizing a Lower Close in Modern Equity Markets
To understand what a lower close means, it helps to recall the structural backdrop of equity markets in the mid-2020s. US indexes have historically spent roughly half of all trading days finishing lower, which makes a down day the statistical norm rather than an anomaly. The S&P 500, the Dow Jones Industrial Average, and the Nasdaq Composite each carry distinct sector weights and behavioral profiles, and their collective decline on a given day tells us something about the breadth of sentiment rather than the fate of any single company.
The Three Benchmarks and Their Divergent Personalities
The Dow, a price-weighted index of thirty large-capitalization names, tends to move more slowly and reflect industrial and financial sentiment. The S&P 500, weighted by market capitalization across roughly five hundred companies, serves as the broadest gauge of large-cap health. The Nasdaq Composite, heavily tilted toward technology and growth, amplifies moves in the innovation economy. When all three close lower together, the most reasonable inference is a market-wide shift in risk appetite rather than a sector-specific event.
This distinction matters because the report does not tell us whether the decline was uniform or driven by one benchmark dragging the others. A Nasdaq-led selloff has different implications for growth investors than a Dow-led retreat has for value and dividend portfolios. Without the breakdown, the prudent assumption is broad participation — but the professional response is to verify against index-level data before drawing portfolio conclusions.
What a Typical Down Day Looks Like Statistically
Historical data on US equities shows that daily moves cluster tightly around zero. Most sessions end within one percent of the prior close in either direction, and declines of that magnitude are routine. The distribution has fat tails, meaning large moves occur more often than a normal curve would predict, but the overwhelming majority of trading days are unremarkable. A terse wire report is consistent with a session in the middle of that distribution.
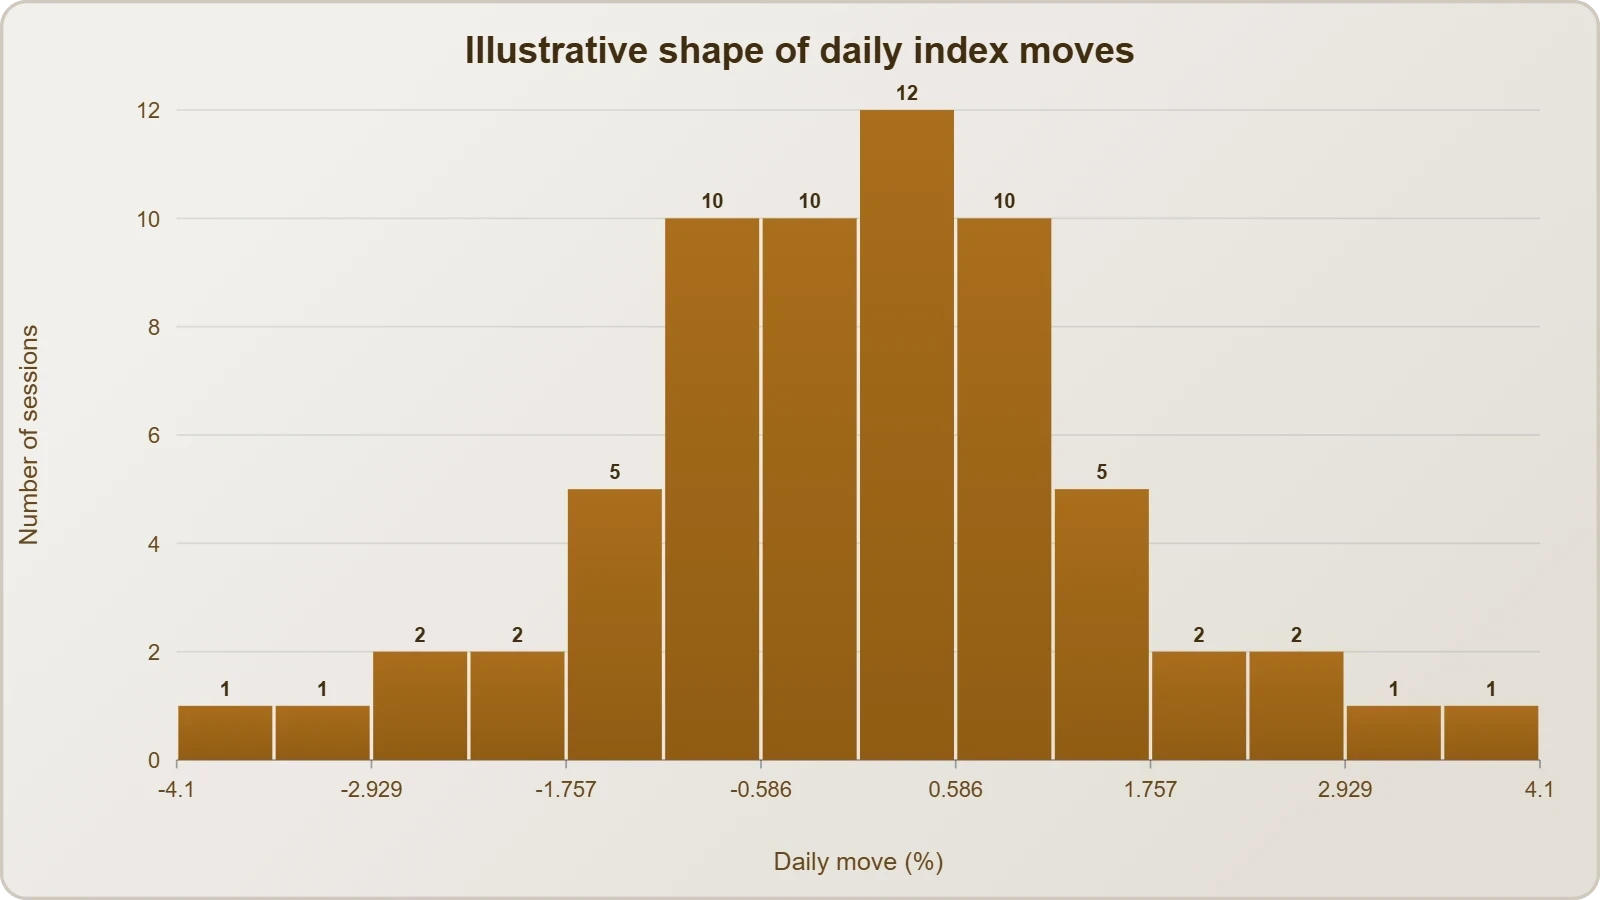
Volatility regimes also shape how declines are experienced. In low-volatility periods, a modest down day feels like noise; in high-volatility periods, the same move can feel like the start of something larger. Because the report provides no volatility context, investors should anchor their interpretation to prevailing conditions — the VIX level, recent ranges, and the calendar of upcoming catalysts — rather than to the bare fact of a decline.
Interpreting the Absence of Market-Moving Factors
The most analytically interesting feature of the dispatch is what it does not say about causes. Financial journalism, at its fullest, explains why markets moved: an inflation print, a central bank signal, an earnings surprise, a geopolitical rupture. The November 3 report offers none of these. That silence invites two readings. The first is that no single identifiable catalyst existed, and selling was driven by diffuse forces. The second is that a catalyst existed but was considered insufficiently significant to warrant mention in a brief closing item.
Catalyst-Driven Versus Flow-Driven Sessions
Markets move for two broad categories of reasons. Catalyst-driven moves trace to identifiable news: data releases, policy decisions, corporate events, or geopolitical shocks. Flow-driven moves trace to mechanics: portfolio rebalancing, month-end positioning, options expiration, index reconstitution, or risk-parity adjustments. Flow-driven sessions often lack a clean narrative, which is precisely why they generate terse reports. The absence of stated causes on November 3 is consistent with a flow-driven day.
This distinction has practical value for investors. Catalyst-driven declines often warrant a reassessment of assumptions, because new information has entered the market. Flow-driven declines usually do not, because the underlying fundamentals are unchanged. Treating a flow-driven dip as though it were catalyst-driven leads to overreaction; treating a catalyst-driven decline as noise leads to complacency. The report alone cannot resolve which type of session occurred, but its sparseness tilts the probability toward flows.
The Calendar as a Silent Influence
Early November sits in a distinctive position on the market calendar. It follows the close of the third-quarter earnings season, arrives amid preparations for year-end positioning, and often precedes major central bank meetings and the release of key employment data. Investors frequently reduce risk ahead of such events, producing modest declines that carry no dramatic story. A lower close on November 3 fits comfortably within this seasonal pattern of cautious pre-catalyst positioning.
Tax considerations also play a role in the final months of the year, as investors harvest losses and rebalance taxable accounts. These activities generate selling pressure that is mechanical rather than conviction-driven. None of this can be confirmed from the dispatch itself, but the professional habit of situating a data point within its calendar context transforms a bare fact into a usable inference about market behavior.
We Also Published
- 01
- 02
- 03
- 04
From Headline to Portfolio Decision
A professional investor reading the November 3 dispatch faces a practical question: what, if anything, should change? The disciplined answer is almost always "nothing, yet." A single direction-only data point is insufficient to justify portfolio action. What it can do is prompt verification. The investor should check the actual percentage moves, examine breadth statistics, review sector performance, and confirm whether volume was elevated or subdued. Only after assembling that fuller picture does a decision become defensible.
Building a Verification Workflow
Verification begins with primary sources: exchange closing data, index provider summaries, and market data terminals. The next layer is breadth — how many stocks advanced versus declined, and whether the decline was concentrated in a few mega-caps or spread across the market. Sector performance reveals whether the selling targeted defensives, cyclicals, or growth. Volume confirms whether the move carried conviction. Each layer adds resolution to the blurry image the wire report provides.
This workflow matters because headlines are compressed representations of complex events. Treating a headline as the event itself is a category error. The report tells us the market went down; the data tells us how, where, and with what intensity. Investors who habitually move from headline to verification avoid the twin errors of overreaction and dismissal, and they build a more accurate mental model of market behavior over time.
Behavioral Discipline in the Face of Routine Declines
Behavioral finance research consistently shows that investors feel losses more acutely than equivalent gains, a phenomenon known as loss aversion. This asymmetry makes routine down days psychologically louder than they are statistically. A terse report that simply says indexes closed lower can trigger disproportionate anxiety if read without context. Recognizing this bias is the first defense against it, and anchoring interpretation to base rates — most days are unremarkable — is the second.
Discipline also means resisting the urge to construct narratives where none exist. The human mind craves explanation, and a bare fact invites speculation. But professional analysis requires distinguishing between what is known and what is inferred. On November 3, 2026, what is known is narrow: the indexes fell. What is inferred — an orderly, likely flow-driven session — should be held with appropriate humility and revised as better data arrives.
The Broader Significance for Market Communication
Beyond the specific session, the dispatch raises a broader question about how financial information reaches the public. Wire services are the connective tissue of market communication, and their editorial choices shape what millions of readers understand about the economy. When a report is minimal, readers who lack the tools to contextualize it may overinterpret or underinterpret the news. Financial literacy, in this sense, is partly the ability to read silences as well as statements.
Information Asymmetry and the Retail Investor
Professional traders have access to real-time data, analytics, and research that retail investors do not. A terse wire report widens this asymmetry, because it provides direction without magnitude or context. The retail reader sees "indexes closed lower" and must decide what it means without the surrounding apparatus. Bridging this gap is one of the central challenges of modern financial journalism and investor education alike.
The remedy is not necessarily longer wire reports but better interpretive habits among readers. Understanding base rates, knowing where to find primary data, and recognizing the difference between catalyst and flow are skills that can be learned. When readers possess these skills, a minimal report becomes a starting point for inquiry rather than a source of confusion. The dispatch's brevity, in this light, is an invitation to engage more deeply rather than a failure of coverage.
What This Session Teaches About Market Psychology
Quiet declines are instructive precisely because they lack drama. They reveal the market's default state: a continuous auction in which prices adjust to the aggregate of countless individual decisions, most of which are unremarkable. The absence of a headline-grabbing catalyst on November 3 suggests a market digesting information, repositioning, and waiting — behavior that is healthy and normal. Not every down day needs a villain, and not every decline signals a turning point.
This perspective is valuable for long-term investors, who are best served by treating daily fluctuations as noise around a trend rather than as verdicts on the future. The indexes closed lower on a Tuesday in November. The sun rose the next morning, the companies in those indexes continued to operate, and the market resumed its endless process of price discovery. That ordinariness is the real story, and it is worth understanding.
Key Takeaways and a Framework for Reading Market Headlines
The November 3, 2026 dispatch is a small artifact with a larger lesson. It demonstrates that market information arrives in layers, and that the outermost layer — a headline stating direction — is the least informative. The professional habit is to descend through the layers: from direction to magnitude, from magnitude to breadth, from breadth to cause, and from cause to implication. Each step requires effort, but each step reduces the risk of misreading the market's message.
A Repeatable Method for Investors
The method can be stated simply. First, note the direction and date. Second, retrieve the magnitude from primary data. Third, assess breadth and sector distribution. Fourth, identify whether the session was catalyst-driven or flow-driven. Fifth, decide whether the new information changes any underlying assumption. Only at the fifth step does portfolio action become relevant, and in most cases the answer will be no. This sequence converts a passive headline into an active analytical process.
Applied to November 3, the method yields a modest conclusion: the indexes fell, likely in an orderly fashion, without an identifiable catalyst, and probably without implications for long-term positioning. That conclusion is unexciting, which is precisely the point. Most market days are unexciting, and the discipline of treating them as such is what separates sustainable investing from reactive trading. The report's brevity, read correctly, is a reminder of that discipline.
Why Sparse Reporting Deserves Respect
It is tempting to criticize a minimal report as inadequate. But wire services operate under constraints of accuracy and editorial judgment, and a terse item can be an honest reflection of an unremarkable session. Respecting that honesty means not demanding narrative where none exists. The report did its job: it told us what happened. The rest — interpretation, context, and implication — is the reader's responsibility, and it is a responsibility worth taking seriously.
In the end, the comprehensive meaning of the source is not hidden in what it says but in how it says it. A lower close, reported plainly, is a snapshot of a market at work. It is neither a warning nor a reassurance. It is information, and like all information, its value depends on the sophistication of the reader. The investor who understands this will read the next terse dispatch with calm, curiosity, and the tools to look deeper.
From our network :
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
RESOURCES
- Resources will be updated soon.
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments