Bangladesh's readymade garment sector, the industrial spine of a $50 billion export economy, has once again become the stage on which the country's deeper macroeconomic anxieties are performed. When several hundred factories shuttered as wage protests entered a fourth consecutive day, the immediate story was one of labour unrest and disrupted production lines. Yet the more consequential narrative lies beneath the picket lines: an economy caught between genuinely encouraging external flows and a domestic investment engine that has all but stalled. Exports climbed six percent in the first four months of the fiscal year, remittances rose thirteen percent, and reserves have held relatively steady — figures that, taken alone, suggest resilience.
The trouble is that these headline numbers conceal a far more fragile internal reality. Private sector credit growth collapsed to a record low of 4.17 percent in September, a figure that, once adjusted for inflation near 8.5 percent, means real credit is actively contracting. Import payments are rising faster than the central bank can comfortably document, pressuring the taka and signalling that the external account is not as serene as the export figures imply. Economists quoted by The Daily Star describe the picture as mixed, and that word does considerable work: it acknowledges genuine strengths while refusing to let them mask unresolved structural weaknesses in banking, energy and business confidence.
What follows is a close reading of that fragile equilibrium — the mechanics of the garment unrest, the diagnostic value of each economic indicator, and the reform agenda that analysts argue cannot be postponed. The analysis draws on the assessments of four senior Bangladeshi economists, each of whom converges on a similar conclusion from a different angle: stabilisation without structural reform will not convert this uneven recovery into durable growth, and prolonged industrial disruption could tip a delicate balance in the wrong direction.
On This Page
- The Anatomy of the Garment Unrest and Its Economic Stakes
- Reading the Indicators: A Fragile and Uneven Recovery
- Private Sector Credit at 4.17 Percent: The Most Worrying Number
- The Reform Agenda: Four Priorities and a Graduation Window
- What the Unrest Means for the Recovery Trajectory
- Frequently Asked Questions
TL;DR Bangladesh's garment worker protests, now in their fourth day, have forced the closure of several hundred factories at a moment when the economy is already struggling with a fragile, uneven recovery. Exports (+6%) and remittances (+13%) look healthy, but private sector credit growth has fallen to a record low of 4.17%, inflation sits near 8.5%, and a weakening taka reflects mounting import payment pressure. Economists warn that prolonged unrest threatens production, delivery commitments and buyer confidence, and argue that wage grievances must be resolved through credible dialogue alongside deeper banking, revenue and competitiveness reforms.
The Anatomy of the Garment Unrest and Its Economic Stakes
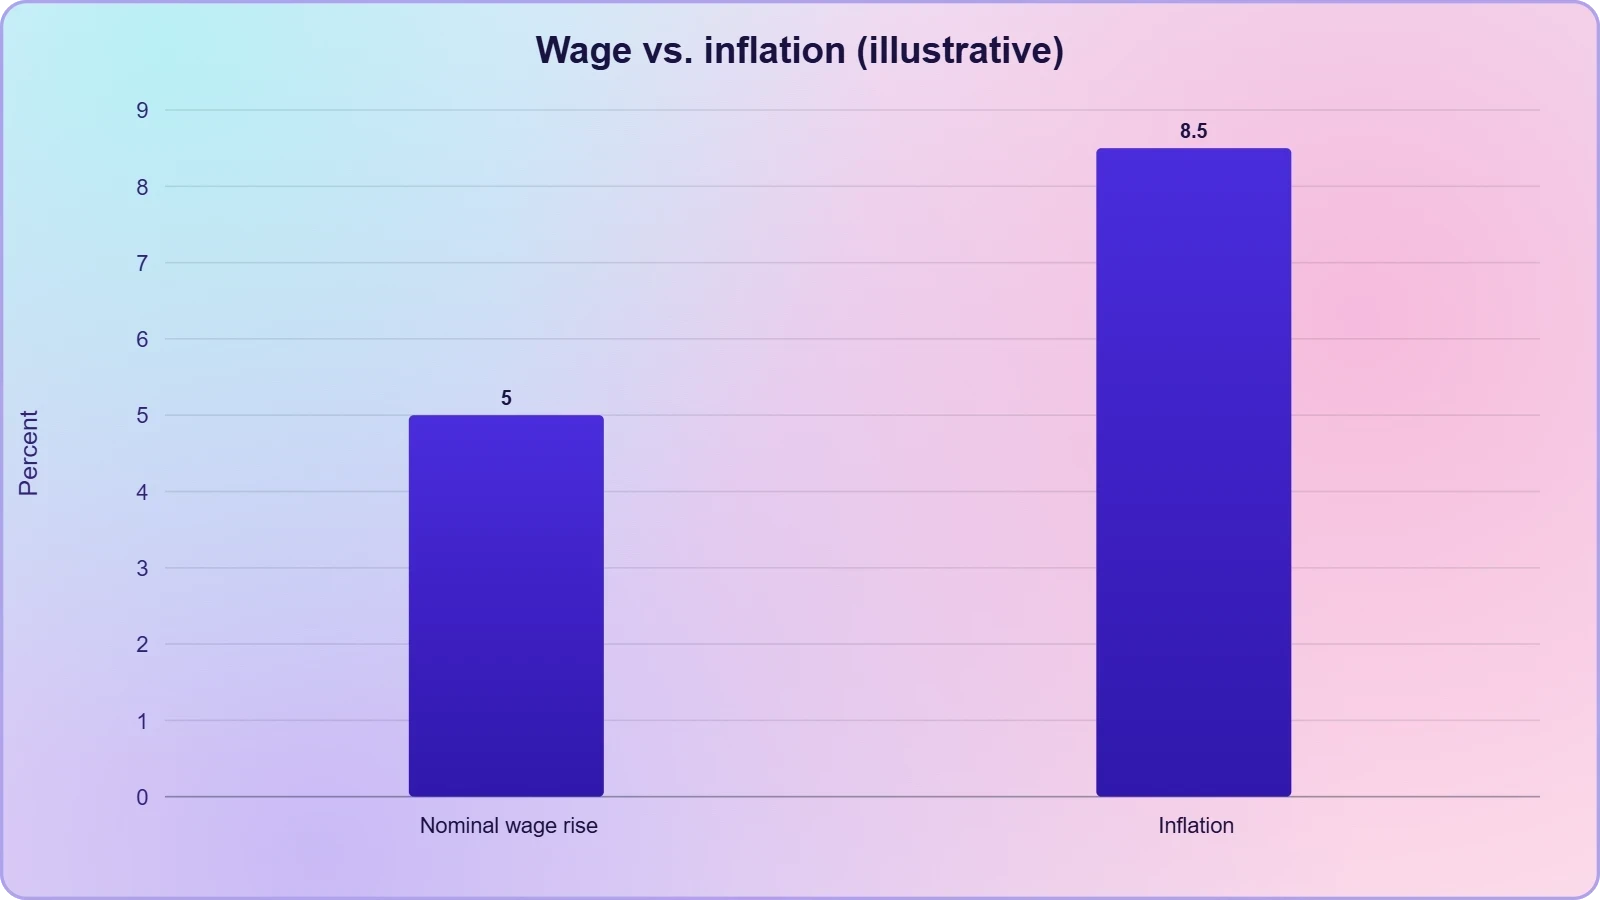
The protests that closed several hundred factories are not an isolated labour dispute but the visible expression of a cost-of-living squeeze that has been building for years. Garment workers, who form the backbone of Bangladesh's export workforce, have watched nominal wages erode against inflation that has hovered stubbornly near 8.5 percent. When the government moved to set a minimum wage, it was a recognition that the status quo had become untenable. Yet a wage floor alone cannot resolve the broader grievance architecture — the rising cost of food, housing and transport that determines whether a pay packet actually sustains a household.
Why Factory Closures Reverberate Beyond the Shop Floor
Each closed factory represents more than a lost production day. Bangladesh's garment industry operates on tight delivery schedules for international buyers whose sourcing decisions are highly sensitive to reliability. A single missed shipment can prompt a buyer to shift orders to Vietnam, India or Cambodia, and those orders rarely return quickly. The economists interviewed were unanimous on this point: unrest damages production, delivery commitments and, most importantly, buyer confidence — an intangible asset that takes years to build and weeks to destroy. The reputational cost compounds the immediate economic one.
There is also a domestic multiplier effect that rarely features in headline export statistics. Garment workers spend the overwhelming majority of their wages on food, rent and transport within local economies, so a shutdown suppresses demand in precisely the communities least able to absorb the shock. Mustafizur Rahman of the Centre for Policy Dialogue framed the stakes plainly: factory unrest is neither good for production nor for workers nor for exports, and it could negatively affect the overall economy. His welcome for the minimum wage was paired with a firm insistence that remaining legitimate grievances be addressed through dialogue rather than confrontation.
The Wage Question and the Limits of a Minimum Wage
Setting a minimum wage was necessary but insufficient, and the economists were careful to distinguish between the two. A statutory floor addresses the most acute dimension of worker grievance, yet it does not automatically restore purchasing power if inflation continues to outpace nominal gains. Nor does it resolve disputes over overtime, payment timing or workplace conditions that frequently sit behind industrial action. The consensus view is that a structured, credible dialogue mechanism — one that gives workers a genuine channel and gives employers predictability — is the only durable route to protecting both livelihoods and export competitiveness.
There is a competitiveness dimension that cannot be wished away. Bangladesh's garment advantage has historically rested on cost, and wage increases compress that advantage unless productivity rises in tandem. This is why the reform conversation and the wage conversation are inseparable: a better-paid workforce requires better infrastructure, more reliable energy and more efficient logistics to remain globally competitive. Framing the unrest purely as a law-and-order problem, or purely as a wage problem, misses the structural interdependence that the economists consistently emphasised in their assessments.
We Also Published
Reading the Indicators: A Fragile and Uneven Recovery
The economic data released alongside the unrest tells a story of two economies operating at different speeds. The external economy — exports, remittances, reserves — is performing with a resilience that surprises many observers. The domestic economy, by contrast, is characterised by anaemic investment, constrained credit and persistent price pressure. Understanding why these two halves diverge is essential to understanding why the recovery has been described as uneven rather than simply weak, and why the policy response has so far failed to translate external strength into domestic momentum.
Exports and Remittances: The Resilient Half
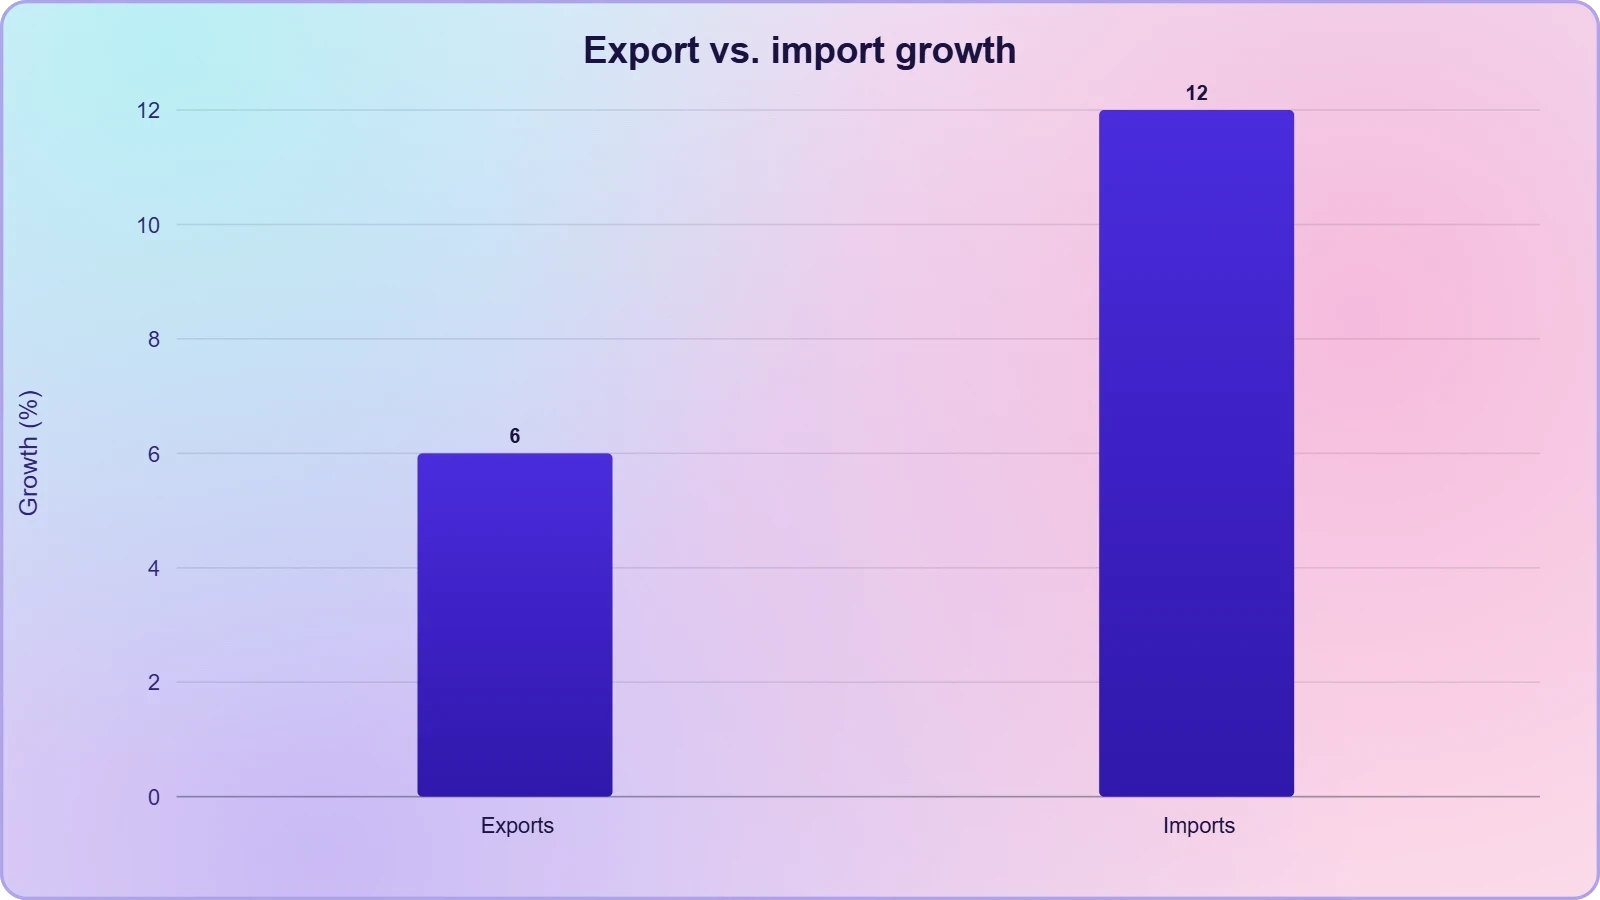
Export growth of six percent in the first four months of the fiscal year is a genuine achievement in a subdued global trade environment, even if it falls short of the double-digit target the government had set. Remittances rising thirteen percent provide a second pillar of external support, cushioning the current account and sustaining household consumption in regions with high out-migration. Foreign exchange reserves, while under pressure, have held up relatively well. Taken together, these flows explain why Bangladesh has avoided the acute balance-of-payments crises that have afflicted several comparable economies in recent years.
Yet the economists were careful not to over-read this strength. Export growth below target, however respectable, means the sector is not generating the surplus of jobs and foreign exchange that a double-digit trajectory would. Remittance growth, meanwhile, is partly a function of exchange-rate incentives rather than purely of higher overseas employment, which makes it a less reliable long-term engine. The external account, in short, is providing a buffer rather than a launchpad — buying time that must be used for reform rather than treated as evidence that reform is unnecessary.
Imports, the Taka and the Pressure Beneath the Surface
Import growth of twelve percent in July and August, set against export growth of six percent, sketches a trade dynamic that inevitably pressures the currency. Bankers report growing payment pressure weakening the taka against the dollar, and the central bank's delay in publishing the latest import payment figures has itself become a signal that the external account deserves scrutiny. A depreciating taka is not inherently harmful — it can support export competitiveness — but when it reflects financing strain rather than deliberate adjustment, it raises the cost of essential imports and feeds directly into domestic inflation.
The interaction between currency pressure and inflation is where the fragility becomes most acute. Bangladesh imports a substantial share of its fuel, machinery and intermediate goods, so a weaker taka raises production costs across the economy, including for garment manufacturers whose margins are already thin. This creates a feedback loop that the economists implicitly recognised: currency pressure raises input costs, input costs raise inflation, inflation erodes real wages, and eroded wages fuel the labour unrest that disrupts production and exports. Each link in that chain reinforces the next, which is precisely why partial interventions struggle to break it.
Private Sector Credit at 4.17 Percent: The Most Worrying Number
Of all the figures cited, the one that drew the sharpest concern was private sector credit growth of 4.17 percent in September. Ashikur Rahman, principal economist at the Policy Research Institute of Bangladesh, identified it as the most worrying indicator, and the reasoning is straightforward. With credit growing more slowly than inflation, it is shrinking in real terms. A financial system that is not expanding credit to businesses in real terms is a financial system that is not financing investment, and an economy that is not financing investment is not building the productive capacity that future growth requires.
Demand-Side and Supply-Side Constraints Together
The record-low credit figure reflects two distinct problems operating simultaneously. On the demand side, businesses are reluctant to borrow because the investment climate is uncertain and the returns on new capacity appear risky. On the supply side, banks are constrained in their ability to lend by weak balance sheets burdened with non-performing loans. This dual constraint is what makes the problem so resistant to simple fixes: lowering interest rates stimulates neither a borrower who sees no viable project nor a lender whose capital is impaired by legacy bad debt.
Rahman's diagnosis is precise on this point. Lowering interest rates alone cannot fix unreliable energy supplies, weak bank balance sheets or uncertainty about doing business. Each of these is a structural condition that monetary policy cannot reach. Energy reliability determines whether factories can run at capacity; bank balance sheets determine whether credit can flow at all; and business uncertainty determines whether anyone wants to borrow in the first place. Until these conditions improve, credit growth will remain suppressed regardless of the policy rate, and the investment recovery will remain theoretical.
The Real Credit Arithmetic
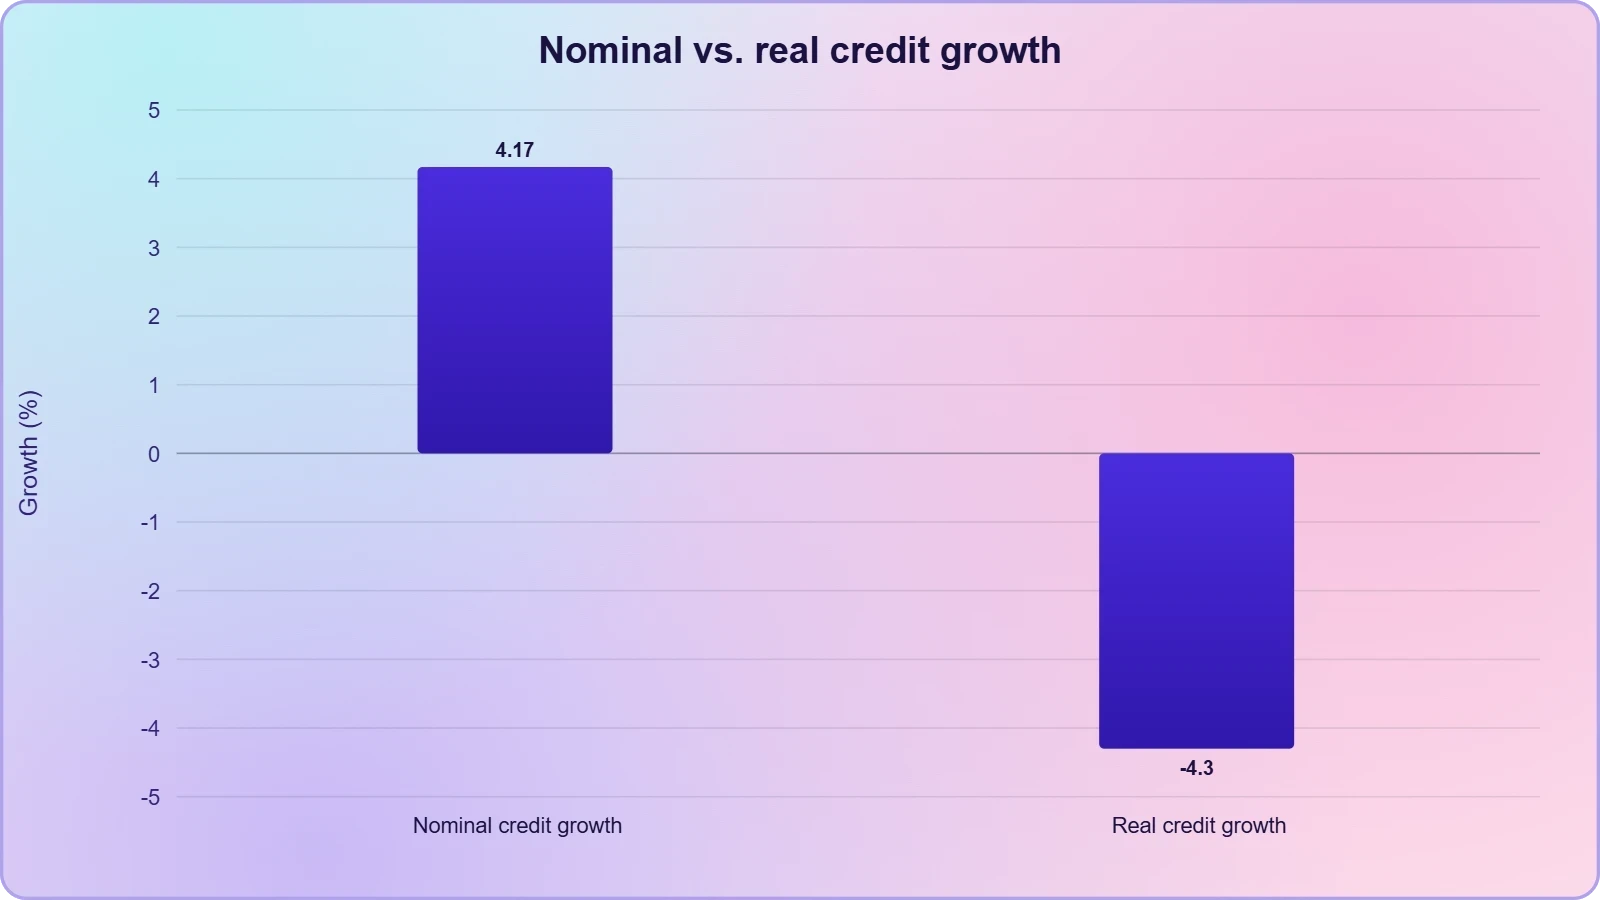
The distinction between nominal and real credit growth is the analytical key to the entire diagnosis, and it deserves to be stated formally. When nominal credit growth falls below the inflation rate, the real stock of credit available to businesses is contracting even though the nominal figure remains positive. The relationship can be expressed simply:
Substituting the reported figures, with nominal credit growth of ##4.17\%## and inflation of approximately ##8.5\%##, yields a real credit growth rate of roughly ##-4.3\%##. This is the arithmetic behind Rahman's warning. An economy whose real credit stock is shrinking by more than four percent annually is, in effect, deleveraging its private sector during a period when it needs investment to recover. The policy implication is uncomfortable but unavoidable: nominal rate adjustments that leave real credit negative are not stimulus, they are the appearance of stimulus.
- 01
- 02
- 03
- 04
The Reform Agenda: Four Priorities and a Graduation Window
The economists did not confine themselves to diagnosis; each offered a prescription, and the prescriptions converge with striking consistency. Abdur Razzaque, chairman of Research and Policy Integration for Development, argued that stabilisation measures and key reforms are needed to revive growth and control inflation, with particular emphasis on strengthening Bangladesh's competitiveness. That emphasis carries added urgency because the country has received an additional three years before graduating from the least developed country category — a window of preferential access that will not remain open indefinitely and must be used to build the productive and institutional capacity to compete without it.
Moazzem's Four-Point Monitoring Framework
Khondaker Golam Moazzem, president of the Knowledge Hub Institute, translated the reform agenda into a concrete monitoring framework with four priorities: steady improvement in foreign exchange reserves, gradual reduction of inflation, reduction of non-performing loans in the banking sector, and improved revenue collection. What distinguishes his contribution is the insistence on monthly targets for each and regular monitoring of progress. This transforms a list of aspirations into an accountability mechanism, because a target without a monitoring cadence is a target that quietly disappears when political attention shifts elsewhere.
The four priorities are also mutually reinforcing rather than independent. Strengthening reserves supports currency stability, which moderates imported inflation. Reducing non-performing loans restores banks' capacity to lend, which supports investment and growth. Improving revenue collection gives the government fiscal space to absorb subsidy pressures without monetisation, which in turn supports inflation control. Treating them as a single coordinated programme rather than four separate initiatives is what makes the framework coherent, and it is precisely the coordination that has been missing from previous reform efforts.
Competitiveness After Least-Developed-Country Graduation
The additional three years before graduation from the least developed country category is simultaneously a reprieve and a warning. Preferential market access has underpinned much of Bangladesh's garment export success, and its eventual withdrawal will expose the sector to tariff schedules that competitors already face. Razzaque's emphasis on competitiveness reforms is therefore not abstract advice but a time-bound imperative: the country has three extra years to build the infrastructure, skills, logistics and institutional quality that will allow its exporters to compete on more than price alone.
Competitiveness, in this context, is a composite of many unglamorous things. Reliable electricity, efficient ports, transparent customs, enforceable contracts and a functioning banking system matter more to exporters than any single headline policy. The garment unrest intersects with this agenda because labour stability is itself a competitiveness variable — buyers price reliability into their sourcing decisions, and a country that cannot guarantee uninterrupted production pays a premium in lost orders. Resolving worker grievances through credible dialogue is therefore not merely a social obligation but an export strategy.
What the Unrest Means for the Recovery Trajectory
The central message that emerges from these assessments is that Bangladesh's recovery is real but shallow, and that the garment unrest is testing whether it can deepen. The external pillars — exports, remittances, reserves — have held, but the domestic engine of investment has stalled, credit is contracting in real terms, and inflation continues to erode household purchasing power. In this configuration, a shock to the garment sector is not a marginal event; it strikes at the one industry whose export earnings underwrite the entire external position, and it does so at the moment when confidence is most fragile.
Mustafizur Rahman's observation that the economy has not yet shown a meaningful recovery is the thread that ties the analysis together. Despite policy measures by the government and the central bank, the recovery has not translated into more investment, more jobs or stronger growth. That gap between policy intent and economic outcome is the defining problem, and it explains why the economists converge on structural reform rather than further stabilisation measures. Stabilisation has done its job in preventing crisis; it cannot, by itself, generate the investment and employment that a genuine recovery requires.
The path forward, as the economists collectively describe it, requires treating the garment unrest as a symptom rather than a standalone crisis. Credible dialogue on wages and cost-of-living concerns protects livelihoods and export competitiveness simultaneously. Monthly monitoring of reserves, inflation, non-performing loans and revenue collection converts reform rhetoric into measurable progress. And the three-year graduation window provides a deadline against which competitiveness reforms can be sequenced. None of these measures is dramatic, and that is precisely the point: the recovery will be secured through disciplined, unglamorous execution rather than through any single decisive intervention.
Frequently Asked Questions
Readers following the Bangladesh garment unrest and its economic implications tend to raise a consistent set of questions. The answers below synthesise the assessments of the four economists cited in the reporting, alongside the macroeconomic data released during the protests. Each response is framed to clarify the underlying mechanics rather than to offer prediction, because the trajectory of the recovery depends heavily on policy choices that have not yet been made and on whether industrial dialogue can be restored quickly enough to prevent lasting damage to buyer relationships.
Why Is Private Sector Credit Growth the Most Watched Indicator?
Private sector credit growth measures whether banks are expanding loans to businesses, which is the primary channel through which savings become investment. At 4.17 percent nominal growth against inflation near 8.5 percent, real credit is contracting by roughly 4.3 percent, meaning the productive sector is effectively deleveraging. This matters more than any single export or remittance figure because it determines whether the economy is building future capacity. A country can post strong export numbers for a time on existing capacity, but without credit-financed investment that capacity eventually depreciates and competitiveness erodes.
Can a Minimum Wage Alone End the Garment Unrest?
A minimum wage addresses the most visible grievance but not the full set. Workers' concerns extend to the cost of living, overtime practices, payment reliability and workplace conditions, and the economists stressed that these legitimate grievances require structured dialogue rather than unilateral settlement. A wage floor that is quickly eroded by inflation also fails to deliver the real income improvement workers are seeking. The durable solution combines an adequate wage, a functioning negotiation mechanism and macroeconomic stability that keeps price growth in check so that nominal gains translate into real purchasing power.
What Does Least-Developed-Country Graduation Mean for Exports?
Graduation from the least developed country category will eventually withdraw the preferential market access that has supported Bangladesh's garment exports. The additional three years granted before graduation is a preparation window, during which the country must build the infrastructure, skills and institutional quality needed to compete under standard tariff schedules. Razzaque's emphasis on competitiveness reforms speaks directly to this deadline. Exporters that have relied on tariff advantage will need productivity, reliability and product upgrading to defend market share once preferences lapse, and the reforms required take years to deliver results.
How Quickly Could the Unrest Affect Export Earnings?
The first-order effect appears within weeks as missed shipments and production shortfalls register in monthly export data. The more consequential second-order effect operates over months and years, as buyers reassess sourcing risk and gradually shift order volumes to alternative suppliers. Buyer confidence is the slowest variable to rebuild once damaged, which is why the economists emphasised dialogue so strongly. A short disruption may leave export trajectories largely intact; a prolonged one risks embedding a reputational discount into Bangladesh's garment offer that no wage settlement can quickly reverse.
From our network :
- The Hidden Cost of AI Convenience: Why Over-Permissioned Agents Are a Security Time BombDiscover why AI agents with excessive permissions create dangerous single points of failure, and learn how implementing least privilege principles can protect your organization from exploitation.
- How AI Agents Will Change the Way We Manage Personal FinancesExplore how AI agents are transforming personal finance through automated budgeting, bill payment, and investment management, while examining the critical security protocols and governance frameworks required for safe deployment.
- Forbidden Matrix Patterns and Visible Lattice Points: A Geometric DictionaryExplore how multidimensional 0–1 matrices encode geometric truths, linking forbidden patterns to visible lattice points and hypergraph theory, with applications in combinatorics and computational geometry.
- The Final Descent: How ESA Retired the Legendary Cluster Constellation After 24 Years of Space Weather ScienceAfter 24 years mapping Earth’s magnetosphere, ESA’s Cluster mission concluded with a precisely controlled reentry over the South Pacific. This analysis explores the scientific legacy, engineering decisions, and debris mitigation principles behind one of space exploration’s most responsible retirements.
- CISA’s Ten-Advisory Wave: Why Generic Patching Fails in OT and How to Build Product-Specific PlaybooksCISA released ten ICS advisories in one week, exposing critical infrastructure risks. Generic patching fails in OT. Learn to build product-specific remediation playbooks.
- Mobile Learning and VR in English: What Global Evidence Reveals About Effective Language TechnologyA systematic review across 14 countries reveals which language-learning technologies genuinely work. Mobile learning, AI, and VR show measurable benefits when pedagogically integrated. This evidence-based guide helps educators and learners select technology that delivers real return on investment.
- University Language Proficiency Exams: Why Institutional Tests Demand Different Preparation Than IELTS and TOEFLDiscover why university-specific language proficiency examinations differ fundamentally from IELTS and TOEFL, and learn strategic preparation approaches for institutional assessment success.
- Live Online English Classes for Kids: Do They Actually Reduce Anxiety?A ten-week study reveals that synchronous online English classes can significantly reduce child language anxiety while improving listening and reading skills. Discover what makes these programs effective and how parents can select the right one.
- Committed Mediterranean Precipitation Decline: Why Emissions Cuts Alone Cannot Restore Winter RainsNew NOAA research reveals that Mediterranean winter rains may decline irreversibly even with emissions cuts. Explore the science of committed climate change and regional impacts.
RESOURCES
- Resources will be updated soon.
- 01
- 02
- 03
- 04
- 05
- 06
- 07
- 08
0 Comments